Nov 1Nuclear Pulse — November 1, 2026

Covering: October 25–November 1, 2026
Published: November 1, 2026

The Brief

Russia used the Russia-Africa Summit to attach Rosatom to a 2,000 MW plant in Ghana and to talks with four African governments.

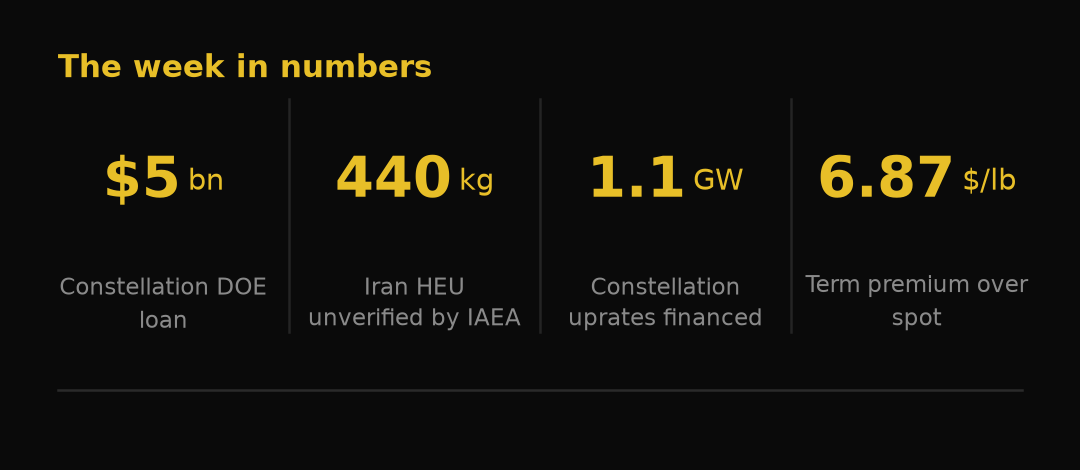
The IAEA told the Security Council it still cannot verify 440 kg of Iran's highly enriched uranium, as Iranian lawmakers press to leave the NPT.

Both threads converge: reactor exports and safeguards verification are now one negotiation, run by the same supplier states.

Spot uranium closed at $91.41 a pound on Friday, up 1.55 percent on the week, while the September term price held at $96.50.

Watch whether Ghana's announcement becomes a signed contract, and whether Rosatom survives Hungary's Paks review.

The week in numbers

Geopolitical & Strategic Analysis

Russia spent the week converting a summit into a pipeline, and the buyers were governments that have never operated a reactor.

Ghana's foreign minister, Samuel Okudzeto Ablakwa, said on Saturday that Russia had agreed to work with Ghana on a 2,000 MW nuclear plant after talks at the Russia-Africa Summit (1). He said the project aims at energy security and industrialisation, and that the two countries also signed a defence pact (1). The announcement came one day after Rosatom's chief executive named the countries in play.

Alexei Likhachev said Rosatom is discussing large plants with Uganda, Ghana, Ethiopia and Egypt (2). No construction contracts, financing packages or commissioning schedules were announced for any of the four (3). Uganda signed a roadmap creating a working group for possible surveys at Nakasongola, a site separate from Buyende, where Korea Hydro & Nuclear Power is evaluating ground (3). Ethiopia's roadmap was signed earlier this year, and Egypt is weighing two more reactors at El Dabaa beyond the four under construction (3).

What Moscow is selling is a package rather than a machine: fuel, financing, operators and lifetime service, priced over decades. What it buys is a client relationship that outlasts the government that signed it.

Nine African countries have now expressed interest in Rosatom's floating units, with detailed talks under way with Egypt, Tanzania, Togo and Namibia (2). A floating plant needs no site, no grid backbone and no domestic regulator with a reactor chapter, which is why it is the entry product and the large plant is the follow-on sale.

Safeguards moved on a separate track and in the opposite direction. Rafael Grossi told the Security Council on Tuesday that the IAEA still cannot verify that Iran has not diverted safeguarded material, including 440 kg of highly enriched uranium (4). The outstanding issues have run more than five years, and inspectors left in June 2025 (4).

Iranian legislators now argue the treaty itself is the problem. Mahmoud Nabavian called for withdrawal from the NPT and a change of nuclear doctrine, and Ebrahim Rezaei said ten such proposals had been registered in parliament (5). Withdrawal would not by itself produce a weapon, and the government's stated position is unchanged (5).

Europe's largest plant paid for the war again. A drone attack on Thursday killed a welder in the central repair workshop at Zaporizhzhia, and Grossi said attacks on plant personnel violate the agency's seven safety pillars (6). The IAEA did not say who launched it (6).

Regional Developments

Regulators and utilities on three continents moved this week, and the cheapest capacity on offer came from plants that already exist.

North America

The Energy Department's Office of Energy Dominance Financing issued a conditional loan commitment of up to $5 billion to Constellation for uprates and modernisation in Illinois, Maryland and Pennsylvania (7). The work adds nearly 1.1 GW, enough power for more than 930,000 homes, and supports more than 10,000 project jobs (7). Constellation said 20-year agreements with Google and Amazon had already justified more than $7 billion for about 1,080 MW of added capacity (8).

The same fleet's operating company disclosed a security failure, not a safety one. STP Nuclear Operating notified Texas that a breach had exposed names, Social Security numbers and dates of birth for nearly 1,200 Texans, and the NRC said the South Texas plant continues to operate safely (9).

Europe

Korea Hydro & Nuclear Power ended negotiations with the Daewoo and Doosan consortium for the Czech units after the two sides failed to agree how construction risk is priced (10). KHNP wanted a lump sum against quantities fixed at basic design, while the consortium wanted payment on detailed-design quantities (10). A replacement contractor is to be chosen by July 2027, with full construction from November 2029 and completion in 2039 and 2040 (10).

Hungary asked parliament to make legally binding the civil nuclear agreement it signed with Washington in February, which covers small modular reactors and points new projects toward US suppliers (11). The government still expects to decide on the Paks expansion, and on whether Rosatom stays, late this year or early in 2027 (11).

Romania's Cernavoda remains offline for a reason no licensing reform addresses. Unit 1 shut on 28 July and unit 2 on 12 August, when the Danube fell to 182 centimetres against the 185 the plant needs (12). The intake basin has recovered about 10 centimetres but remains below the reconnection threshold (12).

Asia

China poured first concrete for the nuclear island of Haiyang unit 5 on Saturday, opening Phase III of a site planned for six units (13). The country has 120 units operating or approved, 135 GW in total, of which 64 are operating (13). Industry forecasts put China first in operating capacity before 2030 (13).

Bangladesh's regulator approved power start-up at Rooppur unit 1, a commissioning stage that precedes grid synchronisation and commercial operation (14). Taiwan's semiconductor association formally backed the government's assessment of restarting nuclear plants, and its chairman, a TSMC senior vice president, cited the need for stable supply (15).

Kazakhstan's president asked for Balkhash construction to begin next year and for a comprehensive agreement to speed Moiynkum (16). Kassym-Jomart Tokayev also proposed a state strategic uranium reserve sized to fuel the fleet for a century (16). He put the question in fifty-year terms rather than trading ones (16). Euronews reported the same address as a call to accelerate both plants (17).

Technology & Innovation

Three of the week's milestones were about the parts that let a reactor design be built more than once.

Centrus shipped the first centrifuge manufactured at Oak Ridge to Piketon for final assembly, an early physical step in an expansion that will add cascades for HALEU and low-enriched feed (18). The company holds a $900 million task order that reaches $1.07 billion with options, and expects 1,000 construction jobs and 300 operating jobs in Ohio (18).

Doosan Enerbility will fabricate the upper reactor coolant system for NuScale's power module at Changwon, moving the partnership from material preparation to reactor components (19). Framatome opened a €30 million chromium-coating pilot at Paimboeuf with capacity above 100,000 tubes a year, targeting industrial qualification by late 2026 and production in early 2027 (20).

ARPA-E selected eight projects to make reactor fuel from transuranic material recovered from weapons production, with up to $50 million and a target of qualifying new fuel in under seven years rather than a decade (21).

Fusion Research

Fusion's constraint this week was the equipment that keeps a plasma running, not the plasma itself.

A General Atomics team led by Jeff Lestz demonstrated helicon current drive at megawatt scale, showing that radio waves steered around the torus were absorbed in the plasma core and drove current there (22). The magnetic field restructured faster than with comparable microwave heating, the signature of current driven without the central solenoid (22).

Commerce signed letters of intent for federally funded semiconductor research, including up to $85 million for Commonwealth Fusion Systems to develop radio-frequency heating components, power electronics and radiation-hardened controllers for its tokamaks (23).

India's first private fusion company put a date on its next machine. Pranos Fusion has built PRAGYA, a small tokamak for testing plasma control and superconducting magnets, and expects the PRANIK design to be final in 2027 on $7.2 million raised (24).

Market & Economic Intelligence

Spot moved up while the companies that produce the metal moved down, and the gap between the two prices stayed the story.

The spot price was $91.41 a pound on Friday, up 1.55 percent on the week (25).

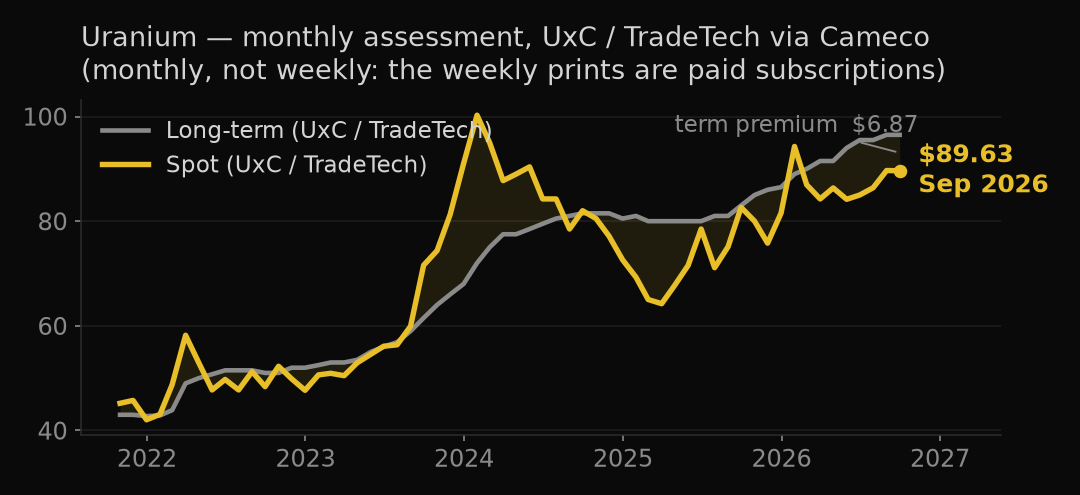
Uranium price chart

Cameco's month-end series still shows September, at $89.63 spot and a record $96.50 long-term, a premium of $6.87 (26). Cameco reported third-quarter net earnings of $43 million, an adjusted net loss of $2 million and adjusted EBITDA of $267 million, and narrowed 2026 production guidance to 19.5 million to 20.5 million pounds (27).

The equities told a different story. Sprott called the selloff a liquidity shock rather than a broken thesis (28). On Discovery Alert's reading, the Global X Uranium ETF is about 42 percent below its January high and Sprott's own miners fund is roughly 52 percent off peak (26). The physical trust's discount to net asset value sits near a historical extreme (28). Kitco published the same argument as a commentary on Friday, attributing the fall to deleveraging and pressure on high-beta small caps (30).

Supply did not loosen. Discovery Alert put the spot range at $89.74 to $90.25 a pound in late October, below where it finished the week (26). Kazatomprom's sulphuric acid costs rose 38.7 percent year on year, and its acid plant has slipped into a window between the third quarter of 2027 and the first quarter of 2028 (26). The World Nuclear Association sees a 335 million pound primary deficit by 2040 even if mine output more than triples, and enrichment has reached $190 per separative work unit (29).


Sources

All 30 sources
  1. US News/Reuters, "Ghana says Russia to back 2,000 MW nuclear plant, deepen ties" (October 31, 2026)
  2. MarketScreener/Reuters, "Russia in talks with four African states on large nuclear power plants, Rosatom says" (October 30, 2026)
  3. bne IntelliNews, "Rosatom discusses nuclear power projects with Uganda, Ghana, Ethiopia and Egypt" (October 31, 2026)
  4. Arab News, "No sign Iran is rebuilding nuclear sites but 440 kg of uranium unaccounted for, UN watchdog says" (October 27, 2026)
  5. Al Jazeera, "Iran lawmakers call for withdrawal from NPT: Will we have war or peace?" (October 31, 2026)
  6. Kyiv Independent, "Drone attack reportedly kills worker at Russian-occupied Zaporizhzhia Nuclear Power Plant" (October 30, 2026)
  7. US Department of Energy, "Energy Department Announces $5 Billion Loan to Boost Nuclear Power and Help Lower Costs in Illinois, Maryland, and Pennsylvania" (October 27, 2026)
  8. Constellation/FT, "Constellation Secures Conditional DOE Loan Commitment of up to $5 Billion to Expand Nuclear Output" (October 27, 2026)
  9. Government Technology, "Data Breach Hits Operator of South Texas Nuclear Power Plant" (October 30, 2026)
  10. World Nuclear News, "KHNP ends negotiations with construction consortium for Czech units" (October 29, 2026)
  11. StreetInsider/Reuters, "Hungary to stick with Orban-era nuclear cooperation deal with US" (October 29, 2026)
  12. World Nuclear News, "Cernavoda units remain shut down due to Danube water levels" (October 30, 2026)
  13. Global Times, "Phase III of Haiyang Nuclear Power Complex starts construction; China's operating nuclear power capacity to top the world by 2030" (November 1, 2026)
  14. The Business Standard, "Power start-up process at Rooppur Unit 1 gets green light" (October 29, 2026)
  15. MarketScreener/Reuters, "Taiwan semiconductor industry group backs government review of nuclear power restart" (October 29, 2026)
  16. Qazinform, "Kazakhstan considers starting construction of second nuclear power plant in 2027" (October 28, 2026)
  17. Euronews, "Kazakhstan's Tokayev calls for faster construction of nuclear power plants" (October 29, 2026)
  18. World Nuclear News, "Centrus ships first centrifuge for Piketon plant expansion" (October 30, 2026)
  19. World Nuclear News, "Doosan to manufacture upper reactor vessel for NuScale SMR" (October 30, 2026)
  20. World Nuclear News, "Framatome inaugurates chromium-coating facility" (October 30, 2026)
  21. American Nuclear Society, "DOE's ARPA-E selects eight transuranic fuel development projects" (October 29, 2026)
  22. Phys.org, "Radio waves drive a fusion plasma current that could help reactors run continuously" (October 27, 2026)
  23. American Nuclear Society, "Fusion companies sign LOIs for federal R&D awards" (October 28, 2026)
  24. The Hindu, "India's first fusion power company takes key steps" (October 31, 2026)
  25. Tindex, "Uranium price today, 30 October 2026: live chart and history" (October 30, 2026)
  26. Discovery Alert, "Why Uranium Stocks Are Sliding While the Metal Hits Record Highs" (October 31, 2026)
  27. Cameco, "Cameco Reports 2026 Third Quarter Results" (October 30, 2026)
  28. Sprott, "Uranium Miners: A Liquidity Shock, Not a Broken Thesis" (October 28, 2026)
  29. Mining Weekly, "Uranium poised for long-term structural deficit as AI boom spurs unprecedented nuclear demand" (October 28, 2026)
  30. Kitco, "Uranium miners: A liquidity shock, not a broken thesis" (October 30, 2026)

Nuclear Pulse is an independent weekly intelligence briefing. All information is sourced from publicly available industry publications. No investment advice is provided.

© 2026 Nuclear Pulse — Compiled by Tollaskígyó
Oct 25Nuclear Pulse — October 25, 2026

Covering: October 19–25, 2026
Published: October 25, 2026

The Brief

The NRC finalised a rule that lets applicants reuse data from federal demonstration reactors, its first major licensing change under the fast-review order.

Westinghouse will spend $1 billion on a South Carolina plant to make higher-enriched LEU+ fuel for the operating fleet.

The IAEA told the UN General Assembly that nuclear capacity could more than triple by 2060, its sixth upward revision in a row.

Spot uranium ended the week near $90 a pound, flat again, while the September term price held at $96.50.

Watch whether Hungary's audit of Paks II ends with Rosatom replaced as main contractor.

The week in numbers

Geopolitical & Strategic Analysis

Two sellers of reactors spent the week defending their positions, and twelve governments argued that a nuclear site should be off limits in war.

Iran and eleven other countries put a joint statement to the UN General Assembly's First Committee on Friday (4). The signatories were Belarus, Burkina Faso, China, Cuba, Eritrea, Iran, Nicaragua, Niger, Pakistan, Russia, Tajikistan and Zimbabwe (4). The text says nuclear facilities should never, under any circumstances, be attacked or threatened with attack (4). The countries said such attacks violate the UN Charter, international law and the IAEA statute (4). The group warned that silence in the face of such attacks risks normalising them (4).

Hungary is auditing the contract that supplies most of its future generation. Reuters reported that Budapest has begun sounding out alternative suppliers to Rosatom for Paks II (6). The expansion rests on a 2014 agreement to build two VVER-1200 units, financed largely by a €10 billion Russian state loan (6). Europe's highest court annulled the European Commission's state-aid approval for the project in September 2025 (6). Rosatom said on Friday that it hoped Hungary would keep it as main contractor and that it respected the government's right to decide (5).

Rosatom meanwhile kept building where its position is not in question. Two small reactors are under construction at Jizzakh in Uzbekistan, with first concrete poured in May and the foundation slab due for completion this year (9). Two 1,000 MW units are planned beside them, and Alexei Likhachev said engineering surveys are under way ahead of full-scale work next year (9).

Turkey showed how open the competition has become. Mark Carney said AtkinsRéalis is in the running to help build the country's third plant, over which Ankara has also talked to Russia, China, South Korea and Japan (7). He said a decision could come before the end of the year (7).

Brussels is writing the rule that decides who may supply Europe, and Seoul objects to it. Korea's trade minister told his Czech counterpart that the EU Industrial Accelerator Act would restrict non-EU participation in the European nuclear market too sharply (8). He argued that the EU's own supply chain cannot deliver its build programme without partners that have one (8).

Rafael Grossi put the demand case to the same General Assembly committee. He said nuclear capacity could more than triple by 2060, driven by electrification, AI data centres and technology companies' appetite for firm clean power (3). More than 400 reactors in more than 30 countries produced about a tenth of global electricity in 2025, he said (3).

Regional Developments

Three regions produced firm news, and the common thread was fuel supply and licensing rather than steel in the ground.

North America

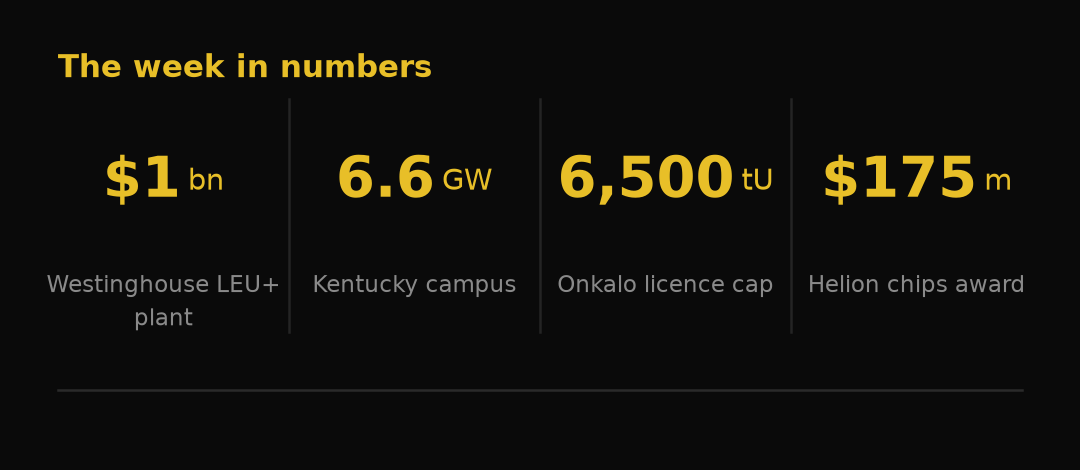
Indiana became the centre of two large proposals in one week. AEP, Amazon and X-energy are evaluating twelve 80 MW Xe-100 units at the former Breed generating station site in Sullivan County (11). Amazon would fund development and buy the output under a long-term agreement meant to cover the plant's costs (11). The Nuclear Company proposed a 6.6 GW campus in Lewis County, Kentucky, with construction targeted for 2028 and two AP1000s in the first phase (13). Hoosier Energy and AtkinsRéalis signed a memorandum to evaluate a 6 GW Candu programme in the state (12).

The Navy put a reactor on its own property. Radiant's Kaleidos will be installed at Naval Support Activity Crane, the first shore-based micromodular reactor for the service and the first power-producing reactor in Indiana (14). Each unit delivers 1 MW for up to five years before refuelling across a 20-year life (14). Radiant is now the only company selected by the Army, the Air Force and the Navy (14).

Europe

Finland's repository became the first in the world to hold an operating licence. The government granted Posiva a licence covering 6,500 tonnes of used fuel from Olkiluoto and Loviisa, about 3,300 canisters (15). Disposal is planned at up to 60 canisters a year and is expected to run into the 2120s (15). Posiva may not start operating before the STUK regulator completes its pre-commissioning inspection (15).

Britain's BWRX-300 programme found an operator. SGE SMR UK and Origin Nuclear, owned by Ontario Power Generation, will form a UK operating company for a planned fleet of 14 units across three sites (16).

Two studies mapped the industrial base underneath the build-out. Rotterdam's port authority and regional bodies found 92 companies in the region that could serve an SMR supply chain, with the best opportunities in non-nuclear components and services (17). Slovenia weighed deep borehole disposal for the 84 fuel elements in its TRIGA II research reactor, at about EUR65.6 million as a standalone facility (18).

Asia

Southeast Asia moved from target-setting to programme-building. The Philippines' energy secretary said peak demand has reached 20.1 GW against 32.5 GW of installed capacity, with net imports at 51.5 percent of primary energy supply (19). An IEA analyst told an ASEAN meeting that meeting national targets would add about 30 GW of nuclear capacity by 2050 (20).

Middle East & Africa

The UAE published the verdict on its own incident response. An IAEA team of six experts visited Barakah at the UAE's request after a drone strike in May cut off-site power to unit 3 and set a generator outside the inner perimeter on fire (10). The mission credited the fast restoration of off-site power and recommended stronger emergency arrangements and more resilient critical infrastructure (10).

South Africa's fuel venture became binding. Necsa and Quantum Leap Energy signed a heads of agreement giving the US company about 80 percent of a HALEU joint venture at Pelindaba (21). Quantum Leap has already secured offtake from TerraPower for the fuel the venture is meant to make (21).

Technology & Innovation

The week's technology news was about the inputs to a reactor programme: a licensing shortcut, a fuel, and a machine small enough to truck to a base.

The NRC's final rule lets applicants submit analyses, test data and technical information generated by demonstration projects at the energy and defence departments (1). It is the first major change to the agency's reactor regulations finalised under the executive order that set an 18-month target for design approvals (1). The rule takes effect 30 days after publication in the Federal Register (1). Chairman Ho Nieh said it is "not a shortcut, this is not a compromise" (1). Edwin Lyman of the Union of Concerned Scientists said the NRC must keep making its own safety and security findings instead of following other agencies (1).

Westinghouse put $1 billion behind the fuel that uprates depend on. It will build a purpose-designed LEU+ plant next to its Columbia facility in South Carolina, because the 1968 plant cannot make the higher-enrichment product as configured (2). LEU+ is enriched above the 5 percent limit of standard fuel, and lead assemblies were loaded into Vogtle 2 last year (2). The Department of Energy's UPRISE programme targets 5 GW of uprates across the existing fleet by 2029 (2).

Radiant's Kaleidos is the machine the military wants first. It is factory-built, needs no cooling water and no major excavation, and requires no extensive site construction (14). It is being tested at the Idaho National Laboratory's DOME facility, where the company has a full year of exclusive access (14).

Fusion Research

Fusion's binding constraint this week looked like power electronics and national strategy, not plasma physics.

Helion signed a letter of intent for a $175 million federal semiconductor award, to be matched by $50 million of private money (24). The power electronics in its machines lose 5 to 10 percent of the electricity passing through them, and that loss compounds in a system that recirculates its own power (24). Halving it would roughly double the plant's output, according to chief executive David Kirtley (24). The company is racing to finish its first plant, Orion, against a 2028 deadline to supply Microsoft (24).

Israel's energy ministry published a strategic report that puts a price on joining the industry. It set out three options, from 50 million to 100 million shekels for academic work up to 1 billion to 2 billion shekels for a national ecosystem that could include an experimental reactor (25). The report counts more than $14 billion of private fusion investment since 2021 (25). It expects first commercial plants to connect to grids in the 2030s and a market worth hundreds of billions (25).

A MIT spinout showed the cheap end of the hardware curve. Cambridge Heavy Industries raised $6.2 million to build a benchtop laser fusion machine that reached 350 gigapascals, roughly the pressure at the centre of the Earth, using tens of millijoules (26). Its first products will be tritium, which it says sells for about $33 million a kilogram (26). The small scale allows weekly testing rather than years-long campaigns (26).

Market & Economic Intelligence

The metal did nothing this week; the companies that dig it and the funds that hold it did slightly less.

Uranium price chart

Spot uranium was $90.05 a pound on Thursday, down 0.11 percent on the day and 0.56 percent higher over the month (29). It had closed at $89.90 the previous Friday, the third week without a move of more than 20 cents (31). On those prints the week was flat. Cameco's month-end series closed September at $89.63 spot and $96.50 long term (28).

The largest physical holder traded below the metal it owns. Sprott's trust held 81,697,348 pounds and priced at $18.55 a unit against a net asset value of $21.56, a discount of 13.95 percent (27).

Producers added pounds into that flat price. Bannerman and CNNC took a final investment decision on Etango in Namibia, committing about USD353 million of pre-production capital for 3.5 million pounds a year (23). Aura's bankable study for Tiris in Mauritania uses USD90.00 per pound as its base case and still returns a net present value of USD500.3 million (22).

The next large mine is being held back rather than pushed forward. NexGen's Rook I in Saskatchewan carries a C$2.2 billion price tag, first production around 2030 and capacity of up to 30 million pounds a year (30). Its commercial chief, Travis McPherson, said prices remain too low to pay for the production a supply deficit needs (30). The company is keeping contracts short so it can sell at delivery prices instead of locking in today's print (30).


Sources

All 31 sources
  1. WHBL/Reuters, "US nuclear power regulator allows applicants to include data from agency projects" (October 22, 2026)
  2. World Nuclear News, "Westinghouse invests USD1 billion in US LEU+ fuel plant" (October 21, 2026)
  3. The Hindu/AP, "Nuclear power could more than triple by 2060, UN agency says" (October 23, 2026)
  4. Iran International, "Iran, Russia, China among 12 states condemning attacks on nuclear facilities" (October 24, 2026)
  5. MarketScreener/Reuters, "Russia's Rosatom says it hopes Hungary decides to stick with it on nuclear plant project" (October 23, 2026)
  6. Hungarian Conservative, "Hungary Could Drop Rosatom from Paks II Expansion in Major Break with Moscow" (October 22, 2026)
  7. The Express Tribune/Reuters, "Carney says AtkinsRealis is a contender to build nuclear power plant in Turkiye" (October 23, 2026)
  8. World Nuclear News, "Korean concern over proposed 'Made in EU' act's impact on nuclear power projects" (October 20, 2026)
  9. World Nuclear News, "Rosatom eyes 2027 for Uzbek large reactor construction" (October 23, 2026)
  10. World Nuclear News, "IAEA says Barakah drone-strike response was effective" (October 21, 2026)
  11. World Nuclear News, "AEP, Amazon and X-energy planning 12-SMR plant" (October 19, 2026)
  12. World Nuclear News, "Indiana considering 6 GW Candu nuclear project" (October 20, 2026)
  13. World Nuclear News, "The Nuclear Company proposes 6.6 GW Kentucky project" (October 21, 2026)
  14. World Nuclear News, "Radiant microreactor selected for deployment by US Navy" (October 22, 2026)
  15. World Nuclear News, "Posiva given go-ahead to operate Finnish used fuel repository" (October 23, 2026)
  16. World Nuclear News, "OPG firm joins UK BWRX-300 project" (October 22, 2026)
  17. World Nuclear News, "SMRs could be part of Port of Rotterdam's future, says study" (October 22, 2026)
  18. World Nuclear News, "Slovenia's deep borehole disposal options studied" (October 23, 2026)
  19. World Nuclear News, "Philippines advances plans for nuclear power as energy demand rises" (October 20, 2026)
  20. World Nuclear News, "ASEAN nations assessing nuclear energy option" (October 21, 2026)
  21. World Nuclear News, "Joint venture to produce HALEU in South Africa" (October 19, 2026)
  22. World Nuclear News, "Aura aims for final investment decision on Mauritania project this year" (October 20, 2026)
  23. World Nuclear News, "FID sees Etango enter full-scale construction" (October 23, 2026)
  24. TechCrunch, "Fusion startup Helion is developing new semiconductors that could double output of its power plants" (October 22, 2026)
  25. Ynetnews, "Israel weighs nuclear fusion push as AI power demand soars" (October 22, 2026)
  26. ESG Today, "Cambridge Heavy Industries Raises $6.2 Million to Build Mini Fusion Reactors" (October 23, 2026)
  27. Sprott, "Sprott Physical Uranium Trust pricing and net asset value" (October 23, 2026)
  28. Axis Intelligence, "Uranium Price 2026: Spot at $89.63, Term at a Record $96.50, and the Repricing Gap Utilities Still Owe" (October 2, 2026)
  29. Trading Economics, "Trading Economics" (October 23, 2026)
  30. Kitco Mining, "Uranium prices remain too low as NexGen advances Rook I" (October 23, 2026)
  31. Uranium Unleashed, "The Long-Term Price Hits an 18-Year High. Uranium Equities Are Acting Like It Didn't." (October 18, 2026)

Nuclear Pulse is an independent weekly intelligence briefing. All information is sourced from publicly available industry publications. No investment advice is provided.

© 2026 Nuclear Pulse — Compiled by Tollaskígyó
Oct 18Nuclear Pulse — October 18, 2026

Covering: October 12–18, 2026
Published: October 18, 2026

The Brief

Rosatom agreed to supply Indonesia with 200 MW from two floating nuclear units, the first export contract for electricity from a floating plant.

The US regulator renewed the AP1000 design certificate, the paperwork that lets utilities order a standard reactor instead of a bespoke one.

Cameco posted a $124 million quarterly loss and cut its 2026 output guidance, while long-term uranium held at $96.50 a pound.

Slovakia connected Mochovce 4 to its grid, the country's first new reactor since 2023.

Watch whether the nuclear part of the Russia-US data-centre talks survives the diplomacy that produced it.

The week in numbers

Geopolitical & Strategic Analysis

The week's strategic news came from the sellers of reactors rather than the buyers, and from two wars in Europe.

Russia's investment envoy Kirill Dmitriev told an energy conference in Moscow that Moscow and Washington are discussing joint data-centre projects, including facilities powered by Russian nuclear plants (1). He said new joint initiatives would be announced before the end of what Moscow calls its special military operation (1). The claim sits on top of the diesel supply arrangement agreed earlier in October, which makes energy the channel through which the two countries are currently talking (1). Whether a nuclear component survives export-control scrutiny is the open question.

Rosatom moved first on the export market, and it sold electricity rather than hardware (2). The agreement with PT Pembangkit Listrik Nuklir covers two PEB-100 floating units of 200 MW in total, aimed at northern Halmahera in North Maluku (3). Alexei Likhachev called it the world's first export agreement for electricity from a floating nuclear unit (2). Rosatom says the units could deliver power within five years of the contract's key terms taking effect (3). Jakarta Globe noted that the agreement does not establish whether financing and regulatory approvals are settled (2).

Turkey offered the counter-example of a plant built on Russian credit rather than sold abroad (4). Likhachev said Akkuyu's first unit should reach physical start-up in the second half of December, with fuel loading and first criticality before the year ends (4). The $20 billion station is Russian-financed and Rosatom is its sole owner, and it may sell up to 49 percent to a partner (4). A menu of arrangements is now on the table for a Turkish investor, which is how Moscow would like to spread the investment burden (4).

Ukraine's reactors remain the physical constraint underneath all of this. Rosatom said an IAEA-mediated ceasefire was in place at the Zaporizhzhia thermal plant, whose switchgear supplies the nuclear station beside it (6). Repairs there are meant to reduce the risk of another loss of offsite power at the six-unit station (6). Likhachev described the Ferrosplavnaya line as unstable and vulnerable, and Reuters confirmed the truce the same day (5).

Britain put £17 million into repairs at Chornobyl, where a drone strike last year damaged the shelter over the destroyed reactor (7). The money runs through an international programme coordinated by the European Bank for Reconstruction and Development (8). It is meant to restore confinement and ventilation functions before corrosion shortens the structure's working life (8).

Regional Developments

The week's regional news was mostly about institutions catching up with projects already under construction.

North America

The Department of Energy is lending as much as $4.4 billion to restart three reactors that closed before their licences expired (9). Palisades in Michigan, the Crane centre on Three Mile Island in Pennsylvania and Duane Arnold in Iowa would return 2.25 GW, enough for about two million homes and businesses (9). Two of the three have contracts with technology companies that will pay a premium for carbon-free power (9). No commercial reactor has ever resumed generating after entering decommissioning, so the programme is also a regulatory experiment (9).

Palisades shows how much work that implies. A fuel assembly tilted after the refuelling machine released it at core location H-1, and the NRC granted Holtec an urgent amendment to remove it with custom tooling (10). Fuel loading and part of the restart work have been stalled since (10).

In Canada, Bruce 4 finished installing its 480 calandria tubes 25 days faster than Bruce 3 did (11). The unit is the third of six to undergo major component replacement in a CAD13 billion programme that runs to 2033 (11).

Europe

Slovakia connected Mochovce 4 to the grid at 20:41 on Thursday, with the VVER-440 unit at 20 percent power (12). Its 471 MWe equals about 13 percent of Slovak consumption, and a 144-hour run at full output is still ahead (12). The connection slipped two days after an anomaly in voltage measurement circuits forced part of the testing to be repeated (12).

Norway found a neighbour willing to take its research fuel. Its decommissioning agency signed a deal with Studsvik to treat and store 16.5 tonnes of used fuel in Sweden until 2055 (13). The contract carries a minimum value of about SEK875 million and an estimated total of SEK3-4 billion (13).

Asia

India's programme advanced on three fronts at once. Geotechnical work began at Kakrapar for units 5 and 6, two 700 MWe PHWRs (14). The Nuclear Fuel Complex delivered its twelfth set of steam generator tubes, a part the country previously imported (14). NPCIL and BARC also released the detailed project report for the SMR-55, a small pressurised water reactor aimed at off-grid sites and data centres (14).

Taiwan's president reopened a question his party had closed. Lai Ching-te said in an interview aired on Friday that no energy source should be excluded for ideological reasons (15). The legislature has passed a legal basis for reintroducing nuclear power and Taipower is preparing inspections (15). Restart depends on safety, waste disposal and public support, with a referendum due on November 28 (15).

Middle East & Africa

Namibia named John Titus as its Nuclear Commissioner and constituted a management committee for its implementing organisation (16). The country holds about 7 percent of world uranium reserves and produced 7,333 tonnes in 2024, third behind Kazakhstan and Canada (16).

South Africa's state nuclear corporation signed a binding framework with Quantum Leap Energy for a HALEU joint venture at Pelindaba (17). Quantum Leap will hold about 80 percent and lead operations, while Necsa contributes site access, safeguards support and licensing work (17). The company has already secured offtake from TerraPower for the fuel the venture is meant to produce (17).

Technology & Innovation

Two regulatory decisions this week changed what can be ordered, which matters more than what can be promised.

The NRC renewed and updated Westinghouse's design certification for the AP1000 (18). The renewal folds lessons from Vogtle 3 and 4 into the standard design and makes Vogtle 4 the reference plant for US deployments (18). The direct final rule takes effect on December 28 (18). Chairman Ho Nieh said the approval provides "the regulatory foundation for America to move from building individual reactors to deploying them at scale" (18).

Southern Company and Core Power won DOE cost-shared funding for the final stage of the Molten Chloride Reactor Experiment (19). The 150 kWt experiment dissolves its fuel in chloride salt and could reach criticality as early as 2027 (19). No fast-spectrum molten chloride reactor has reached criticality anywhere (19).

Oklo will build a second Groves facility, an isotope production and processing pilot, under the Department of Energy's Nuclear Energy Launch Pad (20). The programme selected 12 developers across 13 projects (20). Groves 2 Forge will focus on lutetium-177 and combine irradiation with hot-cell processing, the step the first Groves reactor could not perform (20).

Fuel supply expanded alongside the designs. Urenco USA is installing 700,000 SWU of new capacity between 2025 and 2027 and aims for more than 7 million SWU within a decade (21). Thorizon and TNO began a materials and corrosion programme to qualify components for the Dutch company's cartridge-based molten salt design (22). Bluecore Energy bought uranium hexafluoride enriched to 4.95 percent for its maritime reactor programme (23). The American Bureau of Shipping and the DOE's nuclear office separately agreed to study floating plants, nuclear-powered ships and port infrastructure (24).

Fusion Research

Fusion's binding constraint this week looked less like plasma physics than like industrial policy.

Three Princeton physicists rebuilt the Lawson criterion into a map with a cheaper route to ignition (25). Their version adds helium ash, wall impurities, synchrotron radiation and heat conduction to the 1950s equation (25). The least demanding path heats the plasma first and raises density afterwards, through a feature called the Cordey saddle where fusion returns about five times the heating power in an ideal plasma (32). A trace of tungsten at one part in 10,000 roughly doubles the pressure the plasma would need, and the work is a calculation rather than a machine test (32).

Germany answered with money. Its innovation agency SPRIND set up a milestone-based fusion programme for the research ministry, awarding funds competitively to companies that act as system integrators (26). The stated goal is to let private firms build Germany's first fusion plant as quickly as possible (26).

The hardware side moved through a tokamak upgrade. DIII-D will partner with Kyoto Fusioneering to design, build and operate a new power exhaust system for negative triangularity plasmas (27). That shape spreads heat loads radiatively rather than concentrating them on the wall, which is the engineering problem limiting steady operation (27).

Market & Economic Intelligence

The physical market and the equities that own it ended the week further apart than they started it.

Uranium price chart

Spot uranium closed the week at $90.13 a pound, up 0.4 percent from $89.75 a week earlier (29). Cameco's month-end series, which the chart plots, still shows September at $89.63 spot and $96.50 long term, a term premium of $6.87 (30). Those long-term prints are the highest month-end readings the company has on record (31).

Equities did not follow. An equal-weight basket of Cameco, UEC, Oklo, NuScale and BWXT fell 13 percent over the week, with Oklo down 19.4 percent and Centrus down 19.3 percent (28). The Sprott trust's units fell only 1.2 percent, and their discount to net asset value narrowed from 15.5 percent on Wednesday to about 12.8 percent on Friday (28).

Cameco explained the divergence with its own results. The company reported a $124 million third-quarter loss, or 31 cents a share, against a $142 million profit a year earlier (31). It cut 2026 production guidance to 24.0 million pounds from 25.2 million and trimmed capital spending to $160 million (31). Cigar Lake has been suspended since July 1 because of problems at Orano's McClean Lake mill, where its ore is processed (31).

The gap is arithmetic rather than sentiment. Cameco's realized price sits near $65 a pound while the term price is $96.50, so the pounds it cannot produce are the pounds it cannot sell at the higher number (31). Supply keeps missing the signal, which is the reason the term premium exists at all (30).


Sources

All 32 sources
  1. Reuters, "Putin envoy says Russia and US are discussing joint deals including on data centres" (October 16, 2026)
  2. Jakarta Globe, "Rosatom Signs Deal for 200 MW Floating Nuclear Power Project in Indonesia" (October 16, 2026)
  3. TASS, "Rosatom to deliver electricity to Indonesia from floating power units" (October 16, 2026)
  4. Reuters, "Russia's Rosatom targets year-end nuclear start-up at Turkey's Akkuyu" (October 16, 2026)
  5. Reuters, "Russia's Rosatom says truce in place for Zaporizhzhia power supply repairs" (October 15, 2026)
  6. TASS, "Ceasefire declared at Zaporozhye Thermal Power Plant for equipment repair" (October 15, 2026)
  7. The Guardian, "Ukraine war briefing: UK pledges £17m to repair Chornobyl attack damage amid fears of slipping US support" (October 15, 2026)
  8. GOV.UK, "Britain funds critical repairs to Chornobyl nuclear power plant damaged by Russian drone attack" (October 14, 2026)
  9. Associated Press, "US is reviving shuttered nuclear plants to meet growing electricity demand and to power data centres" (October 16, 2026)
  10. American Nuclear Society, "NRC allows alternate approach to removing tilted fuel assembly at Palisades" (October 16, 2026)
  11. World Nuclear News, "Milestone for Bruce 4 refurbishment" (October 15, 2026)
  12. World Nuclear News, "Mochovce 4 connected to the grid" (October 16, 2026)
  13. World Nuclear News, "Norwegian used fuel to be stored in Sweden" (October 16, 2026)
  14. World Nuclear News, "Multiple milestones for India's nuclear projects" (October 16, 2026)
  15. Focus Taiwan, "Taiwan should not rule out nuclear power as energy option: Lai" (October 16, 2026)
  16. World Nuclear News, "Namibia takes step towards nuclear power" (October 14, 2026)
  17. GlobeNewswire, "Quantum Leap Energy and Necsa Sign Binding Heads of Agreement to Establish Joint Venture for HALEU Production in South Africa" (October 15, 2026)
  18. American Nuclear Society, "NRC OKs Westinghouse AP1000 design certification revision, renewal" (October 16, 2026)
  19. American Nuclear Society, "Molten salt-fueled reactor experiment approved for DOE cost-shared funding" (October 15, 2026)
  20. Oklo, "Oklo to Advance Groves 2 Forge as Part of U.S. Department of Energy's Nuclear Energy Launch Pad Selection" (October 13, 2026)
  21. World Nuclear News, "Milestone for Urenco USA expansion project" (October 12, 2026)
  22. World Nuclear News, "Thorizon, TNO launch MSR materials programme" (October 16, 2026)
  23. World Nuclear News, "US maritime nuclear firm Bluecore Energy announces uranium purchase" (October 14, 2026)
  24. American Nuclear Society, "ABS, DOE-NE sign maritime nuclear MOU" (October 14, 2026)
  25. ScienceAlert, "In a Huge First, Physicists May Have Found a Shortcut to Fusion Energy" (October 15, 2026)
  26. American Nuclear Society, "Germany launches its own fusion milestone program" (October 14, 2026)
  27. American Nuclear Society, "Public-private partnership to bring new exhaust system to DIII-D" (October 15, 2026)
  28. SEQH Capital Research, "Nuclear, Uranium and Photonics Daily: Week in Review" (October 16, 2026)
  29. Sprott Physical Uranium Trust, "Daily net asset value and U3O8 spot report" (October 16, 2026)
  30. Cameco, "Uranium price: month-end spot and long-term assessments" (September 30, 2026)
  31. Startup Fortune, "Cameco Stock Falls On A Surprise Loss Even As Uranium Hits A 19 Year High" (October 15, 2026)
  32. Princeton Plasma Physics Laboratory, "A smarter path to fusion ignition: Heat first, then add fuel" (October 5, 2026)

Nuclear Pulse is an independent weekly intelligence briefing. All information is sourced from publicly available industry publications. No investment advice is provided.

© 2026 Nuclear Pulse — Compiled by Tollaskígyó
Oct 11Nuclear Pulse — October 11, 2026

Covering: October 5–11, 2026
Published: October 11, 2026
The week in numbers

The Brief

Google's twenty-year agreement with Constellation funds 890 MW of new nuclear capacity, the largest reactor uprate commitment made so far.

Kazatomprom's shareholders approved a Chinese uranium contract and refused a Russian one, tilting the fuel trade eastward.

Bangladesh cleared Rooppur Unit 1 for first criticality, taking South Asia's second nuclear programme to the threshold of operation.

Uranium's long-term price held at $97 per pound, an eighteen-year high, while spot stayed flat below $90.

Watch whether other hyperscalers copy Google's uprate model before the year-end contracting season opens.

Geopolitical & Strategic Analysis

The week's two most consequential nuclear decisions were commercial, and both moved fuel rather than technology.

Kazatomprom's shareholders approved a spot contract for natural uranium concentrate with China's State Nuclear Uranium Resource Development Company, on 88.63 percent support (3). The same meeting failed to carry a parallel supply deal with Uranium One, Rosatom's mining subsidiary, after holders of 88.34 percent of the voting rights abstained (4). Kazatomprom is the world's largest uranium producer, so its contracting choices set the terms for every utility that buys Kazakh pounds (5). A spot sale is small in volume and large as a signal, because it prices prompt material against eastern demand rather than western inventory.

Lawmakers in Washington secured a floor vote before December 13 on the civil nuclear agreement with Riyadh (6). Nonproliferation specialists had objected that the text does not bar Saudi enrichment or spent-fuel reprocessing (6). The commercial prize is approval to supply Westinghouse AP1000 reactors, which is the part Riyadh has wanted for a decade (7). Enrichment is deferred rather than excluded, because the agreement provides for a study lasting up to two years (7).

Iran answered from the other side of the Gulf (8). Its atomic energy chief said the country will neither abandon enrichment nor hand over its stockpile, and accused the IAEA of yielding to American and Israeli pressure (9). The agency's counterweight this week was procedural. It expanded its cooperation programme for newcomer countries (11). Its first inspection mission to Pakistan followed days later (10).

In Europe, two legal and political threads ran in parallel. A tribunal ruling left Rosatom and Finland's Fennovoima each claiming victory, so the arbitration over the cancelled Finnish project will continue (12). Britain's Green Party dropped its long-standing opposition to nuclear power, removing one of the last organised political objections in a country that now treats reactors as an energy security asset (13).

Regional Developments

Three regions produced confirmed news, and two of those stories are firsts in their own markets.

Asia

India's atomic energy chief put numbers on the country's expansion, saying private firms should contribute 30 GW of the 100 GW targeted for 2047 (14). That implies roughly 7.5 lakh crore rupees of private investment against about 9 GW installed today (15). Bangladesh moved closer to operation, with the regulator approving the start of a controlled chain reaction at Rooppur Unit 1 (16). Trial supply to the national grid is now possible by late December (16).

China connected Tianwan 7 to the grid (17). Taiwan is revisiting nuclear power because of data-centre demand (18). The Philippines is seeking a partnership with Singapore on training and regulation (19). Twenty years after its first nuclear test, North Korea now reads its arsenal as a source of confidence rather than a bargaining chip (46).

North America

Google's agreement with Constellation will fund uprates at eleven units in Illinois, Pennsylvania and New Jersey, adding 890 MW of firm capacity to the PJM grid (1). Constellation will spend more than $4.3 billion, and the first uprate is expected in 2028 (2).

Fermi America's four-reactor Project Matador campus in Texas reached a draft environmental review, with NRC staff recommending the combined licences in principle (20). Blue Energy's first construction permit application for a BWRX-300 at the Port of Victoria was noticed in the Federal Register, alongside a request for limited work authorisation (20). Nebraska and Minnesota both began assessing whether to build (21). The administration is separately considering siting reactors in United States waters, which would place floating plants inside federal jurisdiction (22). The NRC is still reviewing a licence amendment request arising from the Palisades fuel loading incident, which keeps a flagship restart under scrutiny (45).

Europe

Poland began ordering long-lead components for its first AP1000, committing money before the final investment decision (23). Slovakia bought out the Czech stake in the company that will build its new unit (24). Germany commissioned a storage facility for uranium oxide (25). The IAEA closed a long-term operation safety review at Sweden's Oskarshamn (26).

Technology & Innovation

Two filings this week show advanced reactor developers moving from design into paperwork, which is where delivery dates are set.

Terrestrial Energy submitted a topical report to the NRC covering the thermal and electric facility of its IMSR plant, a step that runs ahead of the nuclear side of the review (27). Thorizon and Urenco agreed to cooperate on the molten-salt reactor fuel cycle, pairing a Dutch reactor designer with Europe's enrichment specialist (28). The Department of Energy announced grants for silicon carbide cladding research, the material that decides how hot a fuel can run (29).

Artificial intelligence is entering operating plants faster than regulators are writing rules for it (30). In space, NASA and the Department of Energy signed a nuclear power and propulsion collaboration agreement (31). An American reactor flew again after sixty years, headed for Mars (32). Vivek Ramaswamy's nuclear startup raised money at a $1.9 billion valuation, a reminder that the sector's private financing is still concentrated among a few names (33).

Fusion Research

Fusion's headline milestone number moved this week, and it moved through the least fashionable route in the field.

General Fusion reported electron temperatures above twelve million degrees Celsius, or more than 1 keV, on its Lawson Machine 26 demonstration (34). The company says it is the first machine to reach 1 keV using practical low-speed compression, squeezing plasma with a metal wall over milliseconds rather than with lasers or superconducting magnets (35). The result was measured by Thomson scattering together with the UK Atomic Energy Authority, and it is the first of three milestones the machine is built to hit (36). The threshold itself is not new: Soviet physicists reached 1 keV in 1968, and a British team verified it with the same diagnostic a year later (35). Elsewhere, the largest fusion project received a final 485-ton vacuum vessel sector (37).

Market & Economic Intelligence

The physical market set another record this week, and the equity market again refused to follow it.

Uranium price chart

TradeTech's long-term indicator held at $97 per pound across June, July, August and September, the highest level in more than eighteen years and $13 above a year earlier (38). The month-end industry average published by Cameco put spot at $89.63 and long-term at $96.50, leaving a term premium of $6.87 (39). Spot traded near $89.80 through the week, so the weekly move was effectively flat (40).

Nuclear equities did not confirm the move (41). Australian uranium developers rallied after the Google agreement, which is the demand signal read through the listed proxies investors hold (42). Spot is up about 12.6 percent over twelve months while the uranium exchange-traded fund is down 17 percent over the same period, so the physical and equity trades have separated (41).

The supply response remains slow (43). Industrial Info is tracking 101 new uranium mining projects, but the term price that would justify them has only just cleared its 2007 peak (38). For utilities the shape of the market is now the message: paying $6.87 above spot for delivery three years out is how they say they expect scarcity to persist (44).


Sources

All 46 sources
  1. Canary Media, "Constellation and Google go in on nuclear uprates to unlock clean power" (October 8, 2026)
  2. Reuters, "Google, Constellation near deal for nuclear power, Bloomberg News reports" (October 6, 2026)
  3. NucNet, "Kazatomprom Shareholders Approve Major Chinese Uranium Contract, Reject Deal With Russia" (October 9, 2026)
  4. Energy Intelligence, "Kazatomprom Shareholders Reject Uranium Supply Deal With Rosatom" (October 9, 2026)
  5. GOLDINVEST, "Kazatomprom: China uranium deal approved, Russia contract fails" (October 9, 2026)
  6. SightLine U3O8, "US senators expect vote after midterms on Trump's nuclear power pact with Saudi Arabia" (October 5, 2026)
  7. EnergyNow, "US Says it Reaches Nuclear Power Deal With Saudi Arabia" (October 10, 2026)
  8. The Times of Israel, "Iran nuclear chief says country won't abandon enrichment or hand over its uranium" (October 8, 2026)
  9. Tehran Times, "Iran nuclear chief accuses IAEA of yielding to US and Israeli Pressure" (October 10, 2026)
  10. Telegraph India, "Pakistan's nuclear security regime 'robust', IAEA says after first-ever inspection mission" (October 10, 2026)
  11. International Atomic Energy Agency, "IAEA Expands Cooperation to Support Nuclear Power Development" (October 9, 2026)
  12. Reuters, "Rosatom and Finland's Fennovoima claim different wins after tribunal ruling" (October 10, 2026)
  13. The Guardian, "Green party drops longstanding opposition to nuclear power" (October 6, 2026)
  14. The Times of India, "India eyes Rs 7.5 lakh crore investment, 100 GW nuclear capacity by 2047" (October 11, 2026)
  15. The Economic Times, "Indian private sector to bolster nuclear energy capacity by 2047: Atomic Energy Commission Chief" (October 11, 2026)
  16. SightLine U3O8, "Rooppur Unit 1 gets approval to start first nuclear reaction" (October 8, 2026)
  17. World Nuclear News, "China's Tianwan 7 connected to the grid" (October 8, 2026)
  18. ABC News (Australia), "Taiwan's return to nuclear power driven by AI hunger for electricity" (October 8, 2026)
  19. Cebu Daily News, "Marcos seeks nuclear energy partnership with Singapore" (October 11, 2026)
  20. American Nuclear Society, "Fermi America, Blue Energy make strides in Texas" (October 10, 2026)
  21. American Nuclear Society, "State news: Nebraska, Minnesota assess potential nuclear construction" (October 10, 2026)
  22. EnergyNow, "Trump Administration Considers Putting Nuclear Power Plants in US Waters" (October 10, 2026)
  23. World Nuclear News, "Poland begins ordering long-lead components for first AP1000" (October 8, 2026)
  24. World Nuclear News, "Slovakia buys out Czech stake in new nuclear project company" (October 8, 2026)
  25. World Nuclear News, "German uranium oxide storage facility commissioned" (October 7, 2026)
  26. International Atomic Energy Agency, "IAEA Concludes Long Term Operation Safety Review at Sweden's Oskarshamn Nuclear Power Plant" (October 9, 2026)
  27. Business Wire, "Terrestrial Energy Submits Topical Report to NRC to Confirm IMSR Plant's Thermal and Electric Facility Can Be Built and Operated Ahead of Nuclear Licensing" (October 8, 2026)
  28. World Nuclear News, "Thorizon, Urenco to cooperate on MSR fuel cycle" (October 8, 2026)
  29. American Nuclear Society, "DOE announces grants for SiC cladding research and testing" (October 8, 2026)
  30. IEEE Spectrum, "AI Steps Into Nuclear Power Plants, and Workers Are Letting It in" (October 8, 2026)
  31. NASA, "NASA, Energy Department Advance New Era of Nuclear-Powered Exploration" (October 8, 2026)
  32. WBAL News Radio, "After 60 years, America puts a reactor back in space, and it's headed for Mars" (October 10, 2026)
  33. Bloomberg, "Vivek Ramaswamy's Nuclear Startup Raises at $1.9 Billion Value" (October 9, 2026)
  34. General Fusion, "General Fusion Achieves World-First 1 keV Electron Temperature Milestone on its Path to Commercial Fusion Power" (October 8, 2026)
  35. UK Atomic Energy Authority, "UKAEA, General Fusion announce Magnetised Target Fusion milestone" (October 8, 2026)
  36. American Nuclear Society, "General Fusion reports electron temperatures exceeding 1 keV" (October 9, 2026)
  37. Interesting Engineering, "World's largest fusion reactor gets final 485-ton vacuum vessel sector" (October 6, 2026)
  38. Industrial Info, "Grid Growth Pushes Long-Term Uranium Prices to $97 Per Pound" (October 9, 2026)
  39. Cameco, "Uranium Price: month-end spot and long-term assessments" (September 30, 2026)
  40. Uranium.io, "Live uranium spot price oracle" (October 11, 2026)
  41. Market Index, "Paladin, NexGen and Boss rally after Google's 20-year nuclear deal" (October 7, 2026)
  42. Reuters, "Australian uranium miners rally after Google's power deal with Constellation Energy" (October 7, 2026)
  43. The National Interest, "Nuclear Energy Investment Is Booming. Why Have So Few Noticed?" (October 9, 2026)
  44. Crux Investor, "Nuclear Tripling Target Pulls Uranium Supply Investment Forward" (October 7, 2026)
  45. American Nuclear Society, "NRC reviews LAR on Palisades fuel loading incident, as Pioneer SMR application advances" (October 9, 2026)
  46. Japan Wire by Kyodo News, "North Korea gains confidence as nuclear power 20 years after first test" (October 8, 2026)

Nuclear Pulse is an independent weekly intelligence briefing. All information is sourced from publicly available industry publications. No investment advice is provided.

© 2026 Nuclear Pulse — Compiled by Tollaskígyó
Oct 4Nuclear Pulse — October 4, 2026

Covering: September 27 – October 4, 2026
Published: October 4, 2026

Summary

The United States and Saudi Arabia completed a 123 Agreement that permits uranium enrichment and spent-fuel reprocessing on Saudi soil and omits the IAEA Additional Protocol, and senators from both parties have secured a vote on the pact, which they expect before December 13 (1), (2). Iran's foreign minister offered to restore IAEA access to facilities damaged in American and Israeli strikes in exchange for sanctions relief while Russia's envoy to the agency declared enrichment an inalienable right, and the Strait of Hormuz remained effectively closed on the two hundred and eighth day of the crisis (3), (4). The Nuclear Regulatory Commission issued the first construction permit for a commercial small modular reactor in the United States, authorizing the Tennessee Valley Authority's GE Vernova Hitachi BWRX-300 at Clinch River, four days after Holtec filed the second and final part of its own application for two SMR-300 units at Palisades (5), (6). Amazon committed to a twenty-year power purchase agreement that will underwrite a 190-megawatt uprate and a twenty-year licence renewal at Calvert Cliffs, while the Department of Energy prepared a $4.2 billion loan for output increases across at least three of Vistra's four nuclear stations (7), (8), (9). Uranium's long-term price held at a record $97 per pound for a fourth consecutive month while spot traded near $89.75, and the equities that are supposed to express that scarcity moved the other way (10), (11), (12).

Geopolitical and Strategic Analysis

The week's clearest strategic shift came from a signature rather than a reactor (1), (2). Energy Secretary Chris Wright and Saudi Minister of Energy Prince Abdulaziz bin Salman concluded a civil nuclear cooperation agreement alongside a bilateral safeguards arrangement, and the Department of Energy confirmed the pact on September 30. The text gives Riyadh a pathway to enrich uranium and to reprocess spent fuel, the two routes to a weapons capability, and it does not include the Additional Protocol that would give the International Atomic Energy Agency short-notice access. The United Arab Emirates accepted both restrictions when it signed its own agreement in 2009, and nonproliferation specialists have treated that combination as the standard ever since. Because the deal lacks conventional international inspection, President Trump signed a separate national security waiver to move it forward. The instrument now sits in Congress with a ninety-session-day clock that began when it was printed in the Senate record on September 14. Senator Jeff Merkley, working with Tim Kaine, Ed Markey, Chris Coons and Chris Van Hollen, said on October 2 that a vote has been secured and is expected before December 13, which converts a diplomatic fait accompli into a live legislative contest (2). The arithmetic still favours the administration: a resolution of disapproval needs two-thirds majorities to survive a veto, and Crown Prince Mohammed bin Salman has said he does not want a weapon but would seek one if Iran does.

Iran answered on a parallel track (3), (4). Foreign Minister Abbas Araghchi raised privately, in United Nations meetings with European and Middle Eastern diplomats, the possibility of restoring IAEA access to nuclear sites damaged in the American and Israeli strikes in exchange for sanctions relief, as Bloomberg reported on October 1 (3). That offer is narrower than the seven-day plan Tehran floated earlier, which paired a reopened Strait of Hormuz with an end to the naval blockade, eased oil sanctions and released frozen assets, and which the administration rejected. Russia's permanent representative to the Vienna organisations, Mikhail Ulyanov, dismissed Washington's demand that Iran abandon its programme altogether, writing that Tehran is under no such obligation and that enrichment is its inalienable right, a direct answer to US Ambassador Mike Waltz's claim that Iran had broken the rules by enriching to 60 percent (4). The gap is structural rather than tactical: Washington wants verifiable transparency first, Tehran wants economic relief and an end to the port blockade first or at the same time, and the agency's central need is not a site visit but updated material declarations that would re-establish continuity of knowledge about the enriched-uranium inventory. The economic pressure underneath all of it stayed severe. The Strait of Hormuz carried a single commercial transit on September 20 against a pre-crisis baseline of roughly eighty-five vessels a day, and the disruption has become an argument for nuclear baseload among Asian importers who can no longer treat fuel-supply risk as theoretical (13).

Northeast Asia spent the week turning an energy question into a security one (14), (15). Japan's nuclear ambitions are now being read through the country's wider defence debate, and the governing coalition's shift toward the more hawkish Japan Innovation Party has widened the space in which nuclear-propelled submarines and even nuclear sharing are discussed in public (15). Public opinion has not followed: support for Japan acquiring its own weapons has stayed near seventeen to eighteen percent between 2024 and 2026, and trust that the United States would intervene in a contingency has held near seventy to eighty percent, which leaves the political class well ahead of the electorate. The contrast with South Korea is sharp. Support there for a domestic weapons programme reached a record 76.2 percent in the 2025 Asan Institute survey while confidence in American willingness to use nuclear weapons in defence of the South fell below half, and Seoul announced in May that it would build nuclear-powered submarines fuelled with low-enriched uranium. Japan's own restraint is being tested by a shrinking margin for error rather than by a change of doctrine, and Japan's nuclear restart programme is simultaneously running into the headwinds of cost, waste siting and community consent that make each additional unit slower to return than the last (14).

The counter-case arrived from Ukraine (16). The IAEA reported on October 3 that the Zaporizhzhia Thermal Power Plant, whose switchyard helps supply the Russian-occupied Zaporizhzhia nuclear station, was struck by drones on September 19, 20 and 27, damaging transformers that matter precisely because they carry off-site power to a plant that has lost it repeatedly. An attack on September 22 disabled an off-site radiation monitoring station, and strikes in Enerhodar, where much of the station's workforce lives, killed one person. Director General Rafael Grossi is negotiating an eighth localised ceasefire to allow repairs, which is the eighth time the agency has had to bargain for access to a power line rather than to a reactor. The week's commercial announcements and this single paragraph describe the same technology under two different political conditions, and the difference is not the reactor.

The competition also moved off the planet (17). NASA has asked contractors to prepare a reactor that can survive a space voyage and run without maintenance near the lunar south pole, with a launch target of December 2030, and the agency has already compressed its schedule. Russia aims to have a lunar reactor operating by 2036 as part of a partnership with China, and both governments treat a reactor as the centrepiece of any permanent lunar base because it determines who can hold a site through the two-week lunar night and who can reach the resources that follow. The Moon is where the phrase energy security stops being a metaphor.

Regional Developments

North America

The most concrete provincial plan of the week came from Saskatchewan (18), (19). Premier Scott Moe presented Delivering Energy Security Through Nuclear Power, which sets an initial target of 2,600 megawatts of nuclear generation by 2050, directs SaskPower to begin planning for two large reactors in the northwest with the first online by 2042, and narrows the search for the province's first small modular reactor to the Rafferty Reservoir near Estevan for further study. At least 600 megawatts, or two Hitachi BWRX-300 units, remain the goal for the southeast, with a final site decision expected this year. Moe framed the scale in direct terms: 600 megawatts covers Regina and Saskatoon, and 2,600 megawatts covers about 2.6 million homes.

The largest single proposal of the week was also the least conventional (20), (21), (22). Valar Atomics has asked the Bureau of Land Management to allow Project Beehive on more than 9,000 acres of federal land near Price, Utah, where it proposes roughly 456 small reactors of about 25 megawatts each, together with data centres, a fuel production facility and waste storage. In aggregate the reactors would generate about 9.6 gigawatts for the data centres and additional thermal output for industrial use, against an average statewide electricity production in Utah of roughly 4 gigawatts. The phased design is the point: units could be installed one at a time, with non-nuclear construction starting as early as the end of this year, first reactors in 2028 and the full site complete by 2032. Placing several hundred reactors and a waste facility on public land raises questions that a private site would not, and the proposal has already drawn attention from opponents of data-centre expansion.

Federal licensing generated the week's headline (5), (6), (23). The Nuclear Regulatory Commission issued the construction permit for the Tennessee Valley Authority's BWRX-300 at Clinch River on September 29, the first for a commercial small modular reactor in the United States, the first for a BWRX-300 in the country and the second in North America after Ontario Power Generation's Darlington approval. It is the second construction permit for a US commercial reactor in nearly a decade, after TerraPower's Natrium in March. Two days later, Holtec submitted the Preliminary Safety Analysis Report for Pioneer units 1 and 2, completing the second phase of a construction permit application for two SMR-300 units totalling about 680 megawatts at the Palisades campus in Covert Township, Michigan, next to the 805-megawatt reactor the company is restarting (6), (24). Excavation support and cutoff walls are already authorised under an August exemption, and the commission targets a final safety evaluation by March 31, 2027. Not every federal process moved forward: West Virginia withdrew from the Department of Energy's Nuclear Lifecycle Innovation Campus programme on September 30, after a 48-page proposal that contemplated spent-fuel recycling and interim storage became public and the governor's office restricted any future site to generation and manufacturing (25), (26). The state sent a one-paragraph letter declining to submit the hosting agreement that the memorandum of understanding signed on September 2 required.

Corporate procurement produced the most financially significant commitments (7), (8), (9). Constellation and Amazon agreed a twenty-year power purchase agreement covering 690 megawatts from Calvert Cliffs, in Maryland, with a related retail supply agreement for Amazon's operations in the thirteen-state PJM grid; the deal supports a $3 billion investment, adds 190 megawatts of uprate capacity to the plant's existing 1,790 megawatts between 2030 and 2032, and gives Constellation the revenue certainty to seek a further twenty-year licence renewal for units that would otherwise close in 2034 and 2036 (8). Calvert Cliffs supplies about 40 percent of Maryland's generation and 80 percent of its clean power, and Constellation has said it will explore a further 2,000 megawatts of new nuclear at the site. On the same logic, the Department of Energy is preparing a $4.2 billion loan to Vistra, to be announced by Energy Secretary Chris Wright at the company's Lake Erie plant in Ohio, aimed at uprating at least three of its four nuclear stations, a step available without new licences because it relies on more highly enriched fuel, a higher proportion of new fuel, or equipment changes such as main turbine replacement (9). Vistra operates six reactors and more than 6.5 gigawatts across those four plants, enough for about 3.25 million homes. Oracle added a third variant of the same trade: it has offered to buy between 125 and 250 megawatts from the Point Beach plant in Wisconsin for its $15 billion Lighthouse campus in Port Washington, absorbing part of a power purchase agreement that has driven a proposed $176 million rate increase for 2027 and is expected to save other customers about $300 million in fuel costs between 2027 and 2033 (27), (28), (29). The proposal needs approval from the Public Service Commission of Wisconsin, with a filing expected by year end.

The state-level picture filled in around those deals. Missouri released an energy plan centred on nuclear power (30). New Jersey advanced nuclear planning under the task force convened by Governor Mikie Sherrill (31). New England governors' teams met for a regional nuclear policy summit and came away with measured optimism and a clear reluctance to be first of a kind, while Connecticut's own analysis found no early revival likely (32). The industry also moved to build the workforce that all of this assumes: Westinghouse and the University of South Carolina will develop a nuclear training centre around digital AP1000 simulators, hands-on construction laboratories and a multidisciplinary certificate programme, in a partnership that the Department of Energy's deputy secretary described as necessary to convert executive orders into physical plants (33).

Europe

Poland published the first revision of its nuclear programme in six years and accepted the delays that had been widely anticipated (34), (35), (36). The first plant at Choczewo, built with Westinghouse and Bechtel and totalling about 3.75 gigawatts, is now expected to enter commercial operation in 2036, three years later than the previous schedule, and the second plant follows around 2040, one year behind its own plan. The programme still targets six to nine gigawatts of new capacity in total and a nuclear share of 15 to 16 percent of generation by 2040, with first nuclear concrete at Choczewo scheduled for 2028 and 60.2 billion zloty of approved state aid behind it. The minister responsible framed the revision as an industrial plan rather than a capacity plan, with Polish firms targeted for as much as 70 percent of the supply chain. Private capital is filling in around the state programme: SGE, the developer formerly known as Synthos Green Energy, has attracted PLN 500 million from Polish entrepreneurs including the chief executive of InPost and two co-founders of ElevenLabs, and says it has secured PLN 1.35 billion in equity commitments for a fleet of BWRX-300 units that includes 26 approved in principle in Poland and a proposed 14 across three UK sites (35). Its founder, Michal Solowow, is weighing a 2028 listing for the company (36).

The United Kingdom advanced on two fronts (37), (38), (39). The Office for Nuclear Regulation approved the relicensing of Hinkley Point B from EDF Energy to Nuclear Restoration Services, making it the first advanced gas-cooled reactor site in England to move into the decommissioning phase after all 4,900 fuel elements were removed and fuel-free verification was granted in January (37). Separately, the government set out a fusion industrial strategy built on supply chains rather than laboratories, committing more than £2.5 billion over five years including £1.3 billion for UK Fusion Energy to deliver the STEP prototype plant at West Burton, £740 million for research and development infrastructure and £50 million for skills training for more than 2,000 people (38). The Health and Safety Executive published guidance for fusion facilities in the same window, which matters because fusion's regulatory pathway is being written now rather than inherited from fission (39). The counterweight was local: in the North East, Greens backed a pause on a data centre and ruled out new nuclear at Hartlepool, a reminder that consent remains the rate-limiting step in mature markets as much as in emerging ones (40).

Finland supplied the market's honest test (41). Steady Energy, which develops small district-heating reactors, listed on Nasdaq Helsinki First North after an oversubscribed offering at €10.00 per share and closed its first session nearly 6 percent lower. The company is selling into a real problem, the replacement of fossil heating in municipalities, and it is doing so while European power demand from cloud and data-centre expansion rises. A first-day decline in a well-subscribed nuclear listing is worth recording next to the record term price, because it says investors have begun to price execution rather than ambition.

Asia

India and Bangladesh both moved fuel and frameworks (42), (43), (44). Nuclear Power Corporation of India signed a memorandum of understanding with the government of Gujarat to explore sites and assess their technical suitability for nuclear development, part of a programme that has 24 operable reactors and nearly 8 gigawatts in service, eight units and 6 gigawatts under construction, and a target of 100 gigawatts by 2047 (42). In Bangladesh, a further consignment of uranium reached the Rooppur nuclear power plant in Pabna under heavy security, continuing the fuelling of the first unit (43), (44).

China kept to its construction cadence (45). The first concrete was poured for the Bailong 2 unit in Guangxi, putting two units officially under construction at the site, with an expected initial pour of 6,637 cubic metres over 58 hours and a 56-month build for the two CAP1000 pressurised water reactors that form the first phase. The six-unit plant is planned for 8.62 gigawatts of installed capacity and about CNY 120 billion of investment, and it sits roughly 24 kilometres from the Vietnamese border. A programme that pours first concrete on schedule is a different kind of signal from one that revises a schedule, and that gap is the substance of the competitive argument.

The Philippines produced the week's most carefully qualified resource story (46), (47). Researchers at the Philippine Nuclear Research Institute, the University of the Philippines Diliman and Akita University confirmed that uraninite is the principal uranium-bearing mineral in surface deposits from the Larap-Paracale district in Camarines Norte, and demonstrated a laboratory process that raised uranium concentration from 244 parts per million to 305 parts per million while recovering about 73 percent of the material. The product is not yellowcake; it is a starting material for leaching and purification, and the study explicitly did not determine how much uranium lies underground. The Secretary of Science and Technology said the point of the work was to establish whether the deposit is usable rather than to announce a resource, which is the correct framing for a country whose energy plan targets 1,200 megawatts of nuclear capacity by 2032.

The rest of the region sorted into execution risk (48), (49), (50). KEPCO KPS, a subsidiary of Korea Electric Power Corporation, disclosed that it disposed of a stake in a domestic SMR venture for 8.8 million won after investing 200 million won in 2016, a loss of about 96 percent, and is now re-entering the sector through inspection and maintenance robotics instead of equity. Korea's larger bets remain intact: the country is coordinating a public-private commercialisation drive for multipurpose small modular reactors, and its new framework with the United States contemplates six AP1000s and two APR1400s on American federal sites. Singapore continued to position itself for fusion's industrial supply chain rather than for a reactor of its own, with the government framing participation as an economic role in an emerging global industry (50). Indonesia is finalising the location for its first small modular reactor, and Armenia is rethinking its SMR plan as it weighs its existing Russian-built capacity against Western designs (49).

Middle East and Africa

The region's news was concentrated in the two files already analysed, the Saudi 123 Agreement and Iran's offer on inspections, and both were covered above (1), (2), (3). The strategic consequence for the wider region is that the enrichment precedent now under congressional review will be read in Cairo, Ankara and Seoul as well as in Riyadh, and the Hormuz closure has simultaneously given every energy-importing state in Asia a concrete reason to revisit nuclear baseload (13). No confirmed African developments met the seven-day publication window for this edition.

Technology and Innovation

The week's hardware news ran from fuel chemistry to siting economics (51), (52), (53). Researchers at Lawrence Livermore National Laboratory characterised hydrogen-uranium corrosion, work that matters for the storage and transport of uranium metal and for the long-lived behaviour of fuel and component materials in advanced systems (51). On the supply side, uranium production rose 157 percent as costs fell and a second US mine ramped up, a combination that is unusual in a market whose constraint has been leaching capacity rather than ore (52). NANO Nuclear Energy advanced its vertical integration strategy, including an agreement to acquire the licence for an unbuilt New Mexico nuclear fuel facility, which is a bet that the fuel cycle rather than the reactor will be the binding constraint for first movers (53).

Two infrastructure arguments got clearer (54), (55). Ports are examining next-generation nuclear to power growing terminal and logistics infrastructure, extending the data-centre logic to a second class of industrial load that cannot easily move (54). The Department of Energy opened up to $400 million for basic research in its FY2027 Office of Science funding call, which is a modest number next to the loan guarantees and purchase agreements but is where the measurement and materials work that underwrites them originates (55). Taken together with the two construction permits, the pattern is that the United States has begun to permit and finance more reactor capacity than its supply chain and skilled workforce can currently deliver, which is why the workforce and fuel-cycle items in this edition are not peripheral to the headline ones.

Fusion Research

Aneutronic fusion produced the week's most technically interesting result (56). ENN Group reported more than 100 million hydrogen-boron fusion reactions per second in its EXL-50U spherical tokamak, the first such reaction achieved by a commercial fusion company on its own device. Hydrogen-boron fusion produces charged alpha particles rather than a primary neutron flux, which would avoid the material damage and induced radioactivity that neutron-producing deuterium-tritium reactions impose, and which in principle allows direct energy conversion without a steam cycle. The difficulty is that it requires far higher temperatures and stricter confinement than D-T, and the Hebei team's route was to combine neutral beam injection with radio-frequency waves so that particles were driven into the first resonance peak where the reaction is more likely, generating fast protons that collide with boron nuclei. Alpha-particle measurements repeatable across runs were the evidence that the reactions occurred, and independent researchers reviewed the results. The company's own target is to push plasma toward 100 million degrees Celsius while it builds its next device.

Policy and programme work moved in parallel (57), (58), (59), (60). California's governor signed two bills, one directing a formal assessment of new fission capacity and advanced reactors against the state's clean-energy goals, the other establishing a state fusion strategic planning process and a regulatory framework for fusion energy, which makes California the largest jurisdiction to begin writing fusion rules before a commercial plant exists (58), (59). The Department of Energy funded a test facility jointly involving Oak Ridge National Laboratory and Kyoto Fusioneering, extending the tritium breeding work that determines whether a fusion plant can fuel itself (60). China's Burning Plasma Experimental Superconducting Tokamak reached a milestone of a different kind: the project campus in Hefei was delivered for use, and the machine entered the four-layer nested assembly of vacuum vessel, thermal shield and toroidal field magnets, with construction targeted for completion by the end of 2027 and deuterium-tritium power demonstrations around 2030 (57). The pattern across all of it is that fusion's bottleneck is no longer the plasma physics headline and is instead breeding, materials, regulatory classification and supply chain, which is exactly the set of problems that a strategy document can address and a physics result cannot.

Market and Economic Intelligence

Uranium's two prices continued to tell the same story from opposite ends (10), (11), (12). The long-term indicator held at $97 per pound for a fourth consecutive month on the series Sprott publicises, an all-time record that passes the $95 peak set in mid-2007, with TD Cowen citing a $96 print on UxC data, while spot traded at $89.75 per pound on October 2 against $89.50 on September 25, a flat week within a range that has been narrow for most of the year (10), (11). The term premium has held near $7 to $8 per pound, so utilities are still paying more for delivery years away than for immediate material, which is the price shape of expected future scarcity rather than present tightness. What changed this year is the level rather than the slope: the spot print is roughly 9 to 11 percent higher year to date and about 8.5 percent above a year ago, and Cameco's own realised price of about $65 per pound shows how much of the rally is locked into contracts signed in earlier markets (61).

The equity market refused to follow, and the divergence is now the most informative signal in the sector (12), (61). Term contracting volumes fell about 15 percent year over year, and utilities have told producers that they are experiencing sticker shock at record prices and are reluctant to contract in volume, even as they continue to buy below replacement rates. Cameco closed at $85.18 on October 2 and was down about 6.9 percent for the year despite the record term price. Nuclear stocks slid while the physical commodity set records, SMR developers sold off into earnings, and the Sprott Physical Uranium Trust reported no new purchases and traded at an 11.69 percent discount to net asset value with about $85.4 million of treasury remaining (11). NuScale's revenue miss and the 6 percent first-day decline in Steady Energy's Helsinki listing belong to the same repricing, and KEPCO KPS's 96 percent loss on a seven-year-old SMR stake is the same judgment rendered in Seoul (41), (48), (62).

The week's private capital went where the revenue certainty was, not where the technology was most novel (7), (8), (9), (27), (28), (29). Amazon's twenty-year agreement with Constellation, Oracle's offer to absorb part of an expensive Point Beach contract, and the Department of Energy's $4.2 billion loan to Vistra all direct money toward uprates, licence extensions and existing plants, which produce measurable megawatts within a defined regulatory envelope. That is a rational response to the one constraint the sector cannot argue away: the gap between the pace at which demand for firm clean power is growing and the pace at which new reactors can be licensed, financed and built. The Australian published a column arguing that all sides must think again on uranium, which is the question the market is currently answering in two directions at once (63). For this week, the commodity says scarcity and the equities say execution, and both are correct.


Sources

All 63 sources
  1. Reuters (via EnergyNow), "US Says it Reaches Nuclear Power Deal With Saudi Arabia" (September 30, 2026)
  2. Reuters, "US senators expect vote after midterms on Trump's nuclear power pact with Saudi Arabia" (October 2, 2026)
  3. Bloomberg (via roic.ai), "Iran Floats Nuclear Inspector Access for Sanctions Relief" (October 1, 2026)
  4. Mehr News Agency, "Russia dismisses US's call for Iran to abandon nuke program" (October 3, 2026)
  5. American Nuclear Society, "TVA receives construction permit for Clinch River" (September 29, 2026)
  6. World Nuclear News, "Second part of construction permit application submitted for Pioneer SMRs" (October 2, 2026)
  7. Reuters, "Constellation, Amazon sign 20-year power deal to support Maryland nuclear plant" (September 30, 2026)
  8. World Nuclear News, "Constellation, Amazon agree nuclear-focused power purchase deal" (October 1, 2026)
  9. CNBC, "U.S. to lend $4.2 billion to Vistra to boost nuclear power output, source says" (October 3, 2026)
  10. EIN Presswire, "Long-Term Uranium Price Remains at Historical High of $97.00 for Four Consecutive Months" (October 2, 2026)
  11. Uranium Speculator, "Morning Espresso - Oct 02, 2026" (October 2, 2026)
  12. ZeroHedge (via OilPrice.com), "Uranium Hits Record High While Nuclear Stocks Slide" (October 1, 2026)
  13. International Banker, "The Hormuz Closure Is Strengthening the Case for Nuclear Power Among Asian Energy Importers" (October 2, 2026)
  14. Firstpost, "Japan's nuclear power ambitions face turbulent geopolitical headwinds" (October 4, 2026)
  15. East Asia Forum, "Japan's nuclear options under a wavering US umbrella" (October 3, 2026)
  16. The Kyiv Independent, "Series of drone attacks disrupt power supply near Zaporizhzhia Nuclear Plant, IAEA says" (October 3, 2026)
  17. The New York Times (via Political Wire), "Superpowers Race to Put Nuclear Reactors on the Moon" (October 3, 2026)
  18. CBC News, "Premier Scott Moe goes big on nuclear with plans to explore 2 large nuclear reactors in northwest Sask." (September 29, 2026)
  19. 620 CKRM, "Rafferty Reservoir selected as site for further study for SMR development" (September 29, 2026)
  20. NPR, "A startup wants to build a massive nuclear-powered data center on public land in Utah" (September 30, 2026)
  21. TechRadar, "Utah could get a 9.6GW nuclear data center campus with Project Beehive" (October 3, 2026)
  22. Data Center Dynamics, "9.4GW SMR-powered data center campus proposed in Utah" (October 1, 2026)
  23. POWER Magazine, "TVA gets green light to build first BWRX-300 small modular reactor in the US" (October 1, 2026)
  24. Interesting Engineering, "680 MW twin nuclear reactor project advances as site work begins in US" (October 3, 2026)
  25. WCHS-TV, "West Virginia exits nuclear campus initiative over spent fuel handling concerns" (October 1, 2026)
  26. WV MetroNews, "After ambitious pursuit of nuclear hub, West Virginia splits" (September 30, 2026)
  27. Wisconsin Watch, "We Energies strikes deal to power Oracle data center with nuclear energy" (October 2, 2026)
  28. Milwaukee Journal Sentinel (via The Daily Reporter), "Oracle offers to buy nuclear power in Wisconsin" (October 2, 2026)
  29. Forbes, "Oracle Will Absorb $300 Million Nuclear Bill Paid By Wisconsin Taxpayers" (October 2, 2026)
  30. FOX 2, "Missouri releases 2026 energy plan focused on nuclear power" (October 1, 2026)
  31. NJBIZ, "New Jersey energy plans going nuclear under Sherrill task force" (October 2, 2026)
  32. Concord Monitor, "New England states show measured optimism about nuclear renaissance, and hesitation to be 'first of a kind'" (October 2, 2026)
  33. World Nuclear News, "Moves to bolster US nuclear workforce development" (October 2, 2026)
  34. Notes from Poland, "Poland updates nuclear strategy with delays to launch of first two plants" (October 3, 2026)
  35. World Nuclear News, "Polish entrepreneurs invest in SGE's BWRX-300 projects" (October 2, 2026)
  36. Bloomberg, "Billionaire Solowow Eyes 2028 IPO for Polish Nuclear Power Firm SGE" (October 1, 2026)
  37. World Nuclear News, "Hinkley Point B second AGR transferred for decommissioning" (October 2, 2026)
  38. Energy Live News, "UK to turn fusion research into industrial powerhouse" (October 2, 2026)
  39. HazardEx, "UK HSE publishes new guidance for fusion energy facilities" (October 1, 2026)
  40. BBC, "Greens back North East data centre pause and no Hartlepool nuclear" (October 2, 2026)
  41. Reuters, "Nuclear technology group Steady Energy falls in market debut" (October 2, 2026)
  42. World Nuclear News, "NPCIL signs MoU for Gujarat nuclear power projects" (October 2, 2026)
  43. BSS (Bangladesh Sangbad Sangstha), "Additional uranium for Rooppur's first unit reaches plant" (October 4, 2026)
  44. New Age BD, "Uranium consignment reaches RNPP in Pabna" (October 3, 2026)
  45. World Nuclear News, "First concrete poured for Bailong 2 nuclear power unit" (September 28, 2026)
  46. Newsbytes.ph, "DOST awaits further assessment of Camarines Norte uranium find" (October 2, 2026)
  47. South China Morning Post, "Philippines' uranium find a 'vital' boost for nuclear energy ambitions" (October 1, 2026)
  48. ChosunBiz, "Kepco KPS sells SMR stake at 96% loss, refocuses on maintenance tech" (October 2, 2026)
  49. Nuclear Engineering International, "Indonesia finalising SMR location" (October 1, 2026)
  50. The Straits Times, "Nuclear fusion can create economic opportunity for Singapore: Tan See Leng" (October 1, 2026)
  51. American Nuclear Society, "LLNL researchers characterize hydrogen-uranium corrosion" (October 2, 2026)
  52. Streetwise Reports, "Uranium Production Jumps 157% as Costs Fall & Second US Mine Ramps Up" (September 30, 2026)
  53. GlobeNewswire, "NANO Nuclear Energy Advances Vertical Integration Strategy" (October 1, 2026)
  54. Journal of Commerce, "Ports look to next-gen nuclear to power growing infrastructure" (October 2, 2026)
  55. ExecutiveGov, "DOE Allots Up to $400M for FY 2027 Office of Science Funding Call" (October 2, 2026)
  56. Interesting Engineering, "Chinese tokamak achieves hydrogen-boron fusion with 100 million reactions a second" (September 29, 2026)
  57. Global Times, "China's 'artificial sun' hits new milestone with research campus delivered for use, targets 2030 for first electricity output" (October 1, 2026)
  58. General Atomics, "California Governor Signs Fusion Energy Bill Into Law, Strengthening the State's Leadership in the Global Fusion Industry" (October 2, 2026)
  59. Neutron Bytes, "Calif Gov Newsom Signs Bills to Accelerate Fusion and Fission" (September 30, 2026)
  60. American Nuclear Society, "DOE funds ORNL and Kyoto Fusioneering test facility" (October 2, 2026)
  61. AOL (via The Motley Fool), "Uranium Prices Just Broke a 19-Year Record, but Nuclear Stocks Are Collapsing Anyway" (October 2, 2026)
  62. Stocktwits, "SMR Stock Sinks On Huge Revenue Miss, But Here's Why Retail Is Still Bullish" (October 3, 2026)
  63. The Australian, "'All sides must think again on uranium'" (October 4, 2026)

Nuclear Pulse is an independent weekly intelligence briefing. All information is sourced from publicly available industry publications. No investment advice is provided.

© 2026 Nuclear Pulse — Compiled by Tollaskígyó
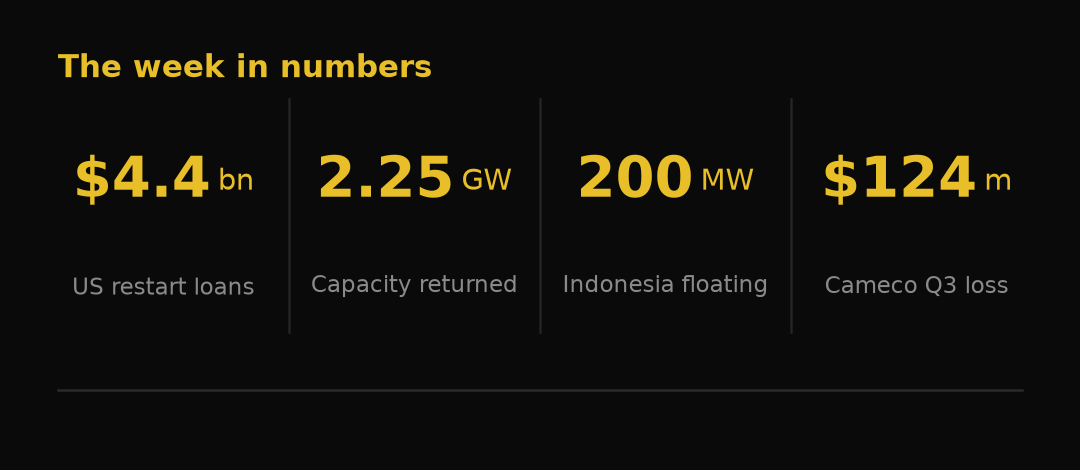
Sep 27Nuclear Pulse — September 27, 2026

Covering: September 20 – September 27, 2026
Published: September 27, 2026

Summary

Italy's Senate approved Prime Minister Giorgia Meloni's bill to return the country to nuclear power by 81 votes to 51 with seven abstentions on September 23, four decades after the 1987 referendum that closed its plants, and Nuward, Edison, Ansaldo and Maire used the same day to commit to a first Italian small modular reactor by 2035 (1), (2), (3). US intelligence told Congress that Saudi Arabia has not ruled out developing nuclear weapons, five days after Riyadh announced 110 million tonnes of uranium-bearing ore at Jabal Sayid, prompting Senators Ed Markey and Jeff Merkley to lead colleagues in demanding that the administration abandon the pending 123 agreement's enrichment provisions (4), (5), (6). The Westinghouse-Bechtel consortium and Polskie Elektrownie Jądrowe agreed the main commercial and legal terms of the engineering, procurement and construction contract for Poland's first nuclear power plant, three AP1000 units totalling 3,750 megawatts, with negotiations to conclude by year-end, while TerraPower moved to rebid the Natrium contract after Bechtel's withdrawal from the Kemmerer project (7), (8), (9). Kairos Power accepted up to $100 million from Samsung C&T for its Hermes 2 demonstration reactor in Oak Ridge while Google agreed to fund 96 megawatts of extended power uprates at Georgia Power's Vogtle and Hatch plants, tying data-centre demand directly to the output of reactors already running (10), (11), (12). Uranium spot traded at $89.50 per pound on September 25, flat against the previous week's $89.70 print and 8.48 percent above a year ago, the long-term indicator stood at $96.50 per pound, and Holtec paused fuel loading at Palisades after a fuel assembly handling mishap that the Nuclear Regulatory Commission is reviewing (13), (14), (15).

Geopolitical and Strategic Analysis

The week's most consequential disclosure came from the American intelligence community rather than from any reactor programme (4), (5). A US assessment delivered to Congress concluded that Saudi Arabia has not ruled out developing nuclear weapons, a judgment reported by The Washington Post and The New York Times on September 25 and carried across Israeli, Gulf and Indian outlets within a day. Read against the July civil nuclear cooperation agreement and the Joint Resolution of Disapproval filed by four Democratic representatives on September 16, the assessment narrows the space in which the administration can argue that an enrichment-capable Saudi programme serves American interests. The Senate letter led by Markey and Merkley pressed the same objection from the other chamber, arguing that a framework permitting enrichment on Saudi soil would make the United States a party to proliferation rather than a brake on it (6). The strategic problem is not the ore announcement, which describes raw material rather than recoverable uranium, but the sequencing. Riyadh now pairs a domestic resource narrative with an enrichment study and a weapons option it declines to foreclose, while Washington runs a war partly justified by Tehran's enrichment.

Iran answered on the same week (18), (19), (20), (21). President Masoud Pezeshkian told the United Nations General Assembly on September 23 that Iran seeks nuclear energy and not a bomb, that it will not accept limits on civilian enrichment, and that it will not bow to what he called the language of force, remarks delivered while the American delegation left the chamber. Within two days the position had softened at the edges: Pezeshkian told Fox News that Tehran is willing to dilute its 60 percent stockpile and submit to international inspections, and Haaretz reported a seven-day Iranian plan to reopen the Strait of Hormuz that nonetheless rules out nuclear concessions. Rafael Grossi said inspections could resume quickly if a political opening appears, which places the technical machinery on standby behind a political decision (18). A reported Russian document describing multi-year cooperation across Iranian finance, nuclear and aviation sectors, published by Fox News on September 20, adds a second-order problem: any monitoring arrangement in Iran now runs through a partner that is itself under sanctions (22).

The IAEA's seventieth General Conference closed in Vienna with the institutional layer settled (17). More than 3,600 participants registered, including representatives of 160 of the agency's 181 member states and 78 ministers, and the conference elected Angola, Brazil, Greece, Honduras, Kuwait, Malaysia, Mexico, New Zealand, Nigeria, Slovakia and Sweden to the 35-member Board of Governors for 2026 and 2027. The United Kingdom and the Cook Islands deposited legal instruments at the annual treaty event, with the UK ratifying the amendment to the Convention on Supplementary Compensation for Nuclear Damage. Separately, the agency signed a partnership agreement with the Inter-American Development Bank covering nuclear energy for development, its first such framework with a regional development bank (78). The substantive output of the conference, the sixth consecutive upward revision of capacity projections and the Uranium 2026 resource assessment, was reported last week; what this week adds is a governing board weighted toward countries entering or expanding nuclear programmes, and a multilateral financing channel opening alongside the bilateral one.

The export architecture moved on bilateral lines rather than through vendor contracts (25), (27), (28), (29). The US Trade and Development Agency signed an agreement worth around $2 million with Turkey's state nuclear enterprise TÜNAŞ for a year-long study of four American small modular reactor designs and five fourth-generation reactor designs, work that gives US vendors an early regulatory foothold in a market where Rosatom is already building Akkuyu (25), (26). Bangladesh and the United States signed a memorandum of understanding on strategic civil nuclear cooperation (27). In South-East Asia, an Energy for Growth Hub assessment ranked ASEAN members by nuclear readiness while DW reported that nuclear power is back on the region's energy agenda, with Vietnam, Indonesia, Malaysia and Thailand all registering positions (28), (29). Countervailing pressure came from France, where RFI reported legal action against EDF over its continuing nuclear ties with Russia (23), and from the Arctic, where Rosatom manufactured the second RITM-200C reactor for a floating plant serving a copper mining cluster in Chukotka (24). The pattern is that technical assistance, not hardware, is the current instrument of influence.

Regional Developments

North America

The Palisades restart absorbed North American attention this week for the worst reason (15), (16). Holtec confirmed that an incident involving a fuel assembly paused fuel loading at the Covert, Michigan plant, a process that began on August 30 when the reactor entered Mode 6 with a core of 204 assemblies combining new fuel and partially used fuel from earlier operating cycles. The Nuclear Regulatory Commission opened a review, the plant was connected to its switchyard, and the company delayed the restart schedule it had been targeting. Palisades matters beyond Michigan because it is the proof case for the wider restart thesis: a closed merchant reactor returned to service with federal loan support, intended to show that the fastest new capacity is capacity that already exists. A handling fault at the refuelling stage does not invalidate that thesis, but it hands the programme's critics a concrete event at the moment when Holtec's equity story was already under strain (72).

Google's agreement with Georgia Power moves in the opposite direction, converting demand into capacity at plants that are already licensed (12). The deal would fund extended power uprates at Plant Vogtle units 1 and 2 and Plant Hatch units 1 and 2, adding roughly 96 megawatts through targeted modifications to turbines, pumps, motors and cooling systems that allow the reactors to run at higher licensed thermal power and send more steam to the turbine generator. The structure is a subscription to a new Nuclear Uprate tariff under which Google receives the zero-emission credits attached to the uprated output, subject to Georgia Public Service Commission approval, and it shields non-participating customers from the incremental cost. Vogtle's uprate was already approved in the company's 2025 Integrated Resource Plan while Hatch's still needs approval. Google has now signed or supported long-term nuclear supply in Finland, Iowa and Georgia, and the Georgia filing is the first that pays for physical capacity additions rather than contracting for existing output.

The Department of Defense continued to build out its own nuclear programme (53), (54), (55). The Army named five installations for its nuclear power initiative, with Aberdeen Proving Ground in Maryland designated for a 390-megawatt molten salt reactor and Fort Drum in New York among the other sites. Applied Atomics, which has revived the mPower design, announced a headquarters and training centre in New Orleans. Federal civilian policy moved in parallel. The Nuclear Regulatory Commission accepted the Diablo Canyon safety report covering continued operation of the two California units (56), and the Senate Environment and Public Works Committee held a hearing on updating the Nuclear Waste Policy Act at which six states were identified as finalists for Department of Energy Nuclear Lifecycle Innovation Campuses, with members noting that ratepayers have paid more than $50 billion into the Nuclear Waste Fund without Congress appropriating commensurate disposal funding (57), (58). In New York, Democratic legislators objected to a $23.9 billion nuclear subsidy proposal on ratepayer grounds, a reminder that state-level nuclear finance remains contested even in jurisdictions that have lifted construction bans (59).

Canada's week belonged to Pickering (35), (36). Ontario Power Generation is taking units 5 to 8 out of service by the end of September, with refurbishment formally beginning in January 2027 subject to final regulatory approval, a programme carried at roughly CAD 26 billion that will replace 1,520 fuel channels and 48 boilers and add a 1.5-kilometre deep-water intake. The province announced CAD 1.7 billion of retube, feeder and boiler replacement work to a 50:50 joint venture of Aecon and Candu Energy, and CAD 1.3 billion of turbine generator replacement to a consortium of Aecon and Siemens Energy Canada. When complete the station will supply up to 2,200 megawatts and the four CANDU reactors will gain as much as 38 years of operating life, with the project counted as a CAD 41.6 billion contributor to Canadian GDP. Refurbishment at this scale is the least speculative form of new nuclear capacity, because the site, the licence and the grid connection already exist.

Europe

Italy's return is now legislative fact rather than political intent (1), (2), (3). The Senate passed Meloni's delegating bill by 81 votes to 51 with seven abstentions on September 23, following the Chamber of Deputies' June passage by 155 to 86 with eight abstentions, and it authorises the government to build a regulatory framework, a national sustainable nuclear programme and an independent safety authority. Environment and Energy Security Minister Gilberto Pichetto Fratin framed the vote around energy security and affordability rather than climate accounting. The industrial signal arrived on the same day: Nuward and its parent EDF, Edison, Ansaldo and Maire stated a common intention to deploy a first small modular reactor in Italy by 2035, and Nuward has separately said it aims to start construction on the first of a ten-unit European fleet in 2030 across five EU member states (30).

Poland's first plant crossed its commercial threshold (7), (8). The Westinghouse-Bechtel consortium and Polskie Elektrownie Jądrowe agreed the main terms of the EPC contract for three AP1000 units totalling 3,750 megawatts at Lubiatowo-Kopalino, with the remaining terms to be settled by year-end and first electricity to the Polish grid targeted for 2036. Bechtel took over site management in August as earthworks began, and the construction licence application went to Poland's National Atomic Energy Agency in March. The same contractor's withdrawal from TerraPower's Natrium project, confirmed this week after the company filed a Worker Adjustment and Retraining Notification covering around 200 positions effective on or about November 16, is the useful contrast (9). Bechtel said it expects to redeploy the affected staff to other nuclear work and will remain on site to complete the Sodium Test and Fill Facility, while TerraPower said construction at Kemmerer continues on schedule and that it intends to rebid the EPC scope.

Elsewhere in Europe the week produced a commissioning milestone and a supply-chain reordering. Slovakia's Mochovce 4 began generating power on September 21 (34). The 471-megawatt unit will be phased up through output steps of 5, 20, 35, 55, 75 and 90 percent with checks at each stage, entering the grid at 20 percent, and once at full output Slovakia's nuclear share will be equivalent to 77.5 percent of national electricity consumption, the highest proportion for any country. In the United Kingdom, GE Vernova Hitachi, SGE and Samsung C&T signed a memorandum of understanding to develop BWRX-300 market opportunities in Europe on the sidelines of the United Nations General Assembly (31), and SGE said it is confident of privately financing a 14-unit, 4.2-gigawatt BWRX-300 fleet across three UK sites under a contract-for-difference model, with its application in the deep-dive stage of the Advanced Nuclear Framework (32). Czech company Škoda JS was named sole supplier of control rod drive mechanisms for Rolls-Royce SMR (33), and the UK's STEP fusion programme received backing from KF (69). On the decommissioning side, EDF's Cyclife validated the dismantling strategy for the Chinon A2 heat exchangers, France's first UNGG reactor to be taken apart (79), and the 80-metre exhaust stack at the decommissioned Stade plant in Lower Saxony was demolished (80).

Asia

Taiwan moved closer to reversing its nuclear phase-out (37), (38). Bloomberg reported a policy shift as the government backed an early plan to restart nuclear power, and the restart review for an existing unit advanced. The shift follows the referendum campaign to abolish the nuclear-free homeland policy scheduled alongside November 28 local elections, and it lands in a system where the Legislative Yuan and the Executive Yuan have taken opposing positions on the question. What has changed is the framing: a decade ago the debate was whether nuclear power should exist in Taiwan at all, and the current debate is which units can be returned to service and on what timetable.

India's programme produced a strategy document and two fuel-loading milestones (39), (40), (41). The government set out a roadmap to reach 100 gigawatts of nuclear capacity by 2047 with an explicit push for indigenous small modular reactors, a target requiring roughly a quadrupling of installed capacity from present levels and a domestic supply chain that does not yet exist at the required scale. Fuel loading began at Rajasthan Atomic Power Project unit 8, and geotechnical investigation started for the next two units at the site, while fuel loading began at Kaiga unit 1 ahead of its return from refurbishment. EDF is simultaneously pressing its reactor technology on Indian decision-makers (41).

South-East Asia's readiness picture sharpened (27), (28), (29), (42), (43). Bangladesh and the United States signed a strategic civil nuclear cooperation memorandum, arriving while Rooppur unit 1 remains loaded but unsynchronised. In the Philippines, scientists reported a possible uranium resource in Camarines Norte while the fate of the long-mothballed Bataan plant remains undecided. The Energy for Growth Hub assessment placed ASEAN members on a readiness spectrum running from countries still building capability to those close to signing vendor agreements, with several upgrading their position since the March edition of its global advanced nuclear map.

Middle East and Africa

The Saudi and Iranian threads analysed above remain the region's dominant variables, and the assessments published this week carry a specific operational consequence: the three-month Congressional review window on the US-Saudi agreement now runs against an intelligence judgment that Riyadh has kept its weapons option open (4), (5), (6). The African uranium map changed hands materially (44), (45). Atomic Eagle, the Australian-listed company formed when GoviEx Uranium merged with Tombador Iron in November 2025, executed the Mining Convention for the Madaouela project with the Republic of Niger at a ceremony in Niamey, formalising the commercial resolution announced in August and triggering discontinuation of the ICSID arbitration GoviEx launched in December 2024 after Niger withdrew its mining rights following the 2023 coup. The convention provides legal, fiscal and regulatory stabilisation measures, establishes a framework for project financing and offtake arrangements, and carries an initial ten-year term with renewal provisions. Niger raised its stake in Madaouela Mining Company to 40 percent, with Atomic Eagle holding 60 percent through its subsidiary, and the project holds an estimated 116.5 million pounds of U3O8, of which 96.9 million pounds sit in the measured and indicated category. Atomic Eagle agreed to pay USD 5 million within 30 days and aims to report a JORC-compliant resource by the end of 2026. Madaouela's return to development, alongside the US Development Finance Corporation's conditional $414.2 million facility for Global Atomic's Dasa deposit agreed the previous week, means that both of Niger's principal uranium projects now rest on Western capital in a country that expelled Western forces two years ago. In South Africa, reporting on accidents at the Koeberg plant raised questions about the country's nuclear future (46).

Technology and Innovation

The Kairos Power term sheet with Samsung C&T is the week's most structurally significant commercial agreement (10), (11). Samsung C&T will contribute up to $100 million, comprising $70 million of equity and the remainder in in-kind engineering services, and joins Kairos's engineering, procurement and construction team for Hermes 2, the 50-megawatt fluoride salt-cooled high-temperature reactor under construction at Oak Ridge. Hermes 2 is the first generation IV reactor covered by a power purchase agreement with a US utility, struck with the Tennessee Valley Authority and Google in August 2025, and its output will count as the first 50 megawatts toward Google's roughly half-gigawatt commitment to Kairos. The commercial design envisions a 150-megawatt plant built from two 75-megawatt units fuelled with 19.75 percent HALEU, with the option of running on lower-enriched LEU+ if HALEU supply proves difficult. Bringing an engineering and construction firm of Samsung C&T's scale onto the team addresses the constraint that most often stalls first-of-a-kind reactors, which is not the physics but the ability to build the same plant repeatedly.

The fuel cycle produced two milestones that both point at enrichment above the historic five percent line (47), (48), (49). Framatome signed the first commercial contract to supply a reload of fuel enriched above 5 percent to an operating US reactor, with delivery in early 2028 and the customer's cycle length extended from 18 months to 24, manufactured at Richland, Washington after that plant's licence was amended to handle enrichment up to 10 percent. TRISO-X completed construction of the 214,000-square-foot TX-1 building in Oak Ridge and moved to interior buildout and equipment installation; the completed facility is designed to produce about 700,000 TRISO pebbles each year, equivalent to five tonnes of uranium and enough to fuel up to 11 Xe-100 reactors, with first output intended for Dow's UCC Seadrift site in Texas under a 40-year special nuclear material licence granted earlier this year.

On the research and infrastructure side, Idaho National Laboratory declared ready a mobile skid that crimps, chops and declads spent fuel rods for the Moran test bed, built over 20 months with funding from the National Nuclear Security Administration's Athena Initiative and first applied to Magnox fuel shipped from Greece (50). Argonne National Laboratory advanced a molten salt heat exchanger with machine-learning-based monitoring, aimed at real-time condition awareness in advanced reactor components (51). A study reported by Interesting Engineering found that up to 172 gigawatts of US small reactor capacity could be unlocked if projects bypassed grid interconnection and sited directly at industrial loads, a finding that recasts siting as a regulatory problem rather than a technological one (52).

Fusion Research

Fusion's policy architecture changed this week in a way that matters more than any plasma record (60), (61). Representatives Zoe Lofgren, Jay Obernolte, Don Beyer, Lori Trahan and Mike Gallagher introduced the bipartisan American Leadership in Fusion Act on September 24. The bill would create a Senate-confirmed Assistant Secretary of Fusion Energy, codify an Office of Fusion within the Department of Energy, and add $10 billion in direct appropriations through public-private partnerships. The Fusion Industry Association noted that private fusion investment reached a record $4.5 billion over the past year and that the sector's obstacle is no longer capital formation but the absence of a federal counterpart structured for commercialisation rather than research.

ITER's programme advanced on two fronts (62), (63), (64). The organisation reported progress on tritium breeding and processing, including the selection of four breeding blanket systems to be tested and a Tritium Plant Summit that brought the developing teams together, and confirmed that the seventh sector module of the vacuum vessel is scheduled for insertion into the pit later this year. US regulators exempted the ITER vacuum vessel from fission-based regulation, a decision that matters for the project's ability to move components without duplicating a licensing regime designed for fission reactors. The agency's own summary of the period said fusion is gathering momentum.

National and institutional programmes expanded in parallel (65), (66), (67), (68), (69). Universities in the United Kingdom and the United States formed a transatlantic alliance to build fusion research capacity and a workforce pipeline, drawing in York, Liverpool, Birmingham and Oxford among others. Proxima Fusion pushed for a European high-temperature superconducting tape supply chain, a component that determines both magnet performance and the pace at which compact devices can be built, as the Financial Times reported that US funding continues to dominate the sector. StandardX raised a £10 million seed round to build a rare isotope refinery serving medical isotope production and fusion fuel requirements. A 20-megawatt compact fusion system aimed at on-site power for data centres and industry was announced for US deployment, the same customer segment that fission microreactor developers are courting.

Market and Economic Intelligence

Uranium's spot market spent the week holding its recent range (13), (14). Trading Economics recorded $89.50 per pound U3O8 on September 25, up 0.06 percent on the day, down 1.21 percent over the month and 8.48 percent higher than a year earlier, which leaves spot flat to marginally lower against the $89.70 print of September 18 and within reach of the six-month high of $90.60 touched on August 26. The weekly trend is flat. The long-term contract indicator held at $96.50 per pound on Cameco's published series for August, at or above the 2007 nominal peak, so the term market continues to trade roughly $7 per pound above spot. That inversion remains the defining feature of the market: utilities are paying a premium for delivery years away while immediate supply clears at a discount, which is the price shape of expected future scarcity rather than present tightness. The supply-side reference point for that expectation is Kazakhstan, where Kazatomprom's TQZ sulphuric acid plant has slipped, limiting leaching capacity at the world's largest producer.

Project and corporate news followed the same logic (73), (74), (75), (76). Cameco became the selling agent for all output from Global Laser Enrichment's Paducah laser enrichment facility, extending the exclusive offtake agreed earlier in September into an agency role over the full production stream. NordX Metals reported outcrop samples grading up to 15.2 percent U3O8 at Flistjärn in Sweden and up to 6.95 percent at Norr Döttern, grades that are unusual outside the Athabasca Basin. Peninsula Energy lifted the mineral resource at its Lance project to 59 million pounds after drilling at Ross. Against those additions, New Mexico banned new uranium mine leases on state lands, removing acreage from development in the United States at the same time as federal policy pushes in the opposite direction.

Equity markets continued to sort nuclear exposure by execution risk rather than by narrative (70), (71), (72), (77). JPMorgan initiated coverage of NexGen Energy at overweight on the strength of its flagship project, and money managers were reported to be finding bargains after the sector's sell-off, while Holtec withdrew its $825 million initial public offering. Bloomberg's assessment that the AI-driven nuclear push is running into cost and regulatory hurdles, taken together with the 172-gigawatt bypass-grid study, describes the same constraint from the demand side: willingness to pay for nuclear power is established, and the binding limits are now construction cost, licensing duration and interconnection queue rather than signed offtake (52), (70).


Sources

All 80 sources
  1. World Nuclear News, "Italy's Senate approves a return to nuclear power" (September 24, 2026)
  2. Reuters, "Italian parliament backs Meloni's plan to restart nuclear power" (September 23, 2026)
  3. Financial Times, "Italy clears path for nuclear power revival" (September 23, 2026)
  4. The Washington Post, "Saudis have not ruled out developing nuclear weapons, U.S. intelligence assesses" (September 25, 2026)
  5. The New York Times, "Saudi Arabia Open to Possibly Developing Nuclear Weapons" (September 25, 2026)
  6. Office of Senator Jeff Merkley, "Senators Markey and Merkley Lead Colleagues to Demand Trump Administration Abandon Reckless Saudi Nuclear Deal" (September 25, 2026)
  7. World Nuclear News, "Polish plant contract negotiations move to next stage" (September 24, 2026)
  8. POWER Magazine, "Bechtel-Westinghouse Group, PEJ Agree on Terms for Poland's First Nuclear Power Plant" (September 23, 2026)
  9. World Nuclear News, "Bechtel steps away from TerraPower project" (September 22, 2026)
  10. TechCrunch, "Kairos Power gets up to $100M from Samsung group to build nuclear reactor for Google" (September 21, 2026)
  11. World Nuclear News, "Samsung C&T invests in Kairos Power" (September 22, 2026)
  12. World Nuclear News, "Google agreement to support Georgia plant uprates" (September 22, 2026)
  13. Trading Economics, "Uranium Price - Chart - Historical Data - News" (September 25, 2026)
  14. Cameco, "Uranium Price" spot and long-term contract indicator series (August 2026)
  15. American Nuclear Society, "Incident pauses Palisades fuel loading; plant connected to switchyard" (September 25, 2026)
  16. Detroit Free Press, "Nuclear regulators probe fuel assembly installation mishap at Palisades" (September 26, 2026)
  17. International Atomic Energy Agency, "Week in Review: IAEA 70th General Conference" (September 25, 2026)
  18. Bloomberg, "IAEA's Grossi Says Iran Nuclear Inspections Can Resume Fast" (September 23, 2026)
  19. The Times of Israel, "Pezeshkian claims Iran won't pursue nukes, won't accept limits on civilian enrichment" (September 23, 2026)
  20. Haaretz, "Iran Offers U.S. Seven-Day Plan to Reopen Hormuz, Rules Out Nuclear Concessions" (September 25, 2026)
  21. Rudaw, "Iranian president says will 'dilute' 60 percent uranium enrichment, denies nuclear bomb ambition" (September 25, 2026)
  22. Fox News, "EXCLUSIVE: Russian document reveals sweeping Iran plan spanning nuclear, finance and aviation" (September 20, 2026)
  23. RFI, "EDF faces legal action over France's continuing nuclear ties with Russia" (September 25, 2026)
  24. World Nuclear News, "Second reactor manufactured for floating nuclear plant" (September 24, 2026)
  25. World Nuclear News, "US-Turkey agreement to accelerate SMR deployment" (September 24, 2026)
  26. Daily Sabah, "Türkiye targets first small modular reactor for early 2030s" (September 23, 2026)
  27. The Hindu, "Bangladesh, U.S. sign MoU on strategic civil nuclear cooperation" (September 26, 2026)
  28. Energy for Growth Hub, "2026 Update: Who in ASEAN Is Ready for Nuclear Power?" (September 25, 2026)
  29. DW.com, "Nuclear power is back on Southeast Asia's energy agenda" (September 21, 2026)
  30. World Nuclear News, "Nuward targets 10 SMRs in five EU countries" (September 21, 2026)
  31. World Nuclear News, "GE Vernova, Hitachi, SGE and Samsung C&T sign BWRX-300s MoU" (September 23, 2026)
  32. World Nuclear News, "SGE confident of UK SMR fleet prospects" (September 23, 2026)
  33. World Nuclear News, "Škoda JS to supply control rod drives for Rolls-Royce SMR's reactors" (September 23, 2026)
  34. World Nuclear News, "Power start-up for Mochovce 4" (September 22, 2026)
  35. World Nuclear News, "Contracts announced as Pickering refurb approaches" (September 23, 2026)
  36. NucNet, "Canada Begins CAD 26 Billion Refurbishment Project At Pickering Nuclear Power Station" (September 22, 2026)
  37. Bloomberg, "Taiwan Backs Early Plan to Restart Nuclear Power in Policy Shift" (September 25, 2026)
  38. Taipei Times, "Nuclear plant restart review advances" (September 25, 2026)
  39. DD News, "Government unveils roadmap to achieve 100 GW nuclear power capacity by 2047, pushes indigenous small modular reactors" (September 27, 2026)
  40. World Nuclear News, "Indian plants celebrate fuel loading milestones" (September 21, 2026)
  41. The Indian Express, "France's EDF pushes for its nuclear reactor tech in India" (September 25, 2026)
  42. Business Mirror, "PHL scientists discover possible uranium resource in Camarines Norte" (September 26, 2026)
  43. The Seattle Times, "An unused and divisive Philippine nuclear plant awaits its fate" (September 26, 2026)
  44. World Nuclear News, "Agreement clears way for resumption of Niger uranium project" (September 25, 2026)
  45. Mining.com, "Niger increases stake in Madaouela uranium project to 40%, statement says" (September 24, 2026)
  46. Chemistry World, "Accidents at South Africa's nuclear power plant lead to questions over country's nuclear future" (September 23, 2026)
  47. World Nuclear News, "Milestone for X-Energy's TRISO-X fuel facility" (September 25, 2026)
  48. NucNet, "Triso-X Reaches Milestone In Advanced Nuclear Fuel Facility Construction" (September 25, 2026)
  49. World Nuclear News, "Framatome secures first contract for higher enriched fuel" (September 22, 2026)
  50. American Nuclear Society, "Fuel decladding skid ready to deploy at INL's Moran test bed" (September 24, 2026)
  51. American Nuclear Society, "Argonne develops real-time AI monitoring for an advanced nuclear reactor component" (September 21, 2026)
  52. Interesting Engineering, "172 GW of US small reactor capacity could be unlocked by bypassing electric grid: Study" (September 23, 2026)
  53. Association of the United States Army, "Army Announces 5 Posts for Nuclear Power Initiative" (September 23, 2026)
  54. Interesting Engineering, "390 MW molten salt nuclear reactor to power US Army's Maryland base" (September 21, 2026)
  55. The Center Square, "Applied Atomics brings revived mPower nuclear design to New Orleans" (September 24, 2026)
  56. San Luis Obispo Tribune, "U.S. nuclear agency OKs Diablo Canyon safety report. What to know" (September 25, 2026)
  57. The Center Square, "Senate considers establishing $50B nuclear energy campuses" (September 23, 2026)
  58. American Nuclear Society, "Senate committee reviews NLIC program, nuclear waste policy" (September 24, 2026)
  59. NEWS10 ABC, "Dems want Hochul to drop $23.9 billion nuclear subsidy plan" (September 26, 2026)
  60. Fusion Industry Association, "Congress Introduces Bipartisan American Leadership in Fusion Act" (September 24, 2026)
  61. Heatmap News, "House Science Leaders Introduce a $10 Billion Fusion Bill" (September 24, 2026)
  62. American Nuclear Society, "ITER breeding blanket and tritium plant plans advance" (September 25, 2026)
  63. American Nuclear Society, "ITER vacuum vessel exempted from fission-based regulation" (September 25, 2026)
  64. ITER, "Fusion is gathering momentum" (September 21, 2026)
  65. Financial Times, "European fusion start-up pushes for local supply chain as US dominates funding" (September 22, 2026)
  66. DPA Magazine, "Leading UK and US universities forge fusion energy alliance" (September 25, 2026)
  67. Pulse 2.0, "StandardX Raises £10 Million Seed Round To Develop Rare Isotopes For Cancer Treatment And Fusion Energy" (September 23, 2026)
  68. Interesting Engineering, "20 MW compact fusion system targets on-site power for data centers and industry" (September 21, 2026)
  69. Nuclear Engineering International, "KF backs UK's STEP programme" (September 25, 2026)
  70. Bloomberg, "AI's Nuclear Power Push Runs Into Cost and Regulatory Hurdles" (September 25, 2026)
  71. Investor's Business Daily, "Uranium Stocks Are Rallying. Why NXE Got Initiated At Overweight." (September 21, 2026)
  72. Renaissance Capital, "Nuclear plant equipment provider Holtec Nuclear withdraws $825 million IPO" (September 25, 2026)
  73. American Nuclear Society, "Cameco becomes selling agent for all Global Laser Enrichment output" (September 27, 2026)
  74. TMX Newsfile, "NordX Metals Finds High-Grade Uranium Mineralization in Outcrop Samples up to 15.2% U3O8 at Flistjärn, Sweden" (September 22, 2026)
  75. Kalkine Media, "Peninsula Energy Boosts Lance Project Mineral Resource to 59.0Mlbs U3O8" (September 25, 2026)
  76. Industrial Info Resources, "New Mexico Bans New Uranium Mine Leases on State Lands" (September 21, 2026)
  77. The Globe and Mail, "Money managers find bargains after sell-off in nuclear sector" (September 23, 2026)
  78. International Atomic Energy Agency, "IAEA and Inter-American Development Bank Sign Partnership Agreement on Nuclear Energy for Development" (September 25, 2026)
  79. World Nuclear News, "France prepares to start dismantling first UNGG reactor" (September 21, 2026)
  80. World Nuclear News, "Demolition of exhaust stack changes Stade skyline" (September 25, 2026)

Nuclear Pulse is an independent weekly intelligence briefing. All information is sourced from publicly available industry publications. No investment advice is provided.

© 2026 Nuclear Pulse — Compiled by Tollaskígyó
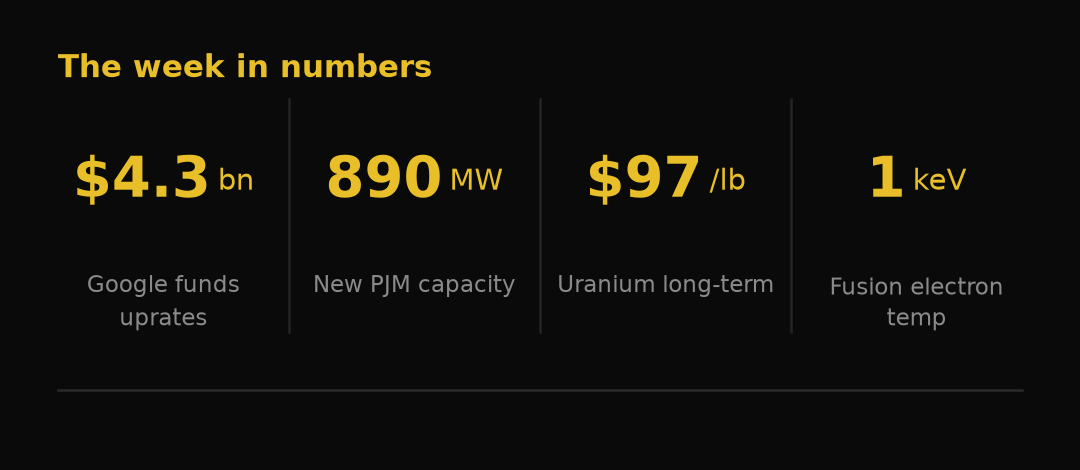
Sep 20Nuclear Pulse — September 20, 2026

Covering: September 13 – September 20, 2026
Published: September 20, 2026

Summary

A drone struck the cooling tower of unit 1 at Russia's Kursk NPP-2 on September 17, a strike on an operating reactor site that the IAEA confirmed left no fire and no change in operating mode, while Director General Rafael Grossi restated that all attacks on nuclear facilities are unacceptable (1), (2), (3). The IAEA's 70th General Conference in Vienna reset the sector's long-range horizon, with capacity projections raised for a sixth consecutive year to 1,284 gigawatts electric by 2060 and small modular reactors accounting for up to 284 gigawatts of that build, equivalent to roughly 950 to 1,140 units (4), (5), (6). Saudi Arabia's energy minister announced 110 million tonnes of uranium-bearing ore at the Jabal Sayid project in the Madinah region, days before Democratic lawmakers filed a Joint Resolution of Disapproval against the US-Saudi 123 agreement (7), (8), (9). EDF said it will build ten Nuward small modular reactors across the European Union by 2035 in a programme its executives described as requiring tens of billions of euros of investment, the largest single SMR fleet commitment announced by a European state-owned utility (10), (11). Uranium's long-term contract indicator held at $96 to $97 per pound, at or above its 2007 nominal peak, while spot traded near $89.70 per pound and the AI-linked equities that carried the sector's 2025 rally continued to deflate, with Holtec postponing its initial public offering and Bechtel walking away from TerraPower's Natrium project (12), (13), (14), (15).

Geopolitical and Strategic Analysis

The Kursk strike is the week's most consequential safety development, and its significance lies less in the damage caused than in the target class (1), (2), (3). Rosatom said the drone detonated on the cooling tower of unit 1 at Kursk NPP-2, causing minor damage and leaving the unit running at full capacity, with radiation levels unchanged. The IAEA confirmed it was informed that the unit was operating when struck, that its operating mode did not change, and that no fire broke out. Grossi's response was categorical rather than technical: all attacks on nuclear facilities are unacceptable irrespective of where they occur, and he repeated his call for maximum military restraint to prevent the risk of a nuclear accident. Read against the Zaporizhzhia campaign, where the agency has now brokered seven localized ceasefires to allow power-line repairs, the pattern is that nuclear sites on both sides of the Ukraine war have become recurring targets of opportunity rather than protected infrastructure (68), (69). The Zaporizhzhia sequence this month is instructive: the plant lost off-site power for eighteen days before an IAEA-brokered ceasefire allowed the 750 kilovolt Dniprovska line to be repaired, and Greenpeace published an assessment this week alleging that Russian forces are deliberately sabotaging supply lines to the site. The strategic read is that the war has produced a durable, low-level radiological risk that no single negotiated arrangement has removed, and that the agency's role has shifted from verification to active deconfliction.

The IAEA General Conference supplied the week's structural argument (4), (5), (6). Grossi's sixth consecutive upward revision projects 1,045 gigawatts electric by 2050 in the high case and 1,284 gigawatts by 2060, roughly 3.4 times the 377.1 gigawatts operating at the end of 2025, against a low case of 696 gigawatts. The composition matters more than the total: in the high case small modular reactors account for about 284 gigawatts of the 1,017 gigawatts of new capacity added through 2060, a 28 percent share, which at an average of 250 to 300 megawatts per unit implies between roughly 946 and 1,136 deployed SMRs, with about 60 percent of new North American capacity potentially SMR-sourced against roughly 40 percent in South-Eastern Asia and Latin America. OECD Secretary-General Mathias Cormann told the parallel Roadmaps to New Nuclear conference in Paris that almost 80 gigawatts of new nuclear capacity is under construction across fifteen countries, equal to a fifth of today's global capacity, and that thirty-eight countries now support tripling global nuclear capacity by 2050 (26). The gap between the projection and the pipeline is the whole story: the projection has been revised up six years running, while delivered capacity under construction remains a fifth of the operating fleet.

The non-proliferation layer moved in two directions at once. At the General Conference the IAEA adopted a resolution criticising North Korea's weapons programme, and Pyongyang rejected it within a day (18), (19). Kim Yo Jong called the agency's position biased and accused it of double standards, pointing to US and South Korean nuclear submarine cooperation, while the foreign ministry stated that North Korea's nuclear status is irreversible and enshrined in law, a maximal formulation issued in the same week as state media coverage of a three-day inspection tour by Kim Jong Un of munitions factories. On the Iranian file, Trump's address to the United Nations General Assembly on September 22 will centre on preventing Iran from obtaining a nuclear weapon, with a follow-on meeting scheduled with the six Gulf Cooperation Council states and visas granted to a reduced Iranian delegation including President Masoud Pezeshkian and Foreign Minister Abbas Araghchi (20), (21). A senior administration official said the expectation is that Tehran abandons its nuclear pursuit, and warned that entities doing business with Iran will keep facing consequences. The picture is a non-proliferation architecture contested simultaneously by a declared nuclear state that refuses recognition, an active war that has not produced a nuclear agreement, and a civil nuclear framework in the Gulf that Congress is now trying to stop.

The Saudi file is where those threads converge (7), (8), (9), (22), (23), (24), (25). Prince Abdulaziz bin Salman told the General Conference that geological studies at Jabal Sayid near Madinah identified 110 million tonnes of ore carrying high concentrations of heavy rare earth elements alongside promising uranium concentrations. The figure describes raw material, not recoverable uranium: the amount that can be produced depends on ore grade, geology and extraction economics, and the IAEA has cautioned that identified occurrences do not establish commercial resources. Saudi Arabia currently produces no uranium and has never had a domestic enrichment industry (24). Even so, the timing was deliberate. The announcement came less than two months after the July civil nuclear cooperation agreement with the United States, which created a framework for US companies to bid on Saudi nuclear projects and includes a joint study on the feasibility of an enrichment facility on Saudi soil, with an additional study that could open the door to enrichment up to twenty percent (8), (25). That is the provision that drew the Congressional response: Democratic Representatives Gregory Meeks, Brad Sherman, John Garamendi and Don Beyer introduced a Joint Resolution of Disapproval on September 16, and a bipartisan group including Republican Senators John Kennedy and Rand Paul wrote to the Secretary of State and the Energy Secretary demanding declassification of two side letters the administration has withheld (9). Kelsey Davenport of the Arms Control Association noted that enrichment to twenty percent represents the majority of the work needed to reach weapons-grade levels, the same threshold the United States has repeatedly objected to Iran crossing. Washington is now running an enrichment-tolerant civil framework with Riyadh while fighting a war partly justified by Tehran's enrichment, and the inconsistency is being tested in a three-month Congressional review window.

China's institutional offensive continued on the same calendar, and the Western industrial base sent the opposite signal (14), (15), (34), (88), (89). The China Atomic Energy Authority launched the Global Network for SMR Innovation at the General Conference, describing it as a non-profit, unincorporated and open cooperation mechanism complementing the IAEA, with a governing board, secretariat, specialised committees and working groups and a first general assembly scheduled before the end of the year (34). Holtec Nuclear Corporation postponed the initial public offering it filed in July, having sought up to $900 million by offering 50 million shares at $15 to $18, one day before the offering was expected to price, with chief executive Kris Singh attributing the decision to a market turn against the AI data-centre economy (14). The equity backdrop supports that reading: Constellation Energy has fallen from above $400 last autumn to the mid-$260s, and the VanEck Uranium and Nuclear ETF has dropped from above $160 in January to below $110 (88). Bechtel's separation from TerraPower's Natrium demonstration project in Kemmerer, Wyoming, is the harder industrial data point, because it is a construction disagreement rather than a sentiment shift: the contractor filed a WARN notice covering roughly 200 employees at its Reston headquarters, effective around November 16, after the two companies could not agree on how to proceed to the project's next phase (15), (89). Bechtel says it expects to redeploy most of those staff to other nuclear work, and TerraPower says construction at Kemmerer continues with no anticipated schedule change. Read alongside X-energy trading 36.7 percent below its April IPO price and Standard Nuclear down 20.6 percent from its July offer through midweek, the week's message is that capital markets have repriced nuclear-linked equities while the physical project pipeline has not materially changed (14).

Regional Developments

North America

The TerraPower separation dominates the North American picture, because Natrium is the flagship of the US advanced reactor programme and Bechtel is the contractor with more US nuclear construction experience than any other, including the Vogtle units (15), (89). TerraPower holds the commercial-scale advanced reactor construction permit the NRC authorised on March 4, and the company says it is managing the transition to protect the overall schedule with first power still targeted for 2030 to 2031. What has changed is the execution structure: a project whose cost was estimated at approximately $4 billion with Department of Energy cost-share covering roughly half now needs a new construction partner or an in-house capacity build, and the November 16 layoff date sets a hard deadline for that decision. The week's other project news was procedural but substantive. Holtec's Palisades SMR subsidiary received an NRC exemption authorising installation of permanent support-of-excavation and cutoff-wall systems for Pioneer units 1 and 2, allowing diaphragm walls, soldier-pile soil-mix walls and perimeter cutoff walls to go in ahead of the limited work authorisation, with the regulator's environmental assessment finding no significant impact (46). Blue Energy submitted the first part of its construction permit application for its Port of Victoria, Texas site, requesting limited construction activities including deep foundation and shaft works for the first SMR, and asking the NRC to approve its build-order inversion in which the natural gas portion and balance-of-plant are constructed first and subsequently shared with the nuclear reactors (45). The company frames reactors as less than ten percent of a nuclear plant's cost, with the balance sitting in construction and regulatory work for the rest of the facility.

On the fuel and licensing side, the Department of Agriculture opened a nuclear power funding opportunity for rural electric cooperatives, extending federal nuclear finance to a borrower class that has not historically been in the programme (54). The Navy's first shore-based advanced micromodular reactor moved toward construction at Naval Weapons Station Crane, a commercially owned and operated unit that will also be Indiana's first power-producing reactor (52), (53). Pennsylvania's Department of Environmental Protection issued the Section 401 water quality certification for the restart of the Crane Clean Energy Center at Three Mile Island, covering withdrawals of up to 73.2 million gallons per day from the Susquehanna River against a consumptive use of up to 21 million gallons per day, with discharge temperatures capped at 110 degrees Fahrenheit (55). Valar Atomics secured a land agreement for its Carbon County project, and Idaho State University advanced a second research reactor under its energy future programme (57), (58). A Senate hearing examined nuclear fuel cycle and waste policy (56). In Canada, Pickering's unit 1 came offline for refurbishment work that will see crews remove all 1,520 pressure tubes from the 2,064-megawatt station outside Toronto, and New Brunswick's Point Lepreau plant was reported to be off-line for weeks (70), (71), (72).

Europe

EDF's SMR announcement is the largest European commercial commitment of the week and the most specific fleet target yet published by a state-owned utility (10), (11). Senior Vice President Vakisasai Ramany said at an event hosted by EDF's Edison unit, with Italian supply-chain companies present, that the group plans to build ten Nuward small modular reactors in the European Union by 2035, using technology developed by its Nuward subsidiary, with each unit producing about 400 megawatts of power and 115 megawatts of heat. EDF executives put the programme at tens of billions of euros of investment and explicitly framed it as a contribution to reducing the bloc's dependence on imported fossil fuels. The commercial logic is the district-heating and industrial-heat market rather than grid baseload, the same customer segment the European Investment Bank backed when it agreed to invest up to 40 million euros in Finland's Steady Energy (59). That loan is the EIB's first investment in small modular reactor technology after a history of avoiding new nuclear projects in favour of safety work, and it is structured as a senior unsecured convertible loan covering research, development, testing and licensing through 2028, against Steady Energy's fifteen signed reactor agreements in Finland and a target of starting construction on the first district-heating plant in 2029.

The United Kingdom moved on three fronts (38), (60), (61). The Department for Energy Security and Net Zero directed regulators to begin the Generic Design Assessment for X-energy's Xe-100 high-temperature gas-cooled reactor. The Office for Nuclear Regulation and the Environment Agency published the changes they have already made or intend to make to speed licensing for new nuclear technologies and construction, responding to the Nuclear Regulatory Taskforce's November recommendation of a "radical reset" and its 47 recommendations, with all reforms targeted for completion by the end of next year. And a set of collaboration agreements between US and UK partners was announced to accelerate commercial fusion deployment. Elsewhere in Europe, Slovenia's JEK2 project received a feasibility study proposing a natural draft cooling tower of 193 to 198 metres as the preferred option, and Russia's State Environmental Expertise issued a positive verdict on the licence justification materials for two new units at the Smolensk plant, the only substantive Russian new-build approval of the week (62), (64). Chernobyl's Industrial Complex for Solid Radioactive Waste Management shipped its first seven packages of processed low- and intermediate-level waste (65). Switzerland moved closer to a referendum on new nuclear construction after the alliance Nein zu neuen AKW collected more than 125,000 signatures, well above the 50,000 threshold, against Parliament's counterproposal to the "Stop the Blackout" initiative, with submission to the Federal Chancellery planned for October 6 (63). Armenia's government discussed extending the Metsamor plant and selecting a new reactor with the IAEA, and Prime Minister Nikol Pashinyan did not rule out Russia building the replacement unit (66), (67).

Asia

China's reactor pipeline delivered again, with unit 3 at the Changjiang plant in Hainan entering commercial operation as the first of two Hualong One reactors built under Phase II of the site (31). First concrete for unit 3's nuclear island was poured in March 2021, Phase II represents a total estimated investment of 40 billion yuan or about $5.9 billion with China Huaneng holding 51 percent, and both units are scheduled for full operation in early 2027. Once complete, Phase II is expected to generate 18 billion kilowatt-hours annually and displace more than 6.32 million tonnes of standard coal. The site also hosts the demonstration ACP100 small modular reactor, or Linglong One, which is in pre-commissioning tests. Work began on the second phase of the Jinqimen plant in Zhejiang, which will eventually hold six Hualong One units, and containment integrity tests were completed at unit 5 of the Lufeng plant in Guangdong (32), (33).

Japan produced the week's clearest institutional failure (27), (28), (29), (30). Chubu Electric Power said it will withdraw its regulatory review applications for units 3 and 4 at the Hamaoka plant in Shizuoka Prefecture after an independent committee found that workers felt under pressure from senior management to manipulate earthquake data submitted to the Nuclear Regulation Authority. The committee concluded that the data falsification began around 2012 at the latest, and that whistleblowers who raised concerns in 2019 and 2021 had their concerns dismissed by senior management. The utility described serious doubts about the reliability of its application documents and said it would withdraw rather than maintain the existing applications. President and CEO Kingo Hayashi and Chairman Satoru Katsuno will resign as of September 30, with director Minoru Yasui succeeding Hayashi from October 1. Hamaoka units 3 and 4 were among seventeen reactors in various stages of restart review, and the withdrawal removes two units from that queue during a period when the country's Seventh Basic Energy Plan calls for maximum use of nuclear power. Kansai Electric separately shut the Mihama reactor manually in central Japan. The Japan Times framed the week as a setback for the country's nuclear revival after scandals and accidents, which is the accurate description of what a falsified seismic basis does to a restart programme.

Taiwan's referendum machinery moved forward, with the Central Election Commission announcing five televised forums or debates on the referendum to abolish the "nuclear-free homeland" policy for November 12, 14, 16, 18 and 20, the Legislative Yuan representing the supporting side and the Executive Yuan the opposing side, and both sides required to submit representatives by October 15 (76). The referendum, put forward by the Kuomintang and supported by the Taiwan People's Party, will be held alongside nine-in-one local elections on November 28, and is Taiwan's fourth nuclear referendum since 2018 (76). In the Philippines, the unused and politically divisive Bataan nuclear plant remains without a decision on its fate, a reminder that the region's nuclear revival carries a legacy-asset problem alongside its new-build ambitions (95).

Bangladesh's entry into the operating-nuclear category was complicated by the details (77), (78). The country was described as entering the global nuclear energy community with fuel loaded in Rooppur unit 1, and Science and Technology Minister Faqir Mahbub Anam met Grossi in Vienna to request IAEA cooperation in expediting power supply to the national grid. The transmission system has been integrated with the National Load Dispatch Center's SCADA and energy management system under a Bangladesh Atomic Energy Commission and GE Vernova agreement covering eight transmission lines for units 1 and 2. The underlying commissioning issue is that two of three valve systems failed to operate as expected, preventing the move to trial generation anticipated for late September, with more than 2,000 pre-fuel-loading tests already completed successfully (78). India's Press Information Bureau published a "new chapter" framing of the country's nuclear journey, while India Today noted a sanctions asymmetry: Washington is cracking down on Russian oil buyers but continuing to permit its own uranium imports from Moscow (85), (86). Vietnam, Indonesia, Malaysia, Thailand, Oman and Kuwait all registered nuclear positions during the General Conference week, with the US Trade and Development Agency signing a feasibility study agreement with Thailand's Electricity Generating Authority for about 600 megawatts of SMR capacity across GE-Hitachi, Holtec, Kairos Power, NuScale, TerraPower, Westinghouse and X-energy designs, and ANTARA reporting that the IAEA views Indonesia as accelerating its nuclear development (79), (80), (81), (82), (83), (84).

Middle East and Africa

The Saudi announcements are analysed above; the regional consequence is that the kingdom now has a domestic resource narrative to pair with its enrichment ambitions (7), (22), (23), (24), (25). Prince Abdulaziz argued that the programme is not developed in isolation from the international community or through secret facilities, a construction aimed directly at Iran, and said the kingdom is examining ways to recover uranium associated with its phosphate fertiliser industry in addition to continuing sedimentary cover surveys for conventional uranium. The US Energy Secretary said in Vienna that there are no plans for uranium enrichment in Saudi Arabia, a statement that sits awkwardly beside the enrichment feasibility study written into the agreement text. Grossi has said Saudi Arabia will not sign the Additional Protocol but will accept oversight powers over enrichment, conversion and reprocessing that closely mirror it (24). Israel's Ynetnews published an analysis asking whether nuclear power could turn the country into a global AI hub, a framing that would have been politically untenable eighteen months ago (96).

Iran remains the region's dominant variable (20), (21). Trump's General Assembly address and the Gulf Cooperation Council meeting that follows it constitute the administration's first structured consultation with Gulf states since the war began, and the stated position is that Iran must abandon its nuclear pursuit while sanctions pressure on entities doing business with Tehran continues. Ynetnews reported that Iranian forces have brought down at least two US MQ-1 drones in recent days, that Trump has told Axios a "big decision" on resuming major strikes is approaching, and that he has suggested the war could conclude after the November midterm elections if no agreement is reached (21). The Security Council's mandate for the Iran sanctions-monitoring panel expires on September 26 during the General Assembly, with Russia and China opposing the oversight mechanism (20). In Africa, the US Development Finance Corporation approved up to $414.2 million in debt financing for Global Atomic's Dasa uranium project in Niger, roughly 40 percent above the $295 million proposed in 2024, marking a US commercial return to a country that expelled US forces two years ago (74), (75). Dasa is described as Africa's highest-grade uranium deposit, with a 2024 feasibility study projecting 68.1 million pounds of U3O8 over 23 years at 1,000 tonnes per day throughput, a post-tax net present value of $917 million at an eight percent discount rate and a 57 percent internal rate of return at a base case of $75 per pound (75). The financing remains conditional on identifying a viable export route from landlocked Niger, extending the mining convention and permit on acceptable terms, securing government assurances on loan repayment and completing definitive agreements. South Africa's nuclear programme and Egypt's El Dabaa construction continued on their existing trajectories (73).

Technology and Innovation

Westinghouse's eVinci milestone is the most technically specific achievement of the week (42). Working with Los Alamos National Laboratory and the Nevada National Security Site at the National Criticality Experiments Research Center, Westinghouse completed zero-power high-temperature criticality testing with the microreactor reaching criticality at 663 degrees Celsius, and made a subcritical reactivity measurement at a peak core temperature of 1,011 degrees Celsius, a record high temperature for a reactivity measurement at that facility. The eVinci is a heat pipe-cooled design producing up to 5 megawatts electric from a 15 megawatt thermal core, fuelled with TRISO and designed to run eight or more full-power years before refuelling, with a factory-built reactor shippable in a container. The engineering significance is that the test produced temperature-dependent reactivity data at conditions approaching operating temperature, which is what separates an analytical model from a validated one for a heat-pipe core.

The fuel cycle produced the week's most commercially consequential agreements (43), (44), (47). Centrus Energy and Antares signed a definitive multi-year high-assay low-enriched uranium supply contract, with pre-payments supporting Centrus's expansion at its American Centrifuge Plant in Piketon, Ohio, and deliveries to begin by the end of the decade to support Antares' modular transportable reactors, including space and national security missions (43). Antares is developing TRISO-fuelled reactors, its Antares 0 achieved criticality in June as the first reactor under the Department of Energy's Reactor Pilot Program to reach that milestone by the July 4 deadline, and it has been selected for Army deployment at Fort Bragg, Air Force deployment at Joint Base San Antonio and a Space Force strategic breakthrough award (43). Separately, Cameco agreed to buy all future production from Global Laser Enrichment's planned Paducah Laser Enrichment Facility in Kentucky under an exclusive offtake agreement, guaranteeing GLE pricing equivalent to Cameco's average realised annual price net of selling costs across its long-term contracting portfolio (44). GLE is 51 percent owned by Silex Systems and 49 percent by Cameco, reached Technology Readiness Level 6 last year after a large-scale enrichment demonstration at its Wilmington test loop, and expects a licence in hand in early 2027. GLE intends to re-enrich high-assay depleted uranium tails at Paducah under an agreement with the Department of Energy, expecting to produce about 70,000 tonnes of new fresh feed from the more than 200,000 tonnes of tails on site. Reuters also reported that the United States is seeking a faster expansion of uranium enrichment capacity to avert supply shortages, the policy frame around the Urenco USA programme to add 2.1 million separative work units at Eunice, New Mexico and grow installed capacity above 7 million SWU over the next decade (47).

Two unconventional supply ideas surfaced (48), (49). TechCrunch reported that clean technology startup Fluxnium has developed an approach to recover uranium from seawater, with parallel coverage citing roughly four billion tonnes of ocean uranium and a theoretical resource base measured in tens of thousands of years of fuel (48), (49). The claims are early-stage and the economics unresolved, since seawater uranium concentrations are in the parts-per-billion range and the binding materials must survive repeated marine cycling, but the underlying observation is sound: the ocean contains a uranium inventory roughly a thousand times larger than terrestrial reserves. On the legacy-technology side, the American Nuclear Society reported the arrival in Texas of FLiBe salt from the Molten Salt Reactor Experiment for reuse after decades in storage, and the restart of Hanford's Tank Side Cesium Removal system after extended downtime (50), (51). Both are maintenance-grade events, but FLiBe transfer preserves a material that no longer exists in commercial quantity, and TSCR restart restores a treatment path for Hanford's tank waste inventory.

Fusion Research

China's HL-4 (Huanliu-4) design was unveiled at the Fusion Energy Conference and Fusion Week in Shanghai as the world's first high-temperature superconducting high-field steady-state burning experimental platform, and the specifications are the story (35), (37). The device is being built in Shanghai around 25-tesla high-temperature superconducting magnets, with steady-state operation as its core objective, a target minimum fusion energy gain of Q = 5, and an eventual power output of 100 to 200 megawatts electric. The argument for HTS is that it removes the overheating limits of copper coils and shrinks both the machine footprint and the iteration cycle, which converts the tokamak from a pulsed physics experiment into a continuous power-engineering problem. Commissioning is targeted for 2027 for the initial Shanghai facility, with the first 25-tesla HTS high-field magnet development and testing line scheduled for completion in 2028 and prototype magnets by 2030. At the IAEA General Conference, Chinese delegates reported that HL-3 achieved dual hundred-million-degree operation in 2025, with ion temperatures of 120 million degrees Celsius and electron temperatures of 160 million degrees Celsius, and that deuterium-tritium burning plasma physics experiments are planned for 2027, with the Shanghai Fusion Science Research Centre site acquisition of 147,160 square metres complete and construction scheduled for completion in 2030 (37). A separate groundbreaking took place for ENN Group's ENN Fusion Spherical Ring Hydrogen-Boron Plasma Platform, or Helong-2, at its Langfang research centre in Hebei, which pursues the aneutronic proton-boron pathway (36).

Outside China, the week's fusion news was institutional and financial (38), (39), (40). US and UK partners announced a set of collaboration agreements aimed at accelerating commercial deployment, and Euronews reported that the world's first laser fusion power station is under construction in Germany (38), (39). The Financial Times published a long-form assessment of fusion's "moment of truth", and India's programme received profile treatment examining how it compares to the world's larger fusion efforts (40), (41). The pattern across all of it is that fusion has moved from a physics question to a supply-chain and licensing question: the Proxima Fusion high-temperature superconducting tape facility in Lower Saxony and China's 25-tesla magnet line are both attempts to industrialise an input that previously existed only at laboratory scale, and both are scheduled against demonstrator timelines rather than research timelines (35).

Market and Economic Intelligence

Uranium's spot price held in the high eighties through the week, closing near $89.70 per pound U3O8 on September 17 and $89.73 on September 18, flat day over day, after TradeTech's spot indicator touched $90 per pound during the week of September 15, only the second time that level has been reached since February 2026, with year-to-date gains of about 9.8 percent (12), (13). The weekly trend is effectively flat to marginally higher, and the long-term contract indicator moved to $97 per pound, at or above the 2007 nominal peak, while UxC's equivalent printed $96 at the start of September, so the term market continues to trade above spot for the first sustained period in this cycle (12), (13), (90). That inversion is the single most important datum in the uranium market: utilities are paying a premium of roughly six to seven dollars per pound for delivery years out while the immediate spot market idles, which is the shape of a market pricing future production scarcity rather than present inventory tightness. Benchmark Mineral Intelligence described the market as entering a structural deficit, and Mining.com's chart set showed miners racing to catch nuclear demand (90), (91), (92). The 2026 edition of the Red Book, published jointly by the OECD Nuclear Energy Agency and the IAEA, found that identified resources recoverable at costs below $260 per kilogram of uranium, or $100 per pound of U3O8, now exceed 8.1 million tonnes of uranium, up 2.1 percent on the 2025 edition, and that global production increased roughly 20 percent in 2023 and 2024 compared with the preceding two years, with 2024's 61,924 tonnes the highest since 2016 (16). The counterpoint came from Energy Intelligence, which reported that the Red Book also reveals flatlined uranium exploration spending, meaning the resource base is being expanded primarily by reclassification and re-estimation rather than by new discovery (17).

Project finance followed the price signal (59), (74), (75). The DFC's conditional $414.2 million facility for Global Atomic's Dasa project is the largest single US government-backed uranium financing of the year and raises the question of what the conditions will cost: the loan requires an export route from a landlocked country with active jihadist insurgency, an extended mining convention on terms Niger's government finds acceptable, sovereign assurances on repayment and definitive agreements with the DFC (74), (75). Cameco's exclusive Paducah offtake gives Global Laser Enrichment a guaranteed home for natural uranium hexafluoride and enriched products and clears a commercial pillar ahead of a final investment decision, and the European Investment Bank's convertible loan to Steady Energy opens the first SMR line item in an institution that until recently confined itself to nuclear safety work (44), (59). On the demand side, the Energy Information Administration's September Short-Term Energy Outlook holds nuclear at 18 percent of US generation through 2027 despite record power use (12).

The equity market told a different story (14), (87), (93), (94). Holtec's postponed offering is the clearest signal that capital is no longer pricing nuclear project announcements as risk-free AI exposure, and the reason cited was market sentiment against data centres (14), (88). Korean equities split along the same fault line, with KEPCO E&C jumping 39 percent while KEPCO fell 6 percent, and a US House data centre power bill lifted nuclear stocks midweek before the Holtec news (93), (94). The underlying demand story has not weakened: Crusoe and Aalo Atomics plan to run the first SMR-powered modular AI data centre next summer as a proof of concept, with later deployment of 50-megawatt Aalo Pods at Crusoe sites targeted for commercialisation by the end of 2029, and Aalo frames the opportunity as mass-producing reactors designed specifically for data centres rather than building bespoke gigawatt-scale plants (87). Heatmap News published an argument that nuclear is cheaper than commonly assessed, which is the necessary counterpart to the equity repricing if the term price is to be validated by actual construction volume (97).


Sources

All 97 sources
  1. Reuters, "Drone hit cooling tower on Thursday at Russian Kursk nuclear plant, IAEA says" (September 18, 2026)
  2. The Hindu BusinessLine, "IAEA condemns attacks on nuclear facilities after drone hits Kursk Nuclear Plant cooling tower" (September 19, 2026)
  3. TASS, "Ukraine drone incident fails to disrupt operations at Kursk NPP-2 Unit 1" (September 19, 2026)
  4. International Atomic Energy Agency, "IAEA Projects Global Nuclear Power Capacity Could Triple by 2060, Continuing Rising Trend" (September 14, 2026)
  5. World Nuclear News, "IAEA's projections suggest there could be 1,000 SMRs by 2060" (September 14, 2026)
  6. Interesting Engineering, "Global nuclear power capacity to reach 1,284 GWe by 2060, says IAEA" (September 15, 2026)
  7. Tribune, "Saudi Arabia discovers 110m tonnes of uranium bearing ore in Madinah" (September 14, 2026)
  8. CNBC-TV18, "Saudi Arabia discovers 110 million tonnes of uranium-bearing ore in Madinah region" (September 15, 2026)
  9. ABC News, "Democrats propose bill to strike down controversial Saudi nuclear deal" (September 17, 2026)
  10. Reuters, "France's EDF plans 10 small nuclear plants in Europe by 2035" (September 18, 2026)
  11. Euronext, "France's EDF plans 10 small nuclear plants in Europe by 2035" (September 18, 2026)
  12. Uranium Unleashed, "Uranium Long-Term Contract Price Breaks 2007 Peak as Term Hits $97/lb" (September 19, 2026)
  13. NetNewsLedger, "September 18 2026 Mining Roundup: Uranium Financing, Critical-Mineral Strategy and Marathon Funding Lead the News" (September 18, 2026)
  14. Reuters, "Holtec Nuclear Suspends Planned US IPO" (September 16, 2026)
  15. Construction Dive, "Bechtel splits with Bill Gates-backed nuclear project, files layoff notice" (September 17, 2026)
  16. International Atomic Energy Agency, "Adequate uranium resources available, but sustained investment essential to support global nuclear capacity growth" (September 14, 2026)
  17. Energy Intelligence, "Red Book Reveals Flatlined Uranium Exploration Spending" (September 18, 2026)
  18. Reuters, "North Korea says nuclear status 'irreversible' after UN atomic agency rebuke" (September 18, 2026)
  19. Al Jazeera, "North Korea dismisses UN nuclear watchdog resolution" (September 19, 2026)
  20. Reuters, "As Iran war grinds on, Trump to face skeptical world leaders at UN" (September 18, 2026)
  21. Ynetnews, "Iran in, Abbas out: Trump threatens new strikes as US grants Tehran leaders UN visas" (September 18, 2026)
  22. The National, "Saudi Arabia discovers 110 million tonnes of uranium-concentrated ore in Madinah region" (September 14, 2026)
  23. Business Upturn, "Saudi Arabia identifies 110 million tonnes of uranium-bearing ore in Madinah region" (September 15, 2026)
  24. NaturalNews, "Saudi Arabia Reports Discovery of 110 Million Tonnes of Uranium-Bearing Ore in Medina Region" (September 18, 2026)
  25. PBS, "U.S.-Saudi nuclear power deal faces pushback over potential weapons risks" (September 18, 2026)
  26. World Nuclear News, "Industry groups call for governments commitment for nuclear growth" (September 18, 2026)
  27. World Nuclear News, "Chubu withdraws restart applications for Hamaoka units" (September 14, 2026)
  28. NucNet, "Chubu President And Chairman To Resign Over Hamaoka Nuclear Plant Data Falsification" (September 18, 2026)
  29. The Japan Times, "Japan's nuclear revival hits setbacks after scandals and accidents" (September 18, 2026)
  30. Kyodo News, "Kansai Electric manually shuts Mihama nuclear reactor in central Japan" (September 17, 2026)
  31. World Nuclear News, "Third unit at Changjiang site commissioned" (September 17, 2026)
  32. World Nuclear News, "Groundwork begins for demonstration Hualong One 2.0 units" (September 14, 2026)
  33. World Nuclear News, "Containment tests completed at Lufeng unit 5" (September 18, 2026)
  34. World Nuclear News, "China launches Global Network for SMR Innovation" (September 15, 2026)
  35. Nuclear Engineering International, "China unveils HL-4 fusion tokamak" (September 16, 2026)
  36. World Nuclear News, "China begins building hydrogen-boron fusion device" (September 16, 2026)
  37. World Nuclear News, "China sets out fusion progress, collaboration opportunities" (September 18, 2026)
  38. World Nuclear News, "UK, USA enhance cooperation on fusion energy" (September 15, 2026)
  39. Euronews, "The world's first laser fusion power station is being built in Germany" (September 18, 2026)
  40. Financial Times, "Nuclear fusion's moment of truth" (September 16, 2026)
  41. Firstpost, "Inside India's artificial sun mission: How it compares to the world's fusion giants" (September 15, 2026)
  42. World Nuclear News, "eVinci sets temperature record during zero-power criticality tests" (September 15, 2026)
  43. World Nuclear News, "Antares, Centrus sign multi-year HALEU contract" (September 18, 2026)
  44. World Nuclear News, "Cameco in offtake agreement for US laser enrichment plant" (September 16, 2026)
  45. World Nuclear News, "Blue Energy submits first construction application to NRC" (September 16, 2026)
  46. World Nuclear News, "Holtec SMR project gets regulatory nod for early site work" (September 16, 2026)
  47. Reuters, "US seeks faster uranium enrichment expansion to avert supply shortages" (September 18, 2026)
  48. TechCrunch, "Clean tech startup Fluxnium found a way to tap 50,000 years' worth of nuclear fuel" (September 16, 2026)
  49. Interesting Engineering, "US firm eyes 4 billion tons of ocean uranium for 50,000 years of fuel" (September 17, 2026)
  50. American Nuclear Society, "MSRE FLiBe arrives in Texas for reuse after decades in storage" (September 18, 2026)
  51. American Nuclear Society, "Hanford's TSCR system restarted after extended downtime" (September 18, 2026)
  52. World Nuclear News, "Indiana to get its first power-producing nuclear reactor" (September 14, 2026)
  53. Nature World News, "Navy Plans Indiana's First Power-Producing Nuclear Reactor, a Microreactor at NWS Crane" (September 18, 2026)
  54. American Nuclear Society, "USDA opens nuclear power funding opportunity for rural electric cooperatives" (September 18, 2026)
  55. PA Environment Digest, "DEP Issues Section 401 Water Quality Certification For Restart Of Constellation Energy Three Mile Island Data Center Nuclear Power Plant" (September 19, 2026)
  56. Legis1, "Senate Hearing Examines Nuclear Fuel Cycle and Waste Policy" (September 17, 2026)
  57. ETV News, "Valar Atomics secures land agreement for Carbon County project" (September 18, 2026)
  58. East Idaho News, "ISU powering Idaho's energy future with second nuclear reactor" (September 17, 2026)
  59. World Nuclear News, "First SMR funding agreed by European Investment Bank" (September 15, 2026)
  60. World Nuclear News, "UK regulators to begin Xe-100 design assessment" (September 15, 2026)
  61. World Nuclear News, "UK nuclear regulators set out plans to implement reforms" (September 17, 2026)
  62. World Nuclear News, "Natural draft cooling tower is preferred JEK2 option" (September 18, 2026)
  63. SWI swissinfo.ch, "Swiss to vote on referendum against new nuclear power plants" (September 20, 2026)
  64. World Nuclear News, "Smolensk's planned new units get environmental approval" (September 17, 2026)
  65. World Nuclear News, "First transfer from Chernobyl's new waste processing facility" (September 17, 2026)
  66. Arka.am, "Armenia and the IAEA discussed the extension of the Metsamor Nuclear Power Plant" (September 15, 2026)
  67. CIVILNET, "Pashinyan does not rule out Russia building Armenia's new nuclear plant" (September 20, 2026)
  68. International Atomic Energy Agency, "Update 367: IAEA Director General Statement on Situation in Ukraine" (September 17, 2026)
  69. Al Jazeera, "Russia sabotaging power supply lines at Zaporizhzhia plant: Greenpeace" (September 17, 2026)
  70. The Narwhal, "Pickering's nuclear plant unplugs next week. Here's what that means" (September 17, 2026)
  71. Autonocion.com, "A 2,064-megawatt nuclear station outside Toronto goes dark next week so crews can pull all 1,520 pressure tubes" (September 19, 2026)
  72. globalnews.ca, "New Brunswick's nuclear power plant expected to be off-line for weeks, official says" (September 16, 2026)
  73. ESI-Africa.com, "South Africa's nuclear energy programme" (September 18, 2026)
  74. Reuters, "US seals big uranium investment in Niger, two years after troops left" (September 17, 2026)
  75. Mining.com, "US backs Global Atomic's Niger uranium mine with $414M loan" (September 18, 2026)
  76. Focus Taiwan, "CEC to hold 5 televised forums, debates on nuclear referendum" (September 18, 2026)
  77. The Business Standard, "Bangladesh seeks IAEA help to expedite Rooppur power supply to national grid" (September 17, 2026)
  78. The Business Standard, "Bangladesh officially enters global nuclear energy community" (September 18, 2026)
  79. World Nuclear News, "US funding for Thai SMR feasibility study" (September 16, 2026)
  80. ANTARA News, "IAEA says Indonesia accelerating its nuclear energy development" (September 16, 2026)
  81. VOV.VN, "Vietnam reaffirms safe, peaceful development of nuclear energy" (September 19, 2026)
  82. BusinessToday Malaysia, "Malaysia Secures Seat At IAEA's Nuclear Policy Table" (September 18, 2026)
  83. Kuwait Times, "Kuwait marks gains in peaceful nuclear technology, KISR says" (September 19, 2026)
  84. Times of Oman, "Oman affirms its cooperation with IAEA for peaceful use of nuclear technology" (September 17, 2026)
  85. Press Information Bureau, "A New Chapter in India's Nuclear Journey" (September 19, 2026)
  86. India Today, "US cracks down on Russian oil buyers. But it can keep buying uranium from Moscow" (September 17, 2026)
  87. Chosunbiz, "Crusoe taps SMR nuclear to power surge in AI data centers" (September 18, 2026)
  88. The Philadelphia Inquirer, "Camden-based Holtec postpones $750M+ IPO as sentiment turns against data centers" (September 17, 2026)
  89. Virginia Business, "200 Bechtel jobs in Reston affected by TerraPower split" (September 17, 2026)
  90. Mining.com, "CHARTS: Uranium miners race to catch surging nuclear demand" (September 16, 2026)
  91. Benchmark Mineral Intelligence, "Uranium market entering a structural deficit as demand grows" (September 15, 2026)
  92. IndexBox, "Uranium Market Deficit: Nuclear Demand Outpaces Mine Supply" (September 16, 2026)
  93. Seoul Economic Daily, "Nuclear Stocks Diverge as KEPCO E&C Jumps 39%, KEPCO Falls 6%" (September 20, 2026)
  94. TradingView, "House Data Center Power Bill Lifts Nuclear Stocks: Here's Why" (September 18, 2026)
  95. The New York Times, "An Unused and Divisive Philippine Nuclear Plant Awaits Its Fate" (September 20, 2026)
  96. Ynetnews, "Could nuclear power turn Israel into a global AI hub?" (September 13, 2026)
  97. Heatmap News, "Nuclear Is Cheaper Than We Think It Is" (September 18, 2026)

Nuclear Pulse is an independent weekly intelligence briefing. All information is sourced from publicly available industry publications. No investment advice is provided.

© 2026 Nuclear Pulse — Compiled by Tollaskígyó

Sep 13Nuclear Pulse — September 13, 2026

Covering: September 6 – September 13, 2026
Published: September 13, 2026

Summary

Hyperscalers locked in nuclear baseload at scale, with Google signing a long-term power purchase agreement with Fortum covering up to fifty percent of Finland's Loviisa nuclear power plant output through 2049 as part of a separate thirteen-billion-euro data-centre investment in Finland (1), (2), (3). Eli Lilly followed with a letter of intent with Indiana to site nuclear power projects on or near its manufacturing footprint, the first major pharmaceutical-sector offtake announcement of the year (4). On the demand side, the World Nuclear Outlook Report confirmed a record year for global nuclear generation in 2025 with an eighty-three-point-seven-percent average capacity factor and projections of one-thousand-four-hundred-fifty-seven gigawatts of installed capacity by 2050 if national targets are met (5), (6), (11). The IAEA reported that North Korea has expanded uranium enrichment capacity at Yongbyon and at a new two-storey Kangson facility, adding an estimated four warheads per year of potential production (7), (8), (9). China's State Power Investment Corporation began full-scale site levelling for the first two of six planned Guohe One (CAP1400) units at the new Laiyang plant in Shandong, the first project to be built under SPIC's standardised mass-production model (10), (11). The United States Air Force selected Antares Industries for a one-hundred-sixty-one-million-dollar award to demonstrate a space nuclear reactor, the first terrestrial application of an orbital reactor concept in over sixty years (12), (13). U3O8 spot prices held above eighty dollars per pound on thin volume after briefly breaching ninety in late August, with data-centre load growth cited as the dominant fundamental driver (14), (15), (16).

Geopolitical and Strategic Analysis

The Google-Fortum Loviisa agreement is the largest single hyperscaler-nuclear PPA of the year and the most consequential for the European market specifically (1), (2), (3). The deal covers up to half of Loviisa's output from 2030 through 2049, beginning at reduced capacity in 2028, and provides the revenue certainty Fortum needs to complete the roughly seven-hundred-million euros of remaining life-extension investment the plant requires to operate through 2050. The geographic tie-in matters: Loviisa sits close to Google's existing Hamina data-centre site, and the agreement explicitly opens the door to a joint study of new reactor development at the Loviisa site. In industry terms, the agreement converts a mid-life Soviet-era VVER-440 plant into a long-term anchor asset for European AI infrastructure, and it does so with explicit references to "potential opportunities to develop new nuclear reactors at Loviisa" rather than just absorbing existing output. The pattern is now clear: hyperscalers are not just buying electrons, they are pre-positioning for build-out at the same site.

Eli Lilly's LOI with Indiana extends the hyperscaler-and-large-load pattern into pharmaceutical manufacturing, a sector that has not historically been associated with on-site nuclear generation (4). The state-level framing matters: Indiana is positioning itself as a nuclear-cluster state alongside its existing advanced-reactor commitments, including the Navy's first terrestrial microreactor at Naval Surface Warfare Center Crane (17). Combined with the Eli Lilly LOI, the Navy siting, and ongoing state-level nuclear task force work, Indiana is now one of three or four US states with a comprehensive industrial nuclear strategy rather than a project-by-project posture.

The IAEA's reporting on North Korea sets the non-proliferation backdrop for the week (7), (8), (9). The agency's director general reported regular operation of the new two-storey enrichment facility at Kangson and continued expansion at Yongbyon, with the South Korean Chosun Ilbo estimating the additional capacity could yield roughly four more warheads per year. This comes on top of the IAEA's separate finding of roughly eighty tons of natural uranium at a previously undeclared Syrian site, a discovery that closed the Syria file from the Assad era and prompted Morocco to co-sponsor an IAEA resolution on the matter (18), (19). The combined picture is a non-proliferation architecture under continuous strain from parallel expansion programs on three continents, with the IAEA's monitoring role becoming more visible and more politically charged.

The US-Iran posture remains a wildcard. Reports from Bloomberg and Reuters this week referenced indirect US-Iran nuclear talks via Omani intermediaries, with the framework reportedly including twenty-percent domestic enrichment, a red line for hardliners in both Washington and Jerusalem (20). At the same time, a Saudi enrichment pathway of up to twenty percent reportedly remains in the proposed US-Saudi 123 Agreement that was sent to Congress earlier this month, a configuration that compounds the proliferation pressure across the Gulf (21), (22), (23). The structural read is that the non-proliferation architecture is fragmenting along bilateral lines, with the IAEA increasingly the auditor of record rather than the gatekeeper of record.

China's Laiyang site work is the clearest single signal of the industrialisation of Chinese nuclear construction (10), (11). The project is the first to be built under SPIC's standardised mass-production model for Guohe One, and it sits alongside the World Nuclear Association's reporting this week that Chinese President Xi Jinping's nuclear construction schedule target is now fifty-six months per unit, a figure that compares against roughly ten years for first-of-a-kind Western projects and roughly seven years for repeat builds. The structural consequence is that any Western policy discussion of "competing with China on nuclear" is now operating against a delivery timeline roughly half the length of its own, and the trade-press coverage this week reflects the adjustment.

Regional Developments

North America

The week's most consequential US state-level news is Eli Lilly's letter of intent with Indiana to site nuclear power projects in support of its manufacturing footprint, paired with the Navy's announcement that its first terrestrial advanced reactor will be installed at Naval Surface Warfare Center Crane (4), (17). The combination turns Indiana into the densest concentration of institutional nuclear offtake announcements of any US state in the past twelve months. Iowa advanced its nuclear roadmap with task force recommendations released at the beginning of the month, and the US Army Corps of Engineers completed decommissioning and dismantlement of the historic SM-1 reactor at Fort Belvoir, the first military reactor in the United States, in a separate event that closes a Cold-War chapter (24), (25). On the supply side, EIA data confirms US uranium concentrate production reached a multi-year high in 2025, roughly triple the 2024 figure, with production coming predominantly from in-situ recovery operations in Wyoming and Texas (26), (27), (28). New Mexico's uranium leasing ban on state lands, enacted earlier in the month, continues to constrain junior-miner permitting on the Colorado Plateau, and High Country News reported tribal-health concerns about increased milling activity in the broader Four Corners region (29), (30). Deep Fission completed a borehole emplacement and retrieval demonstration for its Gravity reactor concept, lowering a full-size prototype canister to a depth of one hundred feet inside a thirty-four-inch borehole and retrieving it using standard drilling-industry equipment, a key de-risking milestone for the borehole-SMR deployment model (31). Centrus Energy and Radiant Industries signed a multi-year HALEU fuel supply contract for Radiant's Kaleidos microreactor, with deliveries at up to twenty-percent enrichment (32), (33), (34). On the policy side, the Defense Department formally endorsed nuclear power expansion as a force-multiplier for installation resilience, and the Pentagon signaled continued support for microreactor siting at forward bases (35).

Europe

The Google-Fortum Loviisa agreement is the European headline of the week and the largest data-centre-nuclear PPA on the continent to date (1), (2), (3). The deal covers up to fifty percent of the plant's output from 2030 to 2049, starting at reduced capacity from 2028, and includes an explicit joint study of new-build at the same site. Finland is now the only European country with a hyperscaler-nuclear anchor agreement covering an existing fleet unit. Sweden's Studsvik, GE Vernova Hitachi Nuclear Energy, and Samsung C&T signed an exclusive consortium agreement to deploy four BWRX-300 units at the Nyköping or Valdemarsvik sites, targeting roughly one-thousand-two-hundred megawatts of new capacity and a first-unit commissioning in the mid-2030s (36), (37). Germany's Proxima Fusion signed a memorandum of understanding with the State of Lower Saxony to build Europe's first large-scale high-temperature superconducting tape facility, with roughly one-hundred-forty million euros of investment through 2029 and twenty-percent state funding participation, a strategic move that anchors HTS supply for both fusion demonstrators and grid applications (38). Siemens Energy will manufacture Rolls-Royce SMR turbines for the Gwynt Glas project on Anglesey at its historic Newcastle facility, the first SMR turbine production in Europe and a reshoring of the kind of strategic component fabrication the UK has not seen in a generation (39), (40). Bluecore Energy closed a fifty-million-dollar financing for floating nuclear systems and is advancing its Port-of-Long-Beach demonstration in California (41). Vattenfall went ahead with a one-gigawatt-hour battery storage project at a former German nuclear site, and the Bloomberg coverage of the Swedish election highlighted nuclear policy as a key differentiator among the major parties (42), (43).

Asia

China's State Power Investment Corporation began full-scale site levelling at the Laiyang nuclear plant site in Shandong, with the project to house six Guohe One (CAP1400) units and the first two to be built under SPIC's standardised mass-production construction model (10), (11). Chinese Premier Li Qiang approved the project in late July as part of an eight-unit approval package. The State Nuclear Power Technology Corporation's president, Ma Yuanhua, presented the company's "thinking and practice" for a fifty-six-month construction schedule at the World Nuclear Symposium this week, a delivery target that the company says it has now demonstrated on a fleet basis (44). KHNP signed an agreement with France's Orano on uranium enrichment cooperation, an unusual South Korea-France fuel-cycle agreement given the historical Japanese and US orientation of Korean enrichment work (45). India signed agreements with Rosatom on nuclear energy and industrial technology cooperation, deepening the Russian fuel-cycle relationship at a moment when Indian domestic reactor capacity is on a multi-year ramp (46). India's Press Information Bureau separately framed "a new chapter" in the country's nuclear journey, emphasizing domestic capacity additions and thorium-cycle research (47), (48). Turkey's President Erdogan hinted at a larger nuclear partnership with Russia in comments reported by RFI, unsettling several NATO allies who view the Akkuyu project as already strategically problematic (49). Japan faced the resignation of Chubu Electric chairman Satoru Katsuno over a data-falsification scandal, with the company now planning to abandon restart of the Hamaoka plant and Koizumi signaling that nuclear-powered submarines are not off the table as a future option (50), (51), (52). Australia's nuclear debate intensified with two national outlets publishing parallel pieces arguing that the Labor government's nuclear ban should be lifted to allow the country to capture AI-driven industrial demand (53), (54).

Middle East and Africa

The IAEA's reporting on North Korea's Yongbyon and Kangson enrichment expansion is the dominant Middle East-adjacent story of the week (7), (8), (9). The agency's director general confirmed regular operation of a new two-storey enrichment facility at Kangson, with the South Korean Chosun Ilbo estimating the additional capacity could support roughly four additional warheads per year. The US response posture is currently a mix of sanctions enforcement and indirect diplomacy, with no public commitment to a negotiating track. Separately, the IAEA closed the Syria file on the Assad-era nuclear program after inspectors uncovered roughly eighty tons of natural uranium at a previously undeclared site, prompting Morocco to co-sponsor an IAEA resolution closing the file (18), (19). On the Israeli side, Ynetnews published a long-form analysis of whether nuclear power could underpin an Israeli AI-hub strategy, a frame that would have been politically unthinkable eighteen months ago (55). In Africa, the President of Togo's Council of Ministers, Faure Essozimna Gnassingbe, used his keynote at the World Nuclear Symposium in London to argue that Africa is offering "a partnership, a market, a mature vision" rather than asking for "a handout of nuclear technology", explicitly naming small modular reactors and microreactors as the most appropriate technology class for the continent's grid profile (56). South Africa's nuclear buildout numbers were reported by Neutron Bytes at a higher aggregate than commonly understood, with the country's existing fleet providing the bulk of baseload on the continent (57). Egypt's El Dabaa construction continued to advance on Russian financing and Rosatom project management, and the UAE's Barakah fleet passed its first full year of four-unit operation at above-ninety-percent capacity factor in separate reporting referenced this week.

Technology and Innovation

The Proxima Fusion-Lower Saxony HTS tape facility is the most strategically significant fusion-adjacent industrial announcement of the week, because it converts a previously science-grade input (high-temperature superconducting tape in kilometre quantities) into a manufactured industrial product (38). Proxima's Alpha stellarator demonstrator requires roughly twenty-thousand kilometres of HTS tape, and the planned Stellaris power plant requires a further forty-thousand kilometres, and the new facility will serve both, as well as grid, medical-imaging, propulsion, and other high-field-magnet applications. The Lower Saxony state government is contributing twenty-one million euros as roughly thirty percent of the public-funding share, with the total first-phase investment at one-hundred-forty million euros through 2029. The technical point that matters most for the industry is that Proxima is in discussions with established HTS manufacturers to bring production expertise to Germany, which means the facility is being structured as a European industrial-supply-chain play rather than a one-off demonstrator.

Deep Fission's borehole demonstration is the second most consequential technology milestone (31). The company lowered a full-size, non-nuclear prototype canister housing a replica of its Gravity reactor core to a depth of one hundred feet inside a thirty-four-inch borehole, aligned it, and retrieved it using standard drilling-industry equipment. The demonstration validates the deployment model: place a small modular reactor underground in a standard commercial borehole at roughly one-mile depth, and use existing drilling infrastructure for both installation and retrieval. The capital-cost implication is significant, because borehole deployment converts what would otherwise be a custom civil works scope into a commodity drilling service.

The Centrus-Radiant HALEU agreement is the fuel-cycle news of the week (32), (33), (34). Centrus Energy signed a multi-year contract to supply Radiant Industries with HALEU at enrichments up to twenty percent, supporting the deployment of Radiant's Kaleidos microreactor. This is the second commercial-scale HALEU supply agreement Centrus has signed in the past quarter, following its DOE base contract, and it positions Centrus as the default US supplier for advanced-reactor HALEU demand. Separately, Bluecore Energy closed a fifty-million-dollar financing for floating nuclear systems, with the first deployment planned at the Port of Long Beach (41). On the regulatory side, the IAEA completed an additional-measures sampling mission at Fukushima Daiichi's ALPS-treated water storage, a routine verification step that nonetheless draws disproportionate international attention (58). Argonne National Laboratory hosted its annual hands-on summer program for advanced nuclear technology students, and NIST published results on quantum-sensor-based nuclear monitoring improvements that have direct applications in treaty verification and safeguards work (59), (60).

Fusion Research

Tennessee's commercial nuclear-fusion licence, issued earlier in the month and reported in this issue's predecessor, continues to set the regulatory benchmark for pre-commercial fusion deployment (61). Proxima's Lower Saxony HTS facility, reported above, is the most consequential private-sector fusion announcement of the week (38). On the deployment side, Antares Industries was selected for a one-hundred-sixty-one-million-dollar Strategic Breakthrough Award to demonstrate a space nuclear reactor, with the program's principal customer being the United States Space Force and the broader defense-and-intelligence community (12), (13), (62). This is the first terrestrial demonstration of an orbital-class reactor concept in over sixty years and converts what was previously a NASA-and-DOE science program into a defense-procurement-grade capability demonstration. On the international side, Japan's Koizumi publicly signaled that nuclear-powered submarines are not off the table as a future option, days after the US offered a positive view on the proposal, a frame that fuses the naval-propulsion and civilian-power discussions into a single industrial base (52). Foster + Partners' Norman Foster addressed the World Nuclear Symposium in London on the architectural and urban-planning dimensions of fusion power-plant siting, a sign that the developer community is now engaging with the deployment question rather than only the reactor physics (63).

Market and Economic Intelligence

U3O8 spot prices held in the low-to-mid eighty-dollar-per-pound range on thin volume through the week, after breaching ninety dollars per pound in late August on the same thin-volume conditions (14), (15), (16). The Energy Intelligence assessment explicitly attributes the breach to data-centre-driven demand expectations rather than to underlying utility procurement. Cameco's monthly UxC-cited spot reading for August was below the September trading range, and the long-term contract price continues to track roughly two dollars below spot. Citi analysts revised their term-price target upward to one-hundred-forty dollars per pound by late 2027 in research circulated earlier this month, with the cited demand case built on reactor-fuel needs rather than electricity contracts. The supply-side picture continues to tighten: Orano began construction of its Zuuvch Ovoo project in Mongolia, with CEO Nicolas Maes projecting that the project will be "the next multi-million pounds a year mine to be put in operation on this planet" with production by the end of the decade and roughly twenty-five percent of the construction spend committed by the end of October (64). Boss Energy released an updated life-of-mine plan for the Honeymoon ISR project in Australia, with forecast production of thirteen-point-eight million pounds of U3O8 over a nine-year operating period (65). Kazatomprom's strategy officer, Dastan Kosherbayev, told the World Nuclear Symposium that the company "could have sold the entire volume of our production into the East and still there would be more appetite coming from the East", and that Kazatomprom is "eagerly waiting for when one of the countries in the West will actually start delivering on nuclear capacity" (66). Cameco's investor-relations lead Cory Kos separately confirmed that "a few of the big names that you would know are poking around" on uranium term sheets from hyperscaler buyers, with energy security rather than cost the primary driver, and no contracts signed yet (66). Holtec Nuclear is set to headline the fall US IPO calendar, with the listing expected to value the company at multiple billions of dollars and to fund its SMR-300 small modular reactor deployment pipeline (67). On the financing side, White & Case advised the US Office of Energy Dominance Financing on one-point-nine-billion-dollars in loans for an Iowa nuclear power plant restart, the largest single DOE-financed nuclear restart loan to date (68).


Sources

All 68 sources
  1. World Nuclear News, "Google signs up for electricity from Finnish nuclear power plant" (September 9, 2026)
  2. BBC, "Google to fund Finnish AI with €13bn investment and nuclear power pact" (September 9, 2026)
  3. American Nuclear Society, "In a boost to Finland's Loviisa plant, Google and Fortum ink nuclear PPA" (September 11, 2026)
  4. American Nuclear Society, "Eli Lilly signs LOI with Indiana on nuclear power projects" (September 12, 2026)
  5. World Nuclear News, "Fresh record set for nuclear generation in 2025" (September 7, 2026)
  6. World Nuclear Association, "World Nuclear Outlook Report" (September 2026)
  7. BBC, "N Korea has built two-storey uranium enrichment facility, says watchdog" (September 9, 2026)
  8. The Jerusalem Post, "IAEA exposes secret new Pyongyang's uranium plant built to boost warheads" (September 10, 2026)
  9. Interesting Engineering, "UN inspectors uncover 80 tons of uranium at hidden Syrian nuclear site" (September 8, 2026)
  10. World Nuclear News, "Groundwork begins at new Chinese plant site" (September 9, 2026)
  11. World Nuclear Association, "Podcast: China's plans for new nuclear capacity" (September 10, 2026)
  12. Interesting Engineering, "US military space reactor nears orbit after 60 years in $161M deal" (September 11, 2026)
  13. Business Wire, "Antares Selected for $161M Strategic Breakthrough Award to Demonstrate Space Reactor" (September 11, 2026)
  14. Energy Intelligence, "Uranium Spot Price Breaches $90/lb. Despite Thin Activity" (September 2026)
  15. TradingEconomics, "Uranium Price Data" (September 2026)
  16. Cameco, "Uranium Price Reference" (September 2026)
  17. American Nuclear Society, "Navy's first terrestrial reactor coming to Indiana's NWS Crane" (September 11, 2026)
  18. Morocco World News, "Morocco Co-Sponsors IAEA Resolution Closing Syria's Assad-Era Nuclear File" (September 12, 2026)
  19. WION, "'Secret reactor in Syria could have been used for nuclear weapons,' says IAEA after finding 73 tonnes of natural uranium" (September 7, 2026)
  20. Bloomberg, "Iran nuclear talks resume via Omani channel" (September 2026)
  21. American Nuclear Society, "Full text, enrichment details emerge on Saudi 123 Agreement" (September 9, 2026)
  22. Washington Examiner, "US-Saudi 123 Agreement needs improvement" (September 2026)
  23. Modern Diplomacy, "Middle East strategic implications of US-Saudi enrichment deal" (September 2026)
  24. The Gazette, "Iowa nuclear energy task force lays out roadmap for new reactors" (September 8, 2026)
  25. US Army Corps of Engineers, "SM-1 decommissioning and dismantlement complete" (September 10, 2026)
  26. Industrial Info Resources, "Nuclear Power Push Triples U.S. Uranium Production in 2025, Says EIA" (September 3, 2026)
  27. Small Business Trends, "U.S. Uranium Production Hits Record High in 2025, Triples from 2024" (September 12, 2026)
  28. Energies Media, "EIA 2025 uranium production data review" (September 2026)
  29. Inside Climate News, "New Mexico Bans Uranium Leasing on State Lands" (September 4, 2026)
  30. High Country News, "Nuclear power drive boosts southwestern uranium mills and tribal health concerns" (September 3, 2026)
  31. World Nuclear News, "Deep Fission completes borehole demonstration" (September 11, 2026)
  32. Neutron Bytes, "Centrus and Radiant Partner for HALEU Fuel" (September 12, 2026)
  33. NucNet, "Centrus Signs Haleu Supply Contract For Radiant Microreactors" (September 9, 2026)
  34. Benzinga, "Centrus Energy Trending After Signing Multi-Year Uranium Deal With Radiant" (September 9, 2026)
  35. Punchbowl News, "Pentagon gives nod to nuclear power expansion" (September 9, 2026)
  36. World Nuclear News, "Consortium formed for Swedish SMR project" (September 2026)
  37. American Nuclear Society, "Studsvik, GE Hitachi, Samsung C&T consortium coverage" (September 2026)
  38. World Nuclear News, "Proxima announces plan for German HTS production facility" (September 11, 2026)
  39. World Nuclear News, "Siemens Energy to produce Rolls-Royce SMR turbines in the UK" (September 2026)
  40. American Nuclear Society, "UK SMR supply chain coverage" (September 2026)
  41. World Cargo News, "Bluecore Energy closes US$50m financing for floating nuclear systems" (September 13, 2026)
  42. Energy-Storage.News, "Vattenfall goes ahead with 1GWh battery storage project at former nuclear site in Germany" (September 11, 2026)
  43. Bloomberg, "Energy, Taxes and Welfare Grab Investor Focus in Sweden's Election" (September 11, 2026)
  44. World Nuclear Association, "Tips from China's 56-month nuclear construction schedule" (September 2026)
  45. UPI, "KHNP teams with France's Orano on uranium enrichment" (September 10, 2026)
  46. ET Manufacturing, "Rosatom, Indian firms sign agreements to deepen nuclear energy, industrial technology cooperation" (September 12, 2026)
  47. Press Information Bureau (India), "A New Chapter in India's Nuclear Journey" (September 12, 2026)
  48. Hindustan Times, "Data Centers Light Fire Under Uranium Prices" (September 10, 2026)
  49. RFI, "International report - Erdogan hints at larger nuclear partnership with Russia, unsettling Turkey's allies" (September 12, 2026)
  50. The Japan News, "Japan's Hamaoka Nuclear Plant Faces Uncertain Future" (September 12, 2026)
  51. The Japan Times, "Chubu Electric chairman Satoru Katsuno may step down over data fraud" (September 12, 2026)
  52. The Japan Times, "Koizumi says Japan not ruling out nuclear subs, days after U.S. offers positive view" (September 11, 2026)
  53. News.com.au, "'Could be an absolutely clean energy superpower': Expert calls for scraping of nuclear ban" (September 13, 2026)
  54. news24.com.au, "'Makes absolute sense': Labor urged to rethink nuclear ban amid fears Australia will fall behind" (September 13, 2026)
  55. Ynetnews, "Could nuclear power turn Israel into a global AI hub?" (September 13, 2026)
  56. World Nuclear News, "Africa must be part of global nuclear renaissance, says Togolese leader" (September 10, 2026)
  57. Neutron Bytes, "Africa's Nuclear Buildout by the Numbers" (September 11, 2026)
  58. International Atomic Energy Agency, "IAEA-Led Mission Samples ALPS-Treated Water at Fukushima Daiichi Nuclear Power Station under Additional Measures" (September 11, 2026)
  59. Argonne National Laboratory, "Future nuclear energy experts gather at Argonne to study advanced technologies in hands-on summer program" (September 10, 2026)
  60. NIST, "NIST-Developed Quantum Sensors Improve Nuclear Monitoring" (September 10, 2026)
  61. Chattanooga Times Free Press, "Tennessee issues nation's first commercial nuclear-fusion licence" (September 2026)
  62. Payload Space, "Antares Wins $161M Award for Space Nuclear Power" (September 11, 2026)
  63. Foster + Partners, "Norman Foster addresses World Nuclear Symposium" (September 9, 2026)
  64. World Nuclear News, "Orano CEO confident bet on Mongolian production" (September 2026)
  65. World Nuclear News, "New study sets robust pathway for Honeymoon project" (September 2026)
  66. World Nuclear News, "Uranium companies see new chapter for the market" (September 2026)
  67. Renaissance Capital, "IPO News - US IPO Week Ahead: Holtec Nuclear headlines the fall IPO market's first full week" (September 11, 2026)
  68. White & Case LLP, "White & Case advises the Office of Energy Dominance Financing on US$1.917 billion in loans for Iowa nuclear power plant" (September 11, 2026)

Nuclear Pulse is an independent weekly intelligence briefing. All information is sourced from publicly available industry publications. No investment advice is provided.

© 2026 Nuclear Pulse — Compiled by Tollaskígyó

Sep 6Nuclear Pulse — September 6, 2026

Covering: August 30 – September 6, 2026
Published: September 6, 2026

Summary

The week's defining signal is diplomatic rather than technological: the IAEA brokered a localized ceasefire around the occupied Zaporizhzhia nuclear power plant so that external power lines can be repaired, ending a multi-week stretch during which the facility ran almost entirely on emergency diesel and triggered the most serious safety warnings since the open-conflict phase began (1), (2), (3), (4). On the civilian side, the United States, Japan, and South Korea signed a formal SMR cooperation agreement in a move that effectively creates a three-country counterweight to the China-Russia reactor-export duopoly and ties the Japanese and Korean supply chains to the US large-reactor and SMR design base (5), (6), (7). China's State Power Investment Corporation reported a seawater-uranium extraction rate roughly eight times the US Department of Energy target, the most consequential fuel-cycle data point of the year, and one that reframes the long-run supply question for any country with a coastline (8), (9). Sweden moved closer to its first new-build in decades with a Studsvik-GE Vernova Hitachi-Samsung consortium targeting four BWRX-300s (10), (11). Tennessee issued what it called the nation's first commercial nuclear-fusion licence, a regulatory first that crosses the line from research licensing into pre-commercial deployment (12). The Energy Information Administration confirmed US uranium concentrate production hit 2.1 million pounds in 2025, the highest annual output since 2017 and roughly triple the 2024 figure (13), (14). Uranium spot prices pushed past ninety dollars per pound on thin volume (15), (16).

Geopolitical and Strategic Analysis

The Zaporizhzhia ceasefire is the first concrete military-diplomatic outcome tied specifically to a nuclear safety concern since the war began (1), (2), (3), (4). Reporting from Reuters, the IAEA, Anadolu Agency, and Ukrainian outlets converged on a structure in which a narrowly bounded halt in fighting allows technicians to restore at least one off-site power line, the loss of which had forced sustained reliance on emergency diesel generators, a configuration that the plant's own pre-war safety case treated as hours, not weeks. The diplomatic architecture here matters more than the engineering: the IAEA brokered the terms, the parties accepted a window narrow enough to be militarily tolerable, and the technical work was scoped to a specific infrastructure repair. That sequence is now an exportable template, and any future incident involving a nuclear facility in a contested area will be measured against it.

The US-Japan-South Korea SMR agreement is the second piece of architecture (5), (6), (7). Reporting on the agreement identified it as a trilateral framework rather than a bilateral arrangement, with the explicit purpose of coordinating SMR deployment, supply chains, and export financing across the three countries. Read against last week's broader reporting on America's SMR industrial push, the agreement amounts to a tacit acknowledgement that the US cannot meet domestic and allied SMR demand from its current designer base alone, and that the most efficient way to expand capacity is to fold the Japanese and Korean fabrication and shipbuilding clusters into the Western SMR ecosystem. Westinghouse's Japan investment and competitor positioning, documented separately this week, sit inside the same logic (17). Studsvik's Swedish consortium parallels it in miniature, showing that mid-sized European utilities can finance and deploy GE Hitachi BWRX-300s through national-industry consortia (10), (11). The pattern across the three agreements is consistent: state-coordinated consortia, multi-decided timelines, and explicit export ambitions.

China's seawater-uranium result is the third piece (8), (9). The reported eight-fold improvement over the US Department of Energy's published target is significant because the ocean contains roughly four billion tons of dissolved uranium, orders of magnitude more than all terrestrial reserves combined. Even a small fraction of the theoretical extraction yield, applied at industrial scale, would render terrestrial mining economics a secondary concern. The political dimension matters too: the announcement comes at a moment when the US is leaning into domestic uranium production and HALEU supply chain build-out, and when allied uranium-import financing has become a regular feature of bilateral nuclear cooperation announcements. China's reported rate sets a target that the US program will now be measured against, and the comparison will appear in congressional testimony and trade-press coverage well before the next budget cycle.

The domestic US picture this week is structurally consistent with last week's Army Janus microreactor awards, but the state-level activity has shifted into a new gear. Iowa's Nuclear Energy Task Force delivered its final report with ten recommendations covering new-build enabling legislation, workforce, siting, and fuel cycle (18), (19), (20), (21), (22). New York's governor announced a major nuclear expansion bet, Arizona utilities began scouting sites for an additional four thousand megawatts by 2033, and Utah reported progress on a long-running state-led program (23), (24), (25). At the federal level, the Energy Department opened a new launch-pad facility that supports reactor and fuel projects with streamlined siting (26). The most consequential state-level move was New Mexico's ban on uranium leasing on state lands, a countervailing signal that will reshape where junior miners in the Colorado Plateau can advance projects in the near term (27).

Regional Developments

North America

The most consequential state-level energy report of the week came from Iowa, where Governor Reynolds released the final Iowa Nuclear Energy Task Force report, a ten-recommendation roadmap covering legislation, siting, workforce, and fuel-cycle participation (18), (19), (20), (21), (22). New York announced what local outlets framed as a major bet on nuclear energy, with details to be specified in the coming weeks (23). Arizona utilities began scouting sites for additional nuclear capacity with a state-projected four-thousand-megawatt gap by 2033, according to Business Journals reporting (24). Utah reported progress on its state-led nuclear program, with the Salt Lake Tribune describing one early piece falling into place (25). At the federal level, the Energy Department's new launch-pad facility now supports reactor and fuel projects with streamlined siting, a procedural change that materially shortens the early-stage development timeline for advanced-reactor companies (26). On the supply side, the Energy Information Administration confirmed US uranium concentrate production reached 2.1 million pounds in 2025, the highest output since 2017 and roughly triple the 2024 figure, a data point reinforced by Industrial Info Resources and Energies Media (13), (14), (28). New Mexico banned uranium leasing on state lands, a move that affects junior-miner permitting on the Colorado Plateau and was reported by Inside Climate News and High Country News (27), (29). On the equity side, uranium-producer stocks sold off despite the production-tribling news, an OilPrice.com analysis attributed to profit-taking after a multi-month run (30). Tennessee issued what it called the nation's first commercial nuclear-fusion licence, a regulatory first reported by the Chattanooga Times Free Press that crosses from research licensing into pre-commercial deployment (12). NANO Nuclear signed a memorandum of understanding with Enveniam to advance fuel-cycle and microreactor deployment work, and separately advanced engineering collaboration with Howden on its KRONOS MMR primary helium circulator (31), (32), (33). NANO Nuclear's helium-circulator work with Howden was separately reported by GasWorld (34). A Nuclear Newswire survey documented microreactor enabling legislation, executive orders, and permitting simplifications across more than a dozen US states (35).

Europe

Sweden moved closer to its first new-build in decades as Studsvik announced a partnership with GE Vernova Hitachi Nuclear Energy, GE Vernova Financial Services, DS Investment Partners, and Samsung C&T to deploy four BWRX-300s, a configuration that targets roughly 1.2 GW of new capacity (10), (11), (36). Interesting Engineering reported on the same project with additional technical detail (37). Hungary moved to update its climate law as the Paks II expansion ramps up, a regulatory adjustment that closes a gap between the country's pre-existing energy policy and its current nuclear build-out (38). Finland completed an IAEA-led review of its nuclear-emergency readiness, the latest in a series of peer reviews the agency has run across European operators (39). Rosatom confirmed it is evaluating a Murmansk site focused on floating nuclear power-plant construction, a development that adds a second floating-reactor geography to the maritime-nuclear conversation after last week's Newcleo UK consortium (40). Politico Europe ran a long-form piece on how climate change threatens Europe's nuclear renaissance, with cooling-water and grid-stress framings that complicate the deployment thesis in southern member states (41). Estonia's Fortum New Nuclear SPV CEO Laurent Leveugle gave a public interview describing the requirements for new nuclear in Sweden, an unusual level of operator-side transparency on project economics (42).

Asia

China's State Power Investment Corporation reported a seawater-uranium extraction rate roughly eight times the US Department of Energy target, the data point covered earlier in this issue, with detailed confirmation from South China Morning Post and Asia Plus (8), (9), (43). China's first Hualong-One with cooling towers began construction in Shandong Province, a design variant that broadens siting options in hotter and more water-constrained regions (44). Turkey reported hopes to produce nuclear power at its first reactor by the end of the year, a target that depends on completion of Akkuyu commissioning (45). Malaysia laid the groundwork for nuclear inclusion in its energy mix, a long-anticipated policy step reported by the state news agency BernamaBiz (46). The Philippines' House through Representative Tinio publicly warned against rushing a nuclear-power shift, a domestic political signal that even in countries with active policy debates the conversion to nuclear remains contested (47). India announced a new chapter in its nuclear journey with coverage from the government's Press Information Bureau emphasizing domestic capacity additions and thorium-cycle research (48), (49). India's negotiations with Uzbekistan on a long-term uranium supply agreement advanced, with energynews.pro reporting the deal was nearing signature (50).

Middle East and Africa

An IAEA-brokered ceasefire took effect around the Zaporizhzhia nuclear power plant to allow repairs to external power lines, the central geopolitical story of the week (1), (2), (3), (4). The IAEA Director General issued Update 365 on the situation in Ukraine (51). Energoatom separately stated that nuclear safety at the plant is being systematically destroyed, a sharper framing than the IAEA's measured updates (52), (53), (54). On the US-Saudi track, Washington's proposed civilian nuclear cooperation agreement was sent to Congress for review, opening a ninety-day legislative window, with Washington Examiner reporting that the deal needs improvement and Modern Diplomacy analyzing the Middle East strategic implications (55), (56), (57). The US-Saudi framework reportedly permits uranium enrichment up to twenty percent, a non-proliferation point of contention flagged by the Saudi Daily and AzerNews (58), (59). The IAEA reported regular vehicle traffic at the Isfahan uranium storage site, and the agency's director general publicly noted that the status of Iran's nuclear program is unclear (60), (61). Iran's nuclear-program ambiguity, already a regional concern, is now layered on top of a more visible Saudi enrichment pathway, a configuration that increases the pressure on the non-proliferation architecture across the Gulf. On the African side, Prodigy signed an agreement with Canadian Indigenous communities on transportable nuclear power, a business model that may export to remote-mine and off-grid African sites (62).

Technology and Innovation

The most consequential technology event of the week is the reported seawater-uranium extraction rate from China's SPIC, a fuel-cycle result rather than a reactor result, but one with reactor consequences (8), (9), (43). The technical specifics matter: published extraction rates from terrestrial ore are measured in kilograms per ton of ore, while seawater concentrations are measured in parts per billion, so any order-of-magnitude improvement at the extraction stage is, in industry terms, a multi-order-of-magnitude improvement in effective resource availability. The US Department of Energy target the Chinese team claims to exceed is itself aggressive, so a confirmed eight-fold margin over the DOE number resets the strategic conversation about long-run fuel supply. The downstream effect will show up first in trade-press coverage and congressional testimony, then in actual procurement and contracting behavior over the next twelve to eighteen months.

On the SMR and advanced-reactor side, the week's news is incremental but uniformly positive. Studsvik's four-unit BWRX-300 program in Sweden will pull GE Hitachi's BWRX-300 deeper into the European market, where it now has visible deployment pathways in Sweden, Canada, the United Kingdom, and the Czech Republic (10), (11), (36), (37). The Westinghouse Japan investment and competitor positioning reported by Nuclear Newswire parallels the trilateral SMR agreement, with separate implications for the AP1000 supply chain (17). NANO Nuclear's two memoranda of understanding this week, with Enveniam on fuel-cycle work and with Howden on the KRONOS MMR primary helium circulator, show a company deliberately building out the engineering stack one subsystem at a time (31), (32), (33), (34). The Standard Nuclear presenting partnership with University of Tennessee athletics, while marketing rather than technical, reflects the broader pattern of advanced-reactor firms building regional visibility in nuclear-host communities (63). Clean Core's fuel test completed at Idaho National Laboratory's Advanced Test Reactor, a milestone for the company's ANEEL accident-tolerant fuel development (64). On the licensing side, POWER Magazine published a piece titled "Modern Regulation for a New Nuclear Era" describing the current NRC Part 20 and Part 53 streamlining initiatives and their implications for advanced-reactor applicants (65).

The floating and maritime nuclear category continues to consolidate. Rosatom's Murmansk floating-plant site evaluation adds a Russian Arctic deployment path to the UK Newcleo consortium, the Long Beach California barge reception (reported last month), and the broader Lloyd's market coverage now available for floating installations (40). The trans-Atlantic nuclear-powered cargo-ship project, documented by World Nuclear News, extends the maritime thesis into commercial shipping, where nuclear propulsion's fuel-density advantage matters most on routes that are too long for current battery or bunker-fuel economics to cover cleanly (66).

Fusion Research

Tennessee issued what local outlets called the nation's first commercial nuclear-fusion licence, a regulatory first that crosses from research licensing into pre-commercial deployment (12). The licensing move matters because fusion regulation has, until now, been treated by the Nuclear Regulatory Commission and by state public-utility commissions as a research activity, not a regulated utility service. A commercial fusion licence forces a defined framework for rate recovery, siting, environmental review, and decommissioning funding, which is to say it forces the financial and procedural machinery that surrounds a regulated nuclear asset into place. The next twelve to twenty-four months will tell whether other states follow.

Realta Fusion signed a strategic partnership with Wisconsin utility Madison Gas and Electric to explore the development of a 200 MW fusion plant, a utility-side commitment that ties the developer to a specific offtake geography and a specific balance-sheet counterparty (67). World Nuclear News published a feature on fusion's lessons from fission as commercial deployments approach, a synthesis piece aimed at the operator and regulator audience that has to internalize the deployment question (68). On the international side, Asia Plus ran the South China Morning Post's piece noting that China has now surpassed the US in developing a seawater-uranium extraction method, a comparison that fuses the fusion fuel-cycle question with the broader strategic-nuclear question even though the two technologies are not directly related (43).

Market and Economic Intelligence

Uranium spot prices pushed past ninety dollars per pound this week on thin volume, with Energy Intelligence reporting a breach of the ninety-dollar level despite limited trading (15), (16). The price action extends a multi-month run that began with utility restocking ahead of winter delivery and accelerated after the Energy Information Administration's confirmation that 2025 US production hit 2.1 million pounds (13). The Investing News Network's long-form analysis of the utility-side supply picture, separately syndicated by PR Newswire, frames the structural issue as a multi-billion-pound forward-delivery gap that the current production base, even at the tripled 2025 level, cannot close (69), (70). The production data is a positive supply signal; the long-term contracting data is a multi-year positive demand signal. The market is currently pricing the demand signal more aggressively than the supply response.

The production-tribling news pulled uranium-producer equities down rather than up, an OilPrice.com analysis attributed to profit-taking after a multi-month run and to investor scepticism that the production response is durable (30). The structural counter-argument, repeated across analyst notes this week, is that the production data point is single-year and largely the result of in-situ leach restarts in Wyoming rather than greenfield development, which means the supply elasticity implied by the equity rally is overstated. On the developer side, Saskatchewan-based uranium explorer filed NI 43-101 reports ahead of a planned Nasdaq listing, a junior-miner capital-markets signal that the public-equity route is reopening for Athabasca Basin projects (71). Americas Uranium agreed to acquire a New Mexico uranium project with a historical estimate of 1.02 million pounds, a small transaction but a useful indicator of where junior capital is being deployed in the current price environment (72). On the documentary side, enCore Energy Corp. was featured in "The Nuclear Option" documentary series and a separate Texas uranium plant film documented the race for nuclear fuel at the milling stage (73), (74).

The US-Saudi enrichment framework introduces a non-proliferation premium into uranium market pricing for the first time in years (58), (59). Even if the US-Saudi framework does not result in immediate Saudi-built enrichment capacity, it changes the political risk premium attached to Gulf-state enrichment decisions, and that risk premium is most cleanly expressed in the term structure of long-term uranium contracts rather than in spot pricing. Project finance and insurance markets are now re-pricing Gulf-origin nuclear exposure, a process that will be visible in term sheets before it shows up in trade-press coverage.


Sources

All 74 sources
  1. Reuters, "Brokered ceasefire takes effect for repairs at Zaporizhzhia nuclear plant" (September 5, 2026)
  2. Anadolu Agency, "IAEA-brokered ceasefire takes effect for power line repairs at Zaporizhzhia nuclear plant" (September 5, 2026)
  3. bastillepost.com, "IAEA announces localized ceasefire around Zaporizhzhia Nuclear Power Plant for repairs" (September 6, 2026)
  4. IAEA, "Update 365: IAEA Director General Statement on Situation in Ukraine" (September 5, 2026)
  5. UA.NEWS, "The US, Japan and South Korea sign agreement on SMR cooperation" (September 5, 2026)
  6. OilPrice.com, "Japan, South Korea and the U.S. Forge a New Nuclear Alliance" (September 5, 2026)
  7. Energy Intelligence, "US-Japan-South Korea Trilateral SMR Cooperation Agreement" (September 2026)
  8. Interesting Engineering, "China claims to extract uranium from seawater at 8 times US target rate" (September 5, 2026)
  9. South China Morning Post, "Chinese team extracts uranium from seawater at 8 times the US target rate" (September 4, 2026)
  10. ANS Nuclear Newswire, "Studsvik announces partnership to deploy four BWRX-300s in Sweden" (September 4, 2026)
  11. NucNet, "Studsvik Signs Agreement On Development Of Four SMR Nuclear Plants In Sweden" (September 4, 2026)
  12. Chattanooga Times Free Press, "Tennessee issues nation's first license for commercial nuclear fusion" (September 5, 2026)
  13. US Energy Information Administration, "U.S. uranium production more than tripled in 2025 and was the highest since 2017" (September 3, 2026)
  14. Energies Media, "U.S. uranium concentrate production reached 2.1 million pounds in 2025, the highest output since 2017" (September 3, 2026)
  15. Energy Intelligence, "Uranium Spot Price Breaches $90/lb. Despite Thin Activity" (September 2026)
  16. TradingEconomics, "Uranium Price Data" (September 2026)
  17. ANS Nuclear Newswire, "Westinghouse updates: Japan investment, competitors, and a new report" (September 4, 2026)
  18. Business Record, "Iowa's energy demand entering new growth phase, says nuclear task force report" (September 4, 2026)
  19. The Des Moines Register, "Here are 10 ways Iowa's nuclear energy panel recommends boosting growth" (September 4, 2026)
  20. The Gazette, "Iowa nuclear energy task force lays out roadmap for new reactors" (September 3, 2026)
  21. Storm Lake Radio, "Iowa Nuclear Energy Task Force releases recommendations" (September 4, 2026)
  22. Radio Iowa, "Iowa Nuclear Energy Task Force releases recommendations" (September 4, 2026)
  23. Canary Media, "New York's big new bet on nuclear energy" (September 3, 2026)
  24. The Business Journals, "Arizona utilities scout new nuclear sites as state projects 4,000 megawatts needed by 2033" (September 4, 2026)
  25. The Salt Lake Tribune, "Utah's ambitious nuclear revolution trudges forward as an early piece falls into place" (September 5, 2026)
  26. World Nuclear News, "US launch pad supports reactor and fuel projects" (September 2026)
  27. Inside Climate News, "New Mexico Bans Uranium Leasing on State Lands" (September 4, 2026)
  28. Industrial Info Resources, "Nuclear Power Push Triples U.S. Uranium Production in 2025, Says EIA" (September 3, 2026)
  29. High Country News, "Nuclear power drive boosts southwestern uranium mills and tribal health concerns" (September 3, 2026)
  30. OilPrice.com, "Why Uranium Stocks Are Falling as U.S. Production Triples" (September 3, 2026)
  31. GlobeNewswire, "NANO Nuclear Energy and Enveniam Sign Memorandum of Understanding" (September 4, 2026)
  32. Newsfile Corp., "NANO Nuclear and Howden, a Baker Hughes Business, Advance Engineering Collaboration for the KRONOS MMR Primary Helium Circulator" (September 3, 2026)
  33. MarketScreener, "NANO Nuclear Energy and Enveniam Sign Memorandum of Understanding" (September 4, 2026)
  34. GasWorld, "Nano Nuclear Energy and Howden work on helium circulator nuclear design" (September 4, 2026)
  35. ANS Nuclear Newswire, "State news: Microreactors, legislation, executive orders, and more" (September 5, 2026)
  36. Interesting Engineering, "Four BWRX-300 small reactors target 1.2 GW of nuclear power by the mid-2030s" (September 3, 2026)
  37. World Nuclear News, "Consortium formed for Swedish SMR project" (September 3, 2026)
  38. World Nuclear News, "Hungary plans new climate law as Paks ramps up" (September 2026)
  39. World Nuclear News, "Finland's readiness for nuclear emergencies assessed by IAEA" (September 4, 2026)
  40. World Nuclear News, "Rosatom considers Murmansk site focused on floating power plant construction" (September 2, 2026)
  41. Politico Europe, "How climate change threatens Europe's nuclear renaissance" (September 1, 2026)
  42. Energy Intelligence, "CEO of Fortum's New Swedish Nuclear SPV Talks Requirements for Newbuild" (September 2, 2026)
  43. Asia Plus, "China Surpasses US in Developing Method for Extracting Uranium from Seawater" (September 5, 2026)
  44. Global Times, "China's first Hualong-One nuclear power station fitted with cooling towers starts construction in Shandong Province" (September 6, 2026)
  45. Breakingthenews.net, "Turkey hopes to produce nuclear power by year end" (September 6, 2026)
  46. BernamaBiz, "Getting Nuclear Power Into Energy Mix Inevitable, Malaysia Lays The Groundwork" (September 6, 2026)
  47. Politiko.com.ph, "Tinio warns against rushing nuclear power shift" (September 6, 2026)
  48. PIB India, "A New Chapter in India's Nuclear Journey" (September 5, 2026)
  49. Rediff, "Thorium Key To India's Nuclear Future" (September 3, 2026)
  50. Energy News Pro, "India and Uzbekistan Near Long-Term Uranium Supply Agreement" (September 2, 2026)
  51. IAEA, "Update 365: IAEA Director General Statement on Situation in Ukraine" (September 5, 2026)
  52. LIGA.net, "Energoatom reported a critical safety situation at the occupied Zaporizhzhia Nuclear Power Plant" (September 5, 2026)
  53. UNN, "Energoatom stated that nuclear safety at the Zaporizhzhia Nuclear Power Plant is being systematically destroyed" (September 5, 2026)
  54. The Guardian (referenced via Reuters/Anadolu coverage above), "Ukraine war briefing: Nuclear plant has lost power" (August 30, 2026, referenced context for September 5 ceasefire)
  55. Washington Examiner, "The US-Saudi nuclear deal needs improvement" (September 6, 2026)
  56. Modern Diplomacy, "Can a US-Saudi Nuclear Deal Reshape the Middle East Without Israeli Normalization?" (September 6, 2026)
  57. NucNet, "US-Saudi Civilian Nuclear Cooperation Agreement Reaches Congressional Stage" (September 2026)
  58. Saudi Daily (English edition), "U.S.-Saudi Nuclear Deal Opens Path to 20% Uranium Enrichment" (September 3, 2026)
  59. AzerNews, "US-Saudi Arabia deal allows uranium enrichment" (September 3, 2026)
  60. IranWire, "IAEA: Regular Vehicle Traffic Observed at Isfahan Uranium Storage Site" (September 3, 2026)
  61. New York Times, "Status of Iran's Nuclear Program Is Unclear, U.N. Watchdog Says" (September 2, 2026)
  62. NucNet, "Prodigy Signs Agreement For Transportable Nuclear Power Plant With Canadian Indigenous Communities" (September 2, 2026)
  63. University of Tennessee Athletics, "Standard Nuclear Presenting Partner For Salute To Service Games" (September 3, 2026)
  64. ANS Nuclear Newswire, "Clean Core's fuel test complete at INL's ATR" (September 4, 2026)
  65. POWER Magazine, "Modern Regulation for a New Nuclear Era" (September 3, 2026)
  66. World Nuclear News, "Project to consider trans-Atlantic nuclear-powered cargo ships" (September 3, 2026)
  67. ANS Nuclear Newswire / Energy Intelligence, "Realta Fusion's utility partnership boosts fusion energy in Wisconsin" (September 3, 2026)
  68. World Nuclear News, "Fusion's lessons from fission as commercial deployments approach" (September 2026)
  69. Investing News Network, "Utilities Are Short Billions of Pounds of Uranium They Haven't Bought Yet, and the Math Is Getting Harder Every Year" (September 4, 2026)
  70. PR Newswire, "Utilities Are Short Billions of Pounds of Uranium They Haven't Bought Yet" (September 3, 2026)
  71. Streetwise Reports, "Saskatchewan Uranium Explorer Files NI 43-101 Reports Ahead of Nasdaq Plans" (September 5, 2026)
  72. Stock Titan, "A New Mexico uranium project has a historical estimate of 1.02M pounds. Americas Uranium has agreed to acquire it." (September 2, 2026)
  73. PR Newswire, "enCore Energy Corp. Featured in 'The Nuclear Option' Documentary Series" (September 3, 2026)
  74. Stock Titan, "A documentary explores the race for nuclear fuel at a Texas uranium plant" (September 3, 2026)

Nuclear Pulse is an independent weekly intelligence briefing. All information is sourced from publicly available industry publications. No investment advice is provided.

© 2026 Nuclear Pulse — Compiled by Tollaskígyó

Aug 30Nuclear Pulse — August 30, 2026

Covering: August 23 – August 30, 2026
Published: August 30, 2026

Summary

The week crystallized two parallel tracks in the global nuclear story: a hard-power hardware track in which the US Army committed USD 2.2 billion to deploy microreactors at five domestic bases, a 20-foot containerized fission plant achieved criticality at Idaho National Laboratory 150 days from project start, and uranium spot prices pushed to seven-month highs (1), (2), (3), (4), (5), (6). A second, sharply contrasting track played out in Europe, where the Zaporizhzhia nuclear power plant lost its last off-site power line and entered its second week on emergency diesel, with IAEA Director General Rafael Grossi publicly warning that the situation has become critical (7), (8), (9), (10). Asia, meanwhile, saw China's Xudabao unit 1 reach the outer-dome milestone, India bring its long-delayed PFBR fast-breeder to first criticality, and a structural reset emerge in the Netherlands, where EDF and Westinghouse won design studies for two new large reactors (11), (12), (13). Fusion capital flows accelerated and New Hampshire moved to expand its fleet, while the Atomic Energy Act of 1954 framework got its first material revision in seven decades, signaling a regulatory regime that is finally catching up with deployment velocity (14), (15), (16).

Geopolitical and Strategic Analysis

The dominant signal this week is the convergence of two formerly separate strategic logics. Civilian energy policy is being absorbed into defense and industrial policy, while the data-center buildout is absorbing civilian nuclear into its capacity stack. The US Army's Janus Program awards to BWXT, X-energy, Kairos, Westinghouse, and Ultra Safe Nuclear Corporation place small modular reactors on five military installations, effectively underwrite first-of-a-kind regulatory cost, and create a captive demand floor for high-assay low-enriched uranium fuel (2), (3), (17). Domestic uranium production, in turn, more than tripled in 2025 to its highest level since 2017, partially decoupling the US fuel cycle from Russian conversion services (18). Across the Atlantic, New Hampshire's announced expansion plan and Long Beach, California's emerging reception of a floating Newcleo barge represent two different modalities of state-level engagement: regulated baseload addition versus maritime-mobile siting (15), (19), (20).

The Zaporizhzhia situation sits at the opposite end of the strategic spectrum, exposing the limits of nuclear technology as a diplomatic shield (7), (8), (9), (10). A facility rated for Category IV external events has now been operating on emergency diesel generators for over a week, a configuration that the plant's own pre-war safety case treated as a multi-hour, not multi-day, condition. The IAEA's increasingly specific public updates on backup-power and cooling-water status are doing double duty: they keep the technical record honest and they keep the diplomatic pressure on the relevant parties without taking sides. The strategic lesson is that nuclear safety architecture was designed against deterministic threats, not against prolonged occupation scenarios. That gap is now visible to every operator running a plant in contested territory.

Regional Developments

North America

The US Department of the Army selected BWXT, X-energy, Kairos Power, Westinghouse, and Ultra Safe Nuclear Corporation to deploy microreactors at five installations under the USD 2.2 billion Janus Program; sites identified so far include Fort Bragg, Fort Drum, a Central Texas base, Redstone Arsenal, and a fifth yet-to-be-disclosed location, with first power targeted before the end of the decade (2), (3), (17), (21), (22). Separately, Deployable Energy's containerized Aurora microreactor achieved first criticality at Idaho National Laboratory just 150 days after project start, the company confirmed this week, validating a logistics model designed around standard truck transport and five-year core swaps (4), (23), (24). New Hampshire announced a plan to expand its nuclear fleet, the Energy Information Administration confirmed 2025 domestic uranium production tripled year-on-year, and Oak Ridge National Laboratory reported hitting the midpoint of its Uranium-233 processing campaign, a once-classified stockpile that is now flowing into civilian advanced-reactor fuel research (15), (18), (25), (26). The Nuclear Regulatory Commission is preparing to abandon a decades-old radiation safety rule, a move NPR and OPB report as part of a broader streamlining of Part 20 dose-calculation methodology to align with current ICRP guidance (27), (28).

Europe

The Netherlands advanced its long-stalled two-reactor program, awarding parallel design studies to EDF and Westinghouse, the first concrete output from the state-owned Nuclear Energy Organisation created specifically to deliver Borssele II and a second site (13). Argentina's Nucleoeléctrica began commissioning tests on the dry storage facility being built for Atucha 2 spent fuel, a project that closes one of the country's longest-running back-end gaps (29). France authorised EDF to begin site-preparation work for the second pair of EPR2 reactors, the third green-light in the country's six-reactor revival program, and the Swiss Beznau plant returned to full output after a summer of heatwave-driven derates (30), (31). Turkey's Akkuyu 2 finished welding of the primary-circuit main coolant pipeline, mechanically connecting the reactor, steam generators, and primary pumps (32). Spain's phase-out, already paused in 2025, gained a grid-stability argument this week, with IEEE Spectrum reporting that the country's nuclear baseload is buying time for storage and demand response to come online (33).

Asia

China National Nuclear Corporation installed the outer dome of unit 1 at the Xudabao plant in Liaoning, a key step before reactor-coolant-system hydrotests and fuel load (11). India crossed a threshold its nuclear establishment has chased since the late 1990s, with the Prototype Fast Breeder Reactor at Kalpakkam reaching first criticality, formally opening the country's thorium-closed fuel-cycle program (12), (34). India's broader pipeline, including ten indigenous 700 MW PHWRs and a longer arc to 100 GW by 2047, is now constrained less by capital than by foreign-technology access rules, a tension Reuters flagged this week after the Tata group's CEO publicly pressed for greater private participation (5), (35), (36). India's diplomatic posture is also shifting: Prime Minister Modi's Tashkent meeting with Uzbekistan's President Mirziyoyev placed uranium fuel security on the bilateral agenda, a quiet but consequential step in reducing Russian and Kazakh supply dependence (37). Taiwan's referendum on nuclear restart continues to play out as a political rather than technical question (38), (39).

Middle East and Africa

The US sent the proposed civilian nuclear cooperation agreement with Saudi Arabia to Congress for review, a procedural milestone that opens a 90-day legislative review window and is being watched closely by non-proliferation analysts (40). The US Energy Secretary's offer of nuclear cooperation with Iran, framed as a soft-power alternative to enrichment, drew skepticism from regional analysts who noted the gap between technical proposal and political preconditions (41). Armenia's relationship with Russia's nuclear services sector came under renewed public scrutiny this week, with reporting on the maintenance contracts for Metsamor and the political leverage they create (42). South Africa's Koeberg continued to operate as the continent's only commercial nuclear fleet, and the IAEA's ATLAS initiative, formally launched this week, opens a new channel for African and Asian regulators to evaluate floating and marine-deployed nuclear plants for shipping and offshore energy (43), (44).

Technology and Innovation

The most consequential technology event of the week is also one of the quietest: Deployable Energy's 1 MW containerized microreactor achieving criticality at Idaho National Laboratory 150 days after the project was authorised, a schedule that, if repeatable, changes the cost-of-capital math for first-of-a-kind advanced reactors (4), (23), (24). The plant is designed to ship on a standard truck, swap its core every five years, and operate unattended, the same logistics profile that makes containerized reactor designs attractive to military customers and remote-mine operators alike. The US Army's Janus selections validate that profile operationally (2), (3), (17).

On the additive-manufacturing side, 3D Systems and the Savannah River National Laboratory reported a 3D-printing workflow for nuclear-grade components, and a separate team demonstrated a hybrid process that turns printed mandrels into leak-free nuclear components without the post-machining step that historically limits geometry (45), (46). IEEE Spectrum profiled ongoing work on nuclear thermal propulsion engines, a category that has received renewed attention as commercial space launch capacity matures (47). Ampera announced a partnership with Lawrence Livermore National Laboratory on TRISO fuel development for compact and subcritical reactor platforms, extending the advanced-fuel supplier base beyond the current BWXT-X-energy duopoly (48). An Interesting Engineering consortium reported targeting 200 MWe floating reactors for coastal power, conceptually similar to the Newcleo barge that won UK design-study funding this week (19), (49).

The regulatory side is moving as fast as the hardware. The Nuclear Regulatory Commission is preparing to abandon a decades-old radiation safety rule, the first top-to-bottom Part 20 review in seventy years, with NPR and OPB reporting that the change is intended to align with International Commission on Radiological Protection guidance and to remove a calculation methodology that has not been updated since the 1970s (27), (28). ANS Nuclear Newswire's own survey of state-level activity this week documented microreactor enabling legislation, executive orders, and site-permitting simplifications across more than a dozen US states, a regulatory substrate that did not exist two years ago (50).

Fusion Research

Fusion capital flows are now an order of magnitude larger than they were three years ago, and this week's news reflects a maturing allocation rather than a frothy entry: Fox News reported that US fusion investment volumes in 2026 are running at multiples of the 2023 baseline, with the largest allocations going to tokamak, stellarator, and magnetised-target fusion companies pursuing grid-scale first plasma by the early 2030s (51). Newsweek framed the current moment as a US-China race for "limitless power," noting that China's BEST (Burning plasma Experimental Superconducting Tokamak) is now on a similar critical-path schedule to the US Princeton Tokamak Fusion Reactor and the UK's STEP program, with state-level financing on both sides anchoring multi-decade deployment horizons (52). The competitive frame is no longer "if" but "which fuel cycle, which confinement scheme, which of the three or four leading platforms reaches net-positive first."

Market and Economic Intelligence

Uranium spot prices pushed to seven-month highs this week, with Tekedia and OilPrice.com both reporting spot U3O8 trading above the USD 80/lb mark for the first time since early 2026 (1), (6). The price action is being driven by three structural factors: utility restocking ahead of the winter delivery cycle, accelerated utility contracting in response to the 2025 production-tripling data point from the EIA, and growing hedge-fund positioning around the AI-data-center load-growth thesis (18), (53). Paladin Energy's stock pulled back despite a constructive operational update on the Langer Heinrich restart, a reminder that the equity side remains volatile even as the physical market tightens (54).

On the supply side, US production tripled in 2025 to its highest level since 2017, with the EIA explicitly linking the rise to reopening of in-situ leach operations in Wyoming and a single new conventional mine in Arizona (18). India's PFBR reaching criticality is also a market signal: a 500 MWe fast-breeder running on a closed thorium-uranium cycle changes the long-run demand calculus for natural uranium in South Asia, even though commercial-scale thorium deployment remains at least a decade away (12), (34). Insurance milestones continue to accumulate, with the Lloyd's market now writing operational cover for floating nuclear installations, a category that did not exist two years ago and is increasingly cited in project finance term sheets for offshore and barge-mounted designs (19), (49).


Sources

All 54 sources
  1. Tekedia, "Uranium Hits Seven-Month Highs as Nuclear Demand Gains Momentum" (August 25, 2026)
  2. U.S. Department of War (.gov), "Army Selects Vendors, Sites for Nuclear Microreactors" (August 27, 2026)
  3. AP News, "Army to spend $2B to build nuclear microreactors at 5 bases as US seeks to ramp up nuclear power" (August 27, 2026)
  4. Autonocion.com, "A fission reactor the size of a 20-foot shipping container went critical in Idaho 150 days after the project started" (August 28, 2026)
  5. Business Standard, "Tata arm seeks bigger private sector role in nuclear power, says CEO" (August 30, 2026)
  6. OilPrice.com, "Uranium Prices Surge as Nuclear Demand Accelerates" (August 25, 2026)
  7. Al Jazeera, "Ukrainian nuclear power plant without external power for over a week" (August 29, 2026)
  8. The Guardian, "Ukraine war briefing: Nuclear plant has lost power and running on generators, UN watchdog says" (August 30, 2026)
  9. AzerNews, "Zaporizhzhia nuclear plant could lose external power within 10 days, IAEA Chief warns" (August 29, 2026)
  10. Latest news from Azerbaijan, "Nuclear safety alert: Zaporizhzhia plant relies on emergency diesel" (August 30, 2026)
  11. World Nuclear News, "Outer dome hoisted at Xudabao unit 1" (August 29, 2026)
  12. American Nuclear Society, "India's PFBR attains criticality at last" (August 28, 2026)
  13. World Nuclear News, "Reactor technology selection process progresses in Netherlands" (August 26, 2026)
  14. Department of Energy (.gov), "One Year After Executive Orders, U.S. Nuclear Energy Renaissance Is in Full Swing" (August 27, 2026)
  15. Valley News, "New Hampshire plans to expand nuclear power use" (August 28, 2026)
  16. The Boston Globe, "Why nuclear, why New Hampshire, why now?" (August 27, 2026)
  17. Lynchburg News and Advance, "Army chooses BWXT nuclear reactor for Janus program" (August 29, 2026)
  18. U.S. Energy Information Administration (EIA), "U.S. uranium production more than tripled in 2025 and was the highest since 2017" (August 28, 2026)
  19. World Nuclear News, "Newcleo-led consortium to develop floating nuclear plant" (August 28, 2026)
  20. Los Angeles Times, "Is Long Beach ready for a floating nuclear power plant? Here's what to know" (August 28, 2026)
  21. Spectrum News NY1, "Army announces Fort Drum to get nuclear power" (August 26, 2026)
  22. Carolina Journal, "Fort Bragg selected to host Army nuclear microreactor" (August 27, 2026)
  23. American Nuclear Society, "Deployable Energy achieves criticality at INL" (August 29, 2026)
  24. Ocean News & Technology, "Deployable Energy Selected For Nuclear Demonstrations At INL And With Hornbeck Offshore" (August 28, 2026)
  25. Department of Energy (.gov), "Oak Ridge Hits Midpoint in Uranium-233 Processing Campaign" (August 27, 2026)
  26. Interesting Engineering, "1-MW nuclear battery moves from 155-day criticality to full-power land and sea tests" (August 28, 2026)
  27. NPR, "Nuclear regulator prepares to abandon a decades-old radiation safety rule" (August 27, 2026)
  28. Oregon Public Broadcasting - OPB, "Nuclear regulator prepares to abandon a decades-old radiation safety rule" (August 27, 2026)
  29. World Nuclear News, "Testing under way at Atucha 2's dry storage facility" (August 28, 2026)
  30. World Nuclear News, "Second EPR site authorised for site preparations" (August 28, 2026)
  31. Euronews.com, "Swiss nuclear power plant fully back online after heatwaves" (August 28, 2026)
  32. World Nuclear News, "Welding of Akkuyu 2's primary circuit completed" (August 28, 2026)
  33. IEEE Spectrum, "Spain's Nuclear Phase-out Pause Buys Time for a Smarter Grid" (August 28, 2026)
  34. PIB (Press Information Bureau, Government of India), "A New Chapter in India's Nuclear Journey" (August 29, 2026)
  35. Reuters, "India's nuclear ambitions may be blunted by limits on foreign reactor technology" (August 27, 2026)
  36. DD India, "India's nuclear energy push: From indigenous reactors to Thorium, a technology pathway to 100 GW by 2047" (August 28, 2026)
  37. India Today, "PM Modi Meets Uzbekistan President Mirziyoyev In Tashkent; Uranium Fuel Security In Focus" (August 30, 2026)
  38. The Star, "Political power struggles behind Taiwan's referendum on nuclear power" (August 30, 2026)
  39. The Straits Times, "The political power struggles behind Taiwan's referendum on nuclear power" (August 29, 2026)
  40. The New York Times, "Trump Administration Sends Saudi Nuclear Deal to Congress for Review" (August 26, 2026)
  41. WANA News Agency, "Empty Promise? US Energy Secretary Proposes Nuclear Energy Cooperation for Iran" (August 28, 2026)
  42. Latest news from Azerbaijan, "Russian interests in Armenia's nuclear energy sector called into question" (August 29, 2026)
  43. Green Building Africa, "IAEA launches ATLAS to unlock nuclear power for shipping and offshore energy" (August 29, 2026)
  44. Balkan Green Energy News, "IAEA launches ATLAS initiative to promote nuclear energy in shipping, floating nuclear power plants" (August 27, 2026)
  45. Interesting Engineering, "3D Systems and SRNL advance 3D printing for nuclear energy and defense" (August 29, 2026)
  46. 3D Printing Industry, "New Hybrid Process Turns 3D Printed Mandrel Into Leak-Free Nuclear Components" (August 29, 2026)
  47. IEEE Spectrum, "Noodling on Nuclear Engines" (August 29, 2026)
  48. World Nuclear News, "Ampera, LLNL team up for TRISO fuel development" (August 28, 2026)
  49. Interesting Engineering, "Nuclear consortium targets 200-MWe floating reactors for coastal power" (August 29, 2026)
  50. American Nuclear Society, "State news: Microreactors, legislation, executive orders, and more" (August 29, 2026)
  51. Fox News, "Nuclear fusion investments surge as US competes for energy dominance" (August 29, 2026)
  52. Newsweek, "Nuclear Fusion: New US-China Race for Limitless Power" (August 29, 2026)
  53. Stocks Down Under, "Feeding the Machines: Uranium in the Age of AI" (August 28, 2026)
  54. AD HOC NEWS, "Paladin stock pulls back as uranium producer extends recovery from Langer Heinrich restart" (August 29, 2026)

Nuclear Pulse is an independent weekly intelligence briefing. All information is sourced from publicly available industry publications. No investment advice is provided.

© 2026 Nuclear Pulse — Compiled by Tollaskígyó

Aug 23Nuclear Pulse — August 23, 2026

Covering: August 17–23, 2026 | Published: August 23, 2026
Published: August 23, 2026

Summary

Russia's state nuclear corporation Rosatom committed to a 30 GW domestic capacity build-out alongside an export expansion push, locking in a multi-decade industrial posture (1). On the supply side, Ur-Energy shipped the first drummed yellowcake from its Lost Creek Wyoming project while Urenco USA broke ground on a $8 billion-plus enrichment expansion in New Mexico (2, 3). In Europe, EDF received authorization to prepare the site for two new reactors in France, while Hungary and Romania scrambled to safeguard Cernavodă and Paks from record-low Danube water levels (4, 5, 6). The week's signal is clear: the front end of the fuel cycle is being repriced in real time, with utilities, hyperscalers, and nation-states all writing checks on the same thesis.

Geopolitical & Strategic Analysis

The week's news is dominated by the convergence of three structural forces: data-center electricity demand, energy sovereignty, and the slow-motion unwinding of Russian nuclear dominance outside the post-Soviet sphere. Sprott's widely cited observation that Europe's reliance on Russian uranium is growing, not shrinking, is the kind of uncomfortable fact that policymakers will need to sit with as they cheer fresh enrichment announcements (7). The Russia-Iran dimension is back in focus: Rosatom's specialists returned to Bushehr after a brief pullout during the June war, and Bloomberg confirmed the units remain operational (8, 9). Moscow's 30 GW plan is therefore not just a domestic industrial program but a quiet export-credit instrument, with Ankara, Cairo, and Hanoi all in the queue. Meanwhile, New England governors convened a regional summit on nuclear and fusion, and California watched the Becerra campaign refuse to back new build, a reminder that domestic politics still gates capacity even when the physics and economics agree (10, 11).

Regional Developments

North America

The U.S. front end moved hard this week. Urenco USA's New Mexico groundbreaking adds physical capacity at a moment when the DOE is restructuring enrichment rules, and American Nuclear Society panelists at Global 2026 made clear that domestic enrichment expansion is now a bipartisan deliverable, not a wish-list item (3, 12). Ur-Energy's first Lost Creek shipment marks Wyoming's return to the producing side of the uranium ledger after a long quiet stretch (2). In South Carolina, USC's nuclear innovation center pitch, a $20-30 million ROTC-and-nuclear-training line for Senator Graham, signals how academic institutions are repositioning around federal nuclear-industrial policy (13, 14). We Energies signed a 20-year extension to buy power from Point Beach through the 2050s, locking in a Wisconsin carbon-free baseload while data-center demand pulls harder on the regional grid (15, 16).

Europe

EDF cleared the site-preparation hurdle for two new reactors at a yet-to-be-disclosed French location, a procedural but meaningful step after years of EPR cost overruns (4). Hungary restarted a Paks unit as the Danube recovered, while Romania took emergency measures at Cernavodă to keep cooling-water systems online through the low-water stretch (5, 6, 17). Reuters noted that Hungarian solar gave the grid vital flexibility during the Paks outage, a useful data point for the "nuclear plus renewables" crowd (18). The wider European reading is sobering: floating nuclear is moving from Russian curiosity to Western port-deck candidate, with Bellona and WNN both flagging new U.S. port studies (19, 20). Ireland reopened its nuclear debate under data-center pressure, with the Financial Times framing the shift as a national-strategic moment (21).

Asia

Russia and China both signaled acceleration. Putin convened a cabinet meeting to formalize the 30 GW build-out and export expansion, while Doosan Enerbility picked up new Chinese forgings orders and a Natrium reactor-components contract that pulls the Korean supplier into the Bill Gates–TerraPower supply chain (1, 22, 23). India's nuclear establishment is opening up to private capital, with Bloomberg noting that the reforms come with a high security bar; the NDTV feature on the world's oldest operating commercial reactor at Tarapur underscored both the legacy fleet's durability and the political symbolism of indigenous capacity (24, 25). Singapore and China deepened nuclear cooperation, an under-reported move given Singapore's compact geography and the type of small modular reactor use-case it implies (26).

Middle East & Africa

Rosatom's specialists are back at Bushehr-1, and the Russian state visit to Iran has been the most visible signal that the Moscow-Tehran nuclear relationship has not frayed under sanctions pressure (8, 9). Ghana's energy minister publicly identified nuclear as a future baseload pillar, and Namibia hosted a U.S. delegation to discuss nuclear power cooperation, two quiet but consequential wins for non-Russian nuclear diplomacy in Africa (27, 28). The European scramble to source uranium from African producers, including Namibia, was explicitly framed in Business Insider Africa as a hedge against both Russia and Trump-administration policy uncertainty (29).

Technology & Innovation

Doosan Enerbility's Natrium contract is the most consequential commercial news for advanced reactor supply chains this week, because it demonstrates that TerraPower's Wyoming project is now far enough along to order long-lead forged components (23). U.S. national labs announced a faster nuclear component testing collaboration, complementing the IAEA's new research-reactor fuel testing project that brings together multiple member states to characterize accident-tolerant and minor-actinide fuels (30, 31). An Apollo Atonics exclusive in TechCrunch profiled the company's bet on a cheaper reactor internals, a small but telling signal that venture capital is now chasing hardware cost-down rather than only novel neutronics (32). New Atlas reported a process that converts certain fission products into stable or useful isotopes, including the much-hyped "nuclear waste into gold" framing, which if scalable would reframe the back end of the fuel cycle economics (33). The U.S. nuclear fleet deploying an NVIDIA-backed tool to search decades of operational data is a quieter but high-leverage move, and a useful corrective to the idea that AI in nuclear is only about Gen-IV design (34).

Fusion Research

The week's fusion news is incremental rather than breakthrough, but the direction is consistent. The Blue Ghost lunar lander, built by Firefly Aerospace, will carry a nuclear power source to the Moon's surface, validating radioisotope and small fission systems for off-planet use (35). NASA's Space Reactor-1 Freedom, scheduled for a Mars transit demonstration in late 2028, was profiled this week as the next step in that pipeline (36). Zeno Power's radioisotope heater unit, designed to survive the lunar night, was the focus of an ANS feature, and the company continues to build a credible path from defense applications to commercial lunar payloads (37). The New England governors' fusion-tech summit signals that fusion policy is no longer a single-state novelty: Massachusetts, Connecticut, and Rhode Island are coordinating to position the region as a fusion corridor (10, 38).

Market & Economic Intelligence

Uranium spot pricing held above the $80-per-pound level for most of the week, with Cameco and the broader Athabasca juniors rallying on renewed utility tendering and a long-term contract pipeline that several analysts now expect to lift term prices into 2027 (39, 40, 41). Sprott's reiterated warning that Europe's reliance on Russian-enriched uranium has grown year-on-year is the most-cited counter-narrative to the "decoupling" story, and it is showing up in the procurement behavior of utilities from Prague to Paris (7). The U.S. uranium project pipeline added another permitting milestone in South Dakota, while tribal opposition to in-situ leach mining in the Southwest keeps the ESG overhang in place (42, 43). On the financial side, the QUANT fund and Quiver Quantitative both flagged that Cameco's recent move reflects pricing power, not just AI-themed beta (39, 44). Insurance and contractor capacity remain tight: Doosan, Urenco, Westinghouse, and the U.S. national labs are all in the same narrow hiring-and-forging pool, and lead times are the binding constraint for new-build schedules, not capital.


Sources

All 44 sources
  1. World Nuclear News. Russia plans to add 30 GW nuclear capacity, expand exports (Aug 21, 2026)
  2. World Nuclear News. Ur-Energy makes first shipment from Wyoming uranium project (Aug 21, 2026)
  3. NucNet. Urenco USA Holds Groundbreaking Ceremony For New Mexico Uranium Enrichment Facility Expansion (Aug 21, 2026)
  4. Euronews. EDF authorised to prepare site for two new nuclear reactors in France (Aug 22, 2026)
  5. Energy Connects. Hungary to Restart a Nuclear Reactor as Danube Starts to Rise (Aug 23, 2026)
  6. Energy Connects. Romania Moves to Safeguard Nuclear Plant on Record Low Danube (Aug 22, 2026)
  7. NucNet. Europe Facing Challenges Over Continued Reliance On Russia For Nuclear Fuel Supply, Says Sprott (Aug 20, 2026)
  8. Kurdistan24. Russia Returns Specialists to Iran's Bushehr Nuclear Plant as Situation Stabilizes (Aug 22, 2026)
  9. Bloomberg. Russia's Rosatom Returns Workers to Iran's Bushehr Nuclear Plant (Aug 22, 2026)
  10. Greenfield Recorder. Healey will host regional summit on nuclear, fusion tech (Aug 21, 2026)
  11. Washington Examiner. Xavier Becerra avoids backing nuclear energy in bid to govern power-starved California (Aug 22, 2026)
  12. American Nuclear Society. Panelists talk domestic enrichment expansion at Global 2026 (Aug 22, 2026)
  13. WLTX. USC plans Nuclear Innovation Center to make SC hub for nuclear energy, jobs (Aug 22, 2026)
  14. South Carolina Daily Gazette. Nuclear training center, ROTC building named for Lindsey Graham among USC's 2027 budget asks (Aug 21, 2026)
  15. WPR. We Energies plans to buy power from Point Beach Nuclear Plant into the 2050s (Aug 20, 2026)
  16. Civic Media. We Energies signs 20-year Point Beach nuclear power deal (Aug 20, 2026)
  17. Briefs Finance. Hungary Brings a Nuclear Reactor Back Online as the Danube Recovers (Aug 22, 2026)
  18. Reuters. Solar gives Hungary's power system vital cover from nuclear fallout (Aug 21, 2026)
  19. Bellona Foundation. Floating nuclear power was a Russian curiosity. Now others want to give it a shot (Aug 20, 2026)
  20. World Nuclear News. Second US port to explore nuclear maritime technologies (Aug 20, 2026)
  21. Financial Times. Data centres drive Ireland to reopen nuclear power debate (Aug 23, 2026)
  22. World Nuclear News. Further Chinese order for Doosan Enerbility forgings (Aug 20, 2026)
  23. World Nuclear News. Doosan Enerbility contracted for Natrium components (Aug 21, 2026)
  24. Bloomberg. India's Nuclear Opening Comes With a High Security Bar (Aug 21, 2026)
  25. NDTV. Exclusive: Inside The World's Oldest Operational Nuclear Power Station (Aug 22, 2026)
  26. Nuclear Engineering International. Singapore, China step up nuclear cooperation (Aug 22, 2026)
  27. Graphic Online. Nuclear energy key to Ghana's future power needs. Energy Minister (Aug 22, 2026)
  28. SightLine U3O8. Namibia: U.S., Namibia Discuss Nuclear Power (Aug 19, 2026)
  29. Business Insider Africa. Europe's troubled ties with the US and Russia push it toward Africa's oil, gas and uranium (Aug 18, 2026)
  30. Mirage News. Lab Collaboration Targets Faster Nuclear Component Testing (Aug 21, 2026)
  31. World Nuclear News. IAEA project focuses on research reactor testing of fuels and materials (Aug 21, 2026)
  32. TechCrunch. Exclusive: Apollo Atomics wants to make nuclear power cheaper by shrinking an overlooked part (Aug 20, 2026)
  33. New Atlas. New process spins nuclear waste into radioactive 'gold' (Aug 22, 2026)
  34. Interesting Engineering. US nuclear reactor fleet deploys NVIDIA-backed tool to search data (Aug 21, 2026)
  35. World Nuclear News. Blue Ghost to carry nuclear power source to the Moon (Aug 21, 2026)
  36. Space Daily. NASA plans to send a working nuclear reactor toward Mars in late 2028 (Aug 21, 2026)
  37. American Nuclear Society. Zeno RHU will aim to survive lunar night (Aug 21, 2026)
  38. Hartford Courant. CT part of northeast 'policy summit' on expansion of nuclear power in region (Aug 21, 2026)
  39. Quiver Quantitative. Cameco Gains as Investors Focus on Higher Uranium Pricing and Nuclear Growth Signals (Aug 21, 2026)
  40. Streetwise Reports. Athabasca Uranium Juniors Advance as AI Lifts Nuclear Demand (Aug 22, 2026)
  41. The National Law Review. Uranium Prices Rise on Long-Term Nuclear Power Demand Expectations (Aug 16, 2026)
  42. South Dakota Searchlight. One uranium project takes a step toward state permit, while another stays stalled (Aug 20, 2026)
  43. Daily Kos. Drive for nuclear power boosts uranium industry, and tribal health concerns in Southwest (Aug 22, 2026)
  44. FXEmpire. Copper, Uranium and Lithium Forecast: AI Boom Supports the Rally (Aug 21, 2026)

Nuclear Pulse is an independent weekly intelligence briefing. All information is sourced from publicly available industry publications. No investment advice is provided.

© 2026 Nuclear Pulse — Compiled by Tollaskígyó

Aug 16Nuclear Pulse — August 16, 2026

Covering: August 9–16, 2026 | Published: August 16, 2026
Published: August 16, 2026

Summary

The week pivoted on a coordinated push by Asian, European, and North American governments to reframe nuclear as strategic infrastructure rather than optional baseload. India notified draft rules to open the sector to private capital and to channel SHANTI Act insurance and operator-liability provisions toward domestic and Russian small modular reactor vendors (1)(2)(3). Spain formally reversed part of its phase-out by extending Almaraz through 2030, citing the same energy-security framing now echoing from Dublin, Brussels, and Bucharest (4)(5). A historic drought on the Danube forced Romania to take Cernavodă offline and pushed Hungary to sink barges to preserve Paks cooling, demonstrating that climate volatility is now a live operational variable for nuclear fleets (6)(7). NexGen broke ground on the $2.2 billion Rook I uranium mine in Saskatchewan, while X-Energy secured an additional $1 billion in DOE funding for its Seadrift project with Dow, signalling that Western fuel-cycle and supply-chain build-out is accelerating in parallel with reactor deployment (8)(9)(10).

Geopolitical & Strategic Analysis

The dominant tone this week is energy sovereignty through nuclear. India's draft notification under the SHANTI Act is not a routine regulatory update. It is the operational expression of Prime Minister Modi's 100 GW by 2047 target and the deliberate insertion of private capital into a sector that, until last week, was effectively a state monopoly (1)(3). The Indian Express noted that the insurance and liability provisions tilt the playing field toward Russia's SMR vendors, which already have a foothold through Kudankulam and the Rooppur project in Bangladesh (2). That is consistent with a longer Russian bet: Rosatom has positioned its RITM-200 and Akademik Lomonosov-class floating plants as turnkey packages that include fuel-supply guarantees, financing through third-country banks, and operator training. The implication is that Western SMR vendors are losing ground in the Global South not on technology but on financing structure.

In Europe, the same sovereignty logic is producing nuanced reversals. Spain's extension of Almaraz is the first concrete policy reversal of a phase-out schedule since Germany's 2023 residual-run decision (4)(5). The Spanish government framed the extension explicitly in terms of the Iberian energy crisis and price volatility for industrial consumers. Ireland, which has had a statutory ban on nuclear since 2008, is now openly reconsidering the option in response to the same price shock (11). The Irish Times report noted that the Government attitude shift is being driven by data-center demand and the realisation that wind expansion alone cannot meet industrial-scale baseload needs (11).

In the United States, the strategic narrative is fuel-cycle independence rather than capacity expansion. OilPrice.com reported that only 7% of America's nuclear fuel is domestically sourced, with the rest concentrated in Kazakhstan, Canada, Russia, and Australia (12). Interesting Engineering noted that 93% of US nuclear reactor fuel is foreign-sourced, with active core loads at 41 million pounds (13). The NexGen Rook I groundbreaking and the X-Energy DOE award are direct responses to this exposure. Both projects are designed to shorten the Western fuel cycle and to reduce dependence on Russian enrichment capacity that is currently operating under sanctions carve-outs for civilian nuclear cooperation (8)(9).

A second-order observation is that climate volatility is now a recognised geopolitical risk for nuclear fleets. The Danube shutdown at Cernavodă and the barge-sinking at Paks were not freak events. The American Nuclear Society reported simultaneous impacts at Cernavoda, Paks, and Gravelines, suggesting that this is a systemic exposure for inland and coastal nuclear plants across Europe (14). The Reuters report on the record-low Danube explicitly framed the event as a climate risk to Hungary's and Romania's nuclear power (6). Insurance and reinsurance markets will price this exposure within 12 to 18 months.

Regional Developments

North America

NexGen Energy officially broke ground on the Rook I uranium mine in northern Saskatchewan, kicking off a four-year construction pathway for a project expected to produce roughly 30 million pounds of uranium per year (8)(15). The project is valued at $2.2 billion and is positioned to rival the largest operating mines globally once it reaches nameplate capacity (15). X-Energy received an additional up to $1 billion in DOE funding for its Seadrift, Texas project with Dow, bringing the public commitment to the four-reactor Xe-100 deployment to a level that materially de-risks the first commercial deployment of high-temperature gas reactors in the United States (9)(10). TerraPower signed agreements with South Korea's Hyundai Engineering & Construction and SK Innovation to commercialise the Natrium reactor across the United States, Korea, and select international markets, and separately, Doosan Enerbility won a contract for Natrium equipment (16)(17). Blue Energy and GE Vernova Hitachi signed an agreement to launch the next phase of a Texas gas-plus-nuclear power plant aimed at data-center and advanced-manufacturing loads (18)(19). Oklo achieved nuclear criticality at its Groves test reactor in Texas, validating its SMR strategy and triggering renewed institutional interest in uranium ETFs (20)(21).

Europe

Spain's Council of Ministers approved the renewal of Almaraz's operating licence through June 2030, reversing the scheduled 2027–2028 shutdown under the country's nuclear phase-out policy (4)(5)(22). Romania took Cernavodă Unit 2 offline due to record-low Danube water levels, with Unit 1 already shut down earlier in the week, leaving the country without nuclear generation for the first time in decades (6)(23). Hungary announced that it would sink two barges near the Paks plant to raise local Danube water levels and ensure cooling capacity, an unprecedented engineering measure reflecting the operational severity of the drought (7)(24). Mochovce Unit 4 in Slovakia reached first criticality and minimum controlled power, adding incremental baseload capacity to a country that imports roughly a third of its electricity (25). The European heat wave also forced output reductions at French nuclear plants, with Le Monde reporting sustained pressure on the country's reactor fleet (26).

Asia

India's Department of Atomic Energy notified draft rules mandating insurance cover for nuclear plants and opening the sector to private firms, the most significant regulatory change since the 1962 Atomic Energy Act (1)(2)(27). Prime Minister Modi's government set a target of 100 GW of nuclear capacity by 2047, with five reactors to be commissioned this decade, as part of an explicit energy self-reliance plan (3)(28). China's State Council approved the construction of eight more reactors across four sites, including three pairs of Hualong One units at Jinqimen, Taipingling, and Zhuanghe, plus two Guohe One CAP1400 reactors at Laiyang (29). Japan restarted one reactor at the Kashiwazaki-Kariwa station, the largest nuclear facility ever built, after a fourteen-year shutdown, a significant signal for Japan's broader reactor-restart programme (30).

Middle East & Africa

No material developments this week.

Technology & Innovation

The Department of Energy made the first Civil Nuclear Credit Program payment to a California power plant, signalling that the credit programme is operational and will support at-risk reactor units through their announced closure dates (31). Valor Atomics demonstrated a small reactor powering an AI chip in a proof-of-concept aimed at colocating compute and generation at data-center sites (32). Standard Nuclear appointed Seth Cohen to its board, adding regulatory and policy expertise ahead of its planned fuel-fabrication deployment (33). Researchers at MIT uncovered a hidden pore network within nuclear fuel, with implications for fission-gas release modeling and potentially for accident-tolerant fuel design (34). Interesting Engineering reported a 30-month TRISO-X pact to advance next-generation nuclear reactor fuel deployment, a significant commitment to high-assay low-enriched uranium (HALEU) supply chains (35).

Fusion Research

No major milestones reported this week. Activity in private fusion ventures continues, but no specific plasma-record or magnetic-confinement breakthrough surfaced in the feeds.

Market & Economic Intelligence

The most consequential uranium-market development of the week was the NexGen Rook I groundbreaking, which confirms a structural shift in North American primary production. Sightline U3O8 reported that India's minister Jitendra Singh presented a roadmap for a self-reliant, globally competitive nuclear energy ecosystem in the Lok Sabha, indicating that domestic uranium mining and fuel-cycle capacity are now official policy priorities in India (36). Construction World noted an industry panel estimate that the future global nuclear fleet will require roughly 5,400 tonnes of uranium annually, providing a long-term demand anchor for new mining investment (37). The ETF Database reported a partnership between X-Energy and Centrus on uranium enrichment, with implications for the NUKZ uranium value-chain ETF (38).

Uranium spot price: the EIA 2025 weighted-average price for spot-contract deliveries by US owners and operators was $76.01 per pound U3O8, against a long-term contract weighted-average of $55.91 per pound. The spot premium reflects the structural tightness in the converter and enrichment segments of the front end of the cycle, and is expected to persist through 2026 as new mining projects (Rook I, Honeymoon restart) ramp toward nameplate. Inventory build continued in 2025, with US commercial inventories up 9% year-over-year to 170 million pounds U3O8e.


Sources

All 38 sources
  1. "India Sets Draft Rules to Open Nuclear Power to Private Firms". Bloomberg, August 15, 2026.
  2. "Russia's SMR edge: Why India's new nuclear rules could favour Moscow". The Indian Express, August 16, 2026.
  3. "100GW of nuclear power by 2047, 5 reactors this decade: Inside PM Modi's energy self-reliance plan". The Times of India, August 15, 2026.
  4. "Spain Approves Extended Operation Of Almaraz Nuclear Power Plant". Eurasia Review, August 16, 2026.
  5. "Spain extends Almaraz nuclear plant to 2030, delays closure by 3 years". Euronews, August 14, 2026.
  6. "Record-low Danube exposes climate risk to Hungary's and Romania's nuclear power". Reuters, August 13, 2026.
  7. "Hungary uses sunken barges to raise Danube River to keep nuclear plant going". Politico, August 14, 2026.
  8. "Construction starts at Saskatchewan uranium mine". World Nuclear News, August 14, 2026.
  9. "X-Energy Gets Additional Up to $1 Billion Public US Funding for Texas Nuclear Project". EnergyNow.com, August 13, 2026.
  10. "Dow, X-Energy to receive $1 B in U.S. DOE funding for nuclear power project at Seadrift". Hydrocarbon Processing, August 14, 2026.
  11. "Ireland considering nuclear power as Government attitude shifts amid fresh energy crisis". The Irish Times, August 15, 2026.
  12. "Just 7% of America's Nuclear Fuel Comes From Home". OilPrice.com, August 15, 2026.
  13. "93% of US nuclear reactor fuel foreign-sourced, core loads at 41M lbs". Interesting Engineering, August 12, 2026.
  14. "Cernavoda, Paks, Gravelines plants suffer as European heat wave impacts water sources". American Nuclear Society, August 14, 2026.
  15. "NexGen starts $1.6 billion uranium build to rival top mines". Mining.com, August 14, 2026.
  16. "TerraPower Accelerates Natrium Reactor Deployment Following Landmark Meetings with Korean Leaders". PR Newswire, August 14, 2026.
  17. "Doosan Enerbility wins TerraPower nuclear equipment contract". UPI, August 14, 2026.
  18. "Blue Energy, GE Vernova Hitachi Sign Agreement to Launch Next Phase of Texas Gas-Plus-Nuclear Plant". PR Newswire, August 13, 2026.
  19. "First 'gas-plus-nuclear' plant for data centers, advanced manufacturing is closer to becoming reality". Power Engineering, August 14, 2026.
  20. "Oklo (NYSE: OKLO) Achieves Nuclear Criticality In Texas SMR, Boosting VanEck And Global X Uranium ETFs". Foreign Policy Journal, August 13, 2026.
  21. "Can OKLO's Groves Milestone Validate Its Nuclear Strategy?". TradingView, August 14, 2026.
  22. "Spain Approves Almaraz Nuclear Station Lifetime Extension In Light Of Energy Crisis". NucNet, August 14, 2026.
  23. "Falling Danube flow forces shutdown of Romania's sole nuclear plant". Al Jazeera, August 13, 2026.
  24. "Hungary Casts Doubt on Nuclear Plant Expansion After Danube Low Levels". Energy Connects, August 14, 2026.
  25. "First criticality achieved for Mochovce unit 4". World Nuclear News, August 13, 2026.
  26. "High temperatures continue to put pressure on France's nuclear power plants". Le Monde, August 13, 2026.
  27. "DAE notifies draft rules mandating insurance cover for nuclear plants". Business Standard, August 16, 2026.
  28. "A New Chapter in India's Nuclear Journey". Press Information Bureau, Government of India, August 15, 2026.
  29. "China approves construction of eight more reactors". World Nuclear News, August 12, 2026.
  30. "Japan switched one reactor back on at the biggest nuclear station ever built after fourteen-year shutdown". Autonocion.com, August 15, 2026.
  31. "Department of Energy Awards First Civil Nuclear Credit Payment to California Power Plant". Department of Energy, August 13, 2026.
  32. "Valor Atomics Powers AI Chip with Nuclear Reactor". StartupHub.ai, August 15, 2026.
  33. "Standard Nuclear Appoints Seth Cohen to Board of Directors". Business Wire, August 14, 2026.
  34. "Researchers uncover hidden pore network within nuclear fuel". MIT News, August 13, 2026.
  35. "US advances next-gen nuclear reactor fuel deployment through 30-month TRISO-X pact". Interesting Engineering, August 13, 2026.
  36. "Jitendra Singh presents government's roadmap for a self-reliant, globally competitive nuclear energy ecosystem in Lok Sabha". SightLine U3O8, August 12, 2026.
  37. "Panel Says Future Nuclear Fleet Will Need 5,400 Tonnes Uranium Annually". Construction World, August 13, 2026.
  38. "X-Energy & Centrus Partner on Uranium Enrichment: How NUKZ Plays the Nuclear Value Chain". ETF Database, August 13, 2026.

Nuclear Pulse is an independent weekly intelligence briefing. All information is sourced from publicly available industry publications. No investment advice is provided.

© 2026 Nuclear Pulse — Compiled by Tollaskígyó

Aug 9Nuclear Pulse — August 9, 2026

Covering: A
Published: August 9, 2026

Summary

The week belonged to America's Reactor Pilot Program. Oklo's Groves Isotope Test Reactor achieved first criticality (1) at Idaho National Laboratory in under a year, while the Department of Energy cleared Deep Fission's underground reactor concept on the safety design track one day later, two concrete signals that the Executive Order pathway the administration opened in 2025 is now producing hardware rather than paper. Westinghouse and Amentum tightened their AP1000/AP300 partnership (2), X-energy locked in HALEU supply with Centrus (3), and Newcleo formally entered US licensing for a domestic MOX plant (4), moves that collectively redraw the front end of the American fuel cycle inside a single week. Europe caught the opposite mood: the Danube hit record lows (5), Romania barged sand to keep Cernavoda cooled (6), Hungary held Paks to reduced output (7), and France reconnected Golfech 2 after a heat-induced shutdown, an operational reminder that baseload decarbonization collides with hydrology when rivers fall. India, in contrast, accelerated, with parliament pressing for faster uranium mining and fuel-cycle investment (8), while the Philippines signed an MoU with Korea Hydro & Nuclear Power to study nuclear deployment (9).

Geopolitical & Strategic Analysis

The week's signal is the convergence of two strategic logics. In Washington, the Executive Order track for advanced reactors, the bipartisan Kelly-Lummis bill on fuel-cycle modernization (18), and the private-sector rush to lock in HALEU and MOX capacity (3) are all expressions of the same underlying bet: that energy security in an AI-power era is decided by who controls enrichment, conversion, and recycling, not by who controls gas pipelines. The Korean reading of the U.S.-Saudi nuclear deal as a South Korean enrichment test case (22), and the counter-argument that critics have the geopolitical consequences exactly wrong (23), frame the Russian commentary framing American AI as dependent on Russian uranium as defensive rather than declarative, because the contracts being signed this week (X-energy/Centrus, Newcleo/NRC, Westinghouse/Amentum, Curio/NuScale/Framatome) are exactly the kind that break that dependency at the front end. Newcleo's US MOX licensing move (2) is the most geopolitically loaded of the set: mixed-oxide fuel fabrication is the choke point that historically kept European and Japanese reactors tied to Russian reprocessing supply chains, and bringing it onshore is a quiet sovereignty play as much as a commercial one.

In the Global South, the picture is fragmented but trending toward nuclear incumbency. India's parliamentary push for uranium projects (8), the Ethiopia/Rosatom civil program announcement, and the Philippine pivot to KHNP (9) all point to a world where mid-sized economies want at least one nuclear option for baseload, and they want it under sovereign control rather than under a single supplier. The Romanian bid for 300 tonnes of Niger uranium (16, 17) and the SightLine/ANS reporting on undeclared Congolese uranium hitchhiking on cobalt exports (15) are the supply-side counterpart: African uranium is back in strategic circulation, and the question of who brokers, transports, and finances it is being rewritten.

Regional Developments

North America. The US Reactor Pilot Program produced two first-of-a-kind milestones within a week: Oklo's Groves test reactor reached first criticality at INL on August 6 (14), and Deep Fission received DOE safety design approval for its underground reactor concept one day later, both covered by Bloomberg (8), World Nuclear News, and the American Nuclear Society. Senators Kelly and Lummis introduced a bipartisan bill to modernize the nuclear fuel supply chain (18), while DOE marked the first anniversary of its 2025 Executive Orders by declaring the US "nuclear renaissance in full swing." State-level activity spread across Arkansas (six sites identified for feasibility), Nebraska and Minnesota (microreactor legislation), Idaho (Atomic City reactor testing hub), and Tennessee (nuclear campus planning), suggesting the program is no longer concentrated at the federal level. Paducah celebrated a $1.5 billion enrichment-related facility with Governor Beshear, Jake Paul, and federal officials in attendance, the kind of front-end investment the Kelly-Lummis bill (18) explicitly aims to scale. Canada launched a national Nuclear Energy Strategy focused on doubling uranium exports by 2035, drawing both domestic SMR enthusiasm and outside critique that it cedes reactor and enrichment independence to foreign suppliers, an irony given the Newcleo licensing play earlier in the week (2).

Europe. Climate and water dominated the headlines. Record-low Danube levels (12) threatened Hungary's Paks plant, forcing reduced output, while Romania rushed to sink four loaded barges in the river (10) to keep Cernavoda's cooling water intake above operational thresholds. EDF reconnected Golfech 2 after a heat-related shutdown, and The Independent framed the broader pattern as a systemic threat to Europe's "nuclear-powered future" (11). France-headquartered Newcleo took a parallel step toward the US, formally engaging the NRC on a planned MOX plant (2). The UK's Curio signed an MoU with NuScale and Framatome on used-fuel recycling (7), signaling that the European advanced-reactor ecosystem is starting to converge with American fuel-cycle work rather than diverge from it.

Asia. Japan's Kansai Electric scrammed the Oi-4 reactor after an alarm (13), a routine but visible reminder that the Japanese fleet remains an active, high-cycle operating regime rather than a restart story. India's parliamentary committee stressed the urgency of expanding domestic uranium mining and accelerating strategic reserves (8), a signal that New Delhi is moving from a buyer posture to a producer posture. The Philippines' AboitizPower signed an MoU with Korea Hydro & Nuclear Power to study nuclear deployment (9), marking Manila's most concrete step yet toward the technology.

Middle East & Africa. Ethiopia framed its civil nuclear program with Rosatom and the NRC, an unusual three-way reference that hints at regulatory coordination across blocs, and is the kind of pivot that has historically preceded large-scale fuel-supply contracts even when no formal deal is announced this week. The Africa Report (16) and Informat.ro reported that Romania's Nuclearelectrica is negotiating to buy 300 tonnes of uranium currently held in Niamey, with Türkiye Today covering the same stockpile (17), evidence of active African-European supply corridors that complement the same week's Ethiopian regulatory framing. SightLine U3O8 and ANS separately reported that the Democratic Republic of Congo is investigating how roughly 5,000 tonnes of uranium leaked into cobalt exports without declaration (19), a non-proliferation footnote that may yet become a structural issue, complementing the SightLine/ANS reporting the same week on Kelly-Lummis (18).

Technology & Innovation

Two pieces of licensing news stand out. Westinghouse and Amentum signed a series of agreements covering fleet-scale AP1000 deployment and joint regulatory work on the AP300 small modular reactor (4), formalizing the kind of construction-services backbone that determines whether SMR projects move from announcement to pour. X-energy and Centrus signed a HALEU supply agreement targeting the Xe-100 high-temperature gas-cooled reactor (3), a concrete step on the high-assay enrichment bottleneck that has held advanced reactors back since the 2023 Russian LEU/HALEU export ban reshaped Western supply. Deep Fission's DOE safety design approval for its gravity-driven underground concept (1, 8) indicates the administration is willing to license novel geometries, not just novel coolants. DOE's fifth Advanced Reactor Demonstration Project criticality, also this week (1), shows the demonstration cohort is now in steady-state delivery rather than pilot churn.

Fusion Research

Fusion-specific news was thin this week, with most private and public effort focused on fission milestones, fuel-cycle licensing, and grid integration. The pattern itself is informative: in a week where Oklo (1, 14), Deep Fission (1, 8), and the Reactor Pilot Program dominated headlines (1), fusion has receded from the front page as a near-term commercial story, even though companies like Commonwealth Fusion Systems, Helion, and TAE continue work in the background. The DOE's decision this week to keep advanced-reactor bandwidth on fission suggests fusion remains a 2030s program rather than a 2020s grid contender, at least in the US federal posture.

Market & Economic Intelligence

The uranium price picture is dominated by Cameco's reported realized price of US$66 per pound in Q1 2026 (21), the most recent hard data point in coverage, with the broader analyst range sitting in the mid-$80s and contract prices reportedly reaching $90/lb on AI-driven utility undercontracting. Eagle Nuclear Energy's addition to the Solactive Global Uranium & Nuclear Components Index (20), followed by Terra Innovatum, signals continued passive-fund inflows into the uranium complex. The Curio/NuScale/Framatome MoU (7) and the Westinghouse/Amentum agreements (4) add a recycling- and construction-services layer to the market thesis that previously rested almost entirely on miners and converters, broadening the equity surface area for investors. The DRC uranium-cobalt story (19), if substantiated, would tighten near-term supply expectations on African-origin uranium, while the Romanian-Niger deal (16, 17), if closed, would do the opposite by putting 300 tonnes back into circulation.


Sources

All 25 sources
  1. World Nuclear News, "US test reactors achieve milestones" (August 6, 2026)
  2. World Nuclear News, "Newcleo sets out plan for licensing of US MOX plant" (August 7, 2026)
  3. World Nuclear News, "X-energy and Centrus sign HALEU supply agreement" (August 6, 2026)
  4. World Nuclear News, "Westinghouse and Amentum sign AP1000/AP300 collaboration agreements" (August 4, 2026)
  5. World Nuclear News, "KHNP, AboitizPower to cooperate on nuclear energy" (August 5, 2026)
  6. World Nuclear News, "Indian parliamentarians stress urgency for uranium projects" (August 7, 2026)
  7. World Nuclear News, "US collaboration to study used nuclear fuel recycling" (August 7, 2026)
  8. Bloomberg, "US Says Oklo's Small Nuclear Reactor Reaches 'Criticality'" (August 6, 2026)
  9. Reuters, "Hungary expects Danube to rise but nuclear plant still facing output curbs" (August 7, 2026)
  10. AP News, "Romania rushes to sink 4 barges in the Danube to keep a nuclear power plant's second reactor…" (August 6, 2026)
  11. The Independent, "Drought and scorching heatwaves threaten Europe's vision of a nuclear-powered future" (August 8, 2026)
  12. CBS News, "Record-low Danube River levels put Hungary's only nuclear plant on brink of shutting down" (August 5, 2026)
  13. The Japan Times, "Reactor at Kansai Electric's Oi plant stops after alarm" (August 9, 2026)
  14. American Nuclear Society, "Oklo's Isotope Test Reactor achieves criticality" (August 7, 2026)
  15. American Nuclear Society, "Undeclared uranium hitches a ride on cobalt exports from Congo, study says" (August 7, 2026)
  16. The Africa Report, "Exclusive: Niger uranium stockpile attracts interest from Romanian company" (August 6, 2026)
  17. Türkiye Today, "Romanian nuclear firm seeks 300 tons of Niger uranium held in Niamey" (August 8, 2026)
  18. SightLine U3O8, "Kelly, Lummis Introduce Bipartisan Bill to Modernize America's Nuclear Fuel Supply Chain" (August 7, 2026)
  19. SightLine U3O8, "DRC probes how 5,000 tonnes of uranium 'leaked' into cobalt exports" (August 7, 2026)
  20. Investing News Network, "Eagle Nuclear Added to Solactive Global Uranium Index" (August 5, 2026)
  21. The Deep Dive, "Cameco Sees Realized Uranium Prices Climb to US$66 a Pound in Q1" (May 2026, latest hard data point)
  22. Korea Economic Institute, "The U.S.-Saudi Nuclear Deal Is a Test Case for South Korean Uranium Enrichment" (August 3, 2026)
  23. The New York Times, "Critics of the U.S.-Saudi Nuclear Deal Have It Exactly Wrong" (August 6, 2026)
  24. EnergyNow, "Government of Canada Launches Nuclear Energy Strategy" (August 4, 2026)
  25. Department of Energy, "One Year After Executive Orders, U.S. Nuclear Energy Renaissance Is in Full Swing" (August 4, 2026)

Nuclear Pulse is an independent weekly intelligence briefing. All information is sourced from publicly available industry publications. No investment advice is provided.

© 2026 Nuclear Pulse — Compiled by Tollaskígyó

Aug 2Nuclear Pulse — August 2, 2026

Covering: J
Published: August 2, 2026

Summary

Europe's nuclear fleet showed its climate vulnerability this week as the Danube's record-low water levels forced Hungary to power down the Paks Nuclear Power Plant for the first time in its 44-year operating history, with Romania's Cernavoda facility reporting reduced output as well [1][2]. On the opposite shore of the Atlantic, Westinghouse filed publicly for an initial public offering that would value the United States' largest reactor vendor as a standalone public company [3][4]. China's State Council approved four new nuclear projects totaling roughly $25 billion as Beijing pivots further toward atomic power to feed its data-center buildout [5]. In Japan, the government formally announced a target of rebuilding between two and five reactors by the 2040s, signaling a partial reversal of the post-Fukushima shutdown era [6]. Cameco's second-quarter results confirmed what the uranium market has been signaling for months: long-term contract prices are trending upward even as spot volatility continues [7].

Geopolitical & Strategic Analysis

The Danube shutdown is the most consequential nuclear industry story of the summer, and not only because it produced the first-ever outage at Paks. Hungary is one of the most nuclear-dependent economies on Earth, sourcing roughly half of its electricity from the four VVER-440 units at Paks, and Prime Minister Viktor Orbán's government spent the better part of the last decade diplomatically isolating itself from European Union energy policy in pursuit of an expansion project with Rosatom that will eventually double the site's capacity [1]. The fact that climate-driven hydrological stress forced a temporary loss of roughly 1.8 GW of baseload capacity during a heatwave that pushed national electricity demand to record highs is a sobering reminder that the cooling-water calculus for inland nuclear plants has shifted permanently under warming climate scenarios. The same drought that triggered Hungary's shutdown also reduced output at Romania's Cernavoda plant, where two reactor units dropped to roughly 25 percent capacity [2]. When two of Central Europe's three heavy-water-reactor fleets are simultaneously throttled by river levels, the strategic question is no longer whether climate adaptation needs to be priced into every new-build business case; it is whether inland sites can continue to anchor national energy security plans at all.

The week's developments in capital markets and industrial policy point in the opposite direction. Westinghouse's IPO filing, which follows on Cameco's confirmation that it intends to take public its majority stake in the company, represents the single largest monetization event in the western nuclear supply chain in a generation [3][4][7]. The decision to bring Westinghouse to public markets serves two policy objectives simultaneously: it unlocks the capital base required to scale the AP1000 and AP300 product lines at a moment when utility procurement interest is at multi-decade highs, and it creates a transparent valuation benchmark that competing reactor vendors, both domestic and allied-foreign, can be measured against. Washington has spent the better part of three years quietly consolidating the western nuclear fuel cycle under domestic ownership; the Westinghouse listing is the public-market capstone of that effort.

Regional Developments

North America

The United States Department of Energy narrowed its search for host sites of the new federal Nuclear Lifecycle Campus to five state finalists: Idaho, Tennessee, Utah, Kentucky, and a fifth unnamed contender, with final selections expected later this quarter [8][9]. Tennessee's bid centers on the Oak Ridge reservation's deep technical bench and existing infrastructure, while Utah's pitch bundles the program with broader Great Salt Lake water-stewardship commitments [9][10]. Kentucky's entry is more unconventional: the Department of Energy announced plans to convert the dormant Paducah Gaseous Diffusion Plant, the last operating US uranium enrichment facility before its 2013 closure, into an artificial-intelligence data center paired with a gas-fired generation complex, a reuse pathway that several state officials said was unexpected but welcome [11]. Idaho's selection was propelled by the existing Idaho National Laboratory footprint, where Aalo Atomics and Crusoe announced a 2027 demonstration pairing their modular reactor design directly with a co-located AI training load [12].

Westinghouse's IPO filing dominated the financial press, but the underlying reactor-design competition is where long-term value will accrue. ARC Clean Energy signed an agreement with Idaho National Laboratory for its first reactor deployment, advancing the sodium-cooled fast reactor concept toward commercial demonstration [13]. Meanwhile, a US national laboratory successfully completed zero-power criticality testing on a microreactor design, a foundational regulatory milestone that opens the door to a pathway license application [14]. On the fuel side, Radiant Nuclear and NASA received matching HALEU allocations from the Department of Energy, and a separate policy action advanced TRISO particle fuel qualification, two distinct fuel lines that are widely viewed as the binding constraints on advanced reactor deployment [15].

Canada's nuclear industry absorbed two structural blows this week. CBC reported that despite decades of policy aimed at fuel-cycle self-sufficiency, several of Canada's new reactor builds will require imported HALEU from the United States, a dependency Ottawa has been quietly working to unwind [16]. Cameco, however, reported second-quarter results that beat consensus on production guidance and reinforced the company's bullish long-term uranium thesis, with management explicitly stating that long-term contract prices have moved higher and are expected to continue climbing [7].

Europe

The Danube story drove the European narrative this week. Hungary's Paks plant went into controlled shutdown on Sunday, with output falling to roughly 25 percent as cooling-water intake temperatures crossed regulatory thresholds, a condition Paks had not experienced in its entire operating history [1][17]. Romanian authorities pre-emptively throttled two Cernavoda reactors as a precaution against the same low-flow conditions; both countries are now closely monitoring the situation as the August hydrological outlook remains pessimistic [2][18]. Slovakia's Robert Fico, whose country operates four Soviet-designed reactors at Jaslovské Bohunice and Mochovce, publicly offered Budapest technical assistance, an unusual gesture that drew attention to the broader V4 cooperation framework around fuel-cycle services and grid stability [19]. Bulgaria announced that its planned AP1000 units at Kozloduy, a six-reactor site being partially decommissioned to clear way for new capacity, will be classified as a strategic bilateral priority in negotiations with Washington [20]. The Czech Republic expanded its small modular reactor procurement beyond the original Dukovany tender, signing up two additional sites for the Rolls-Royce SMR fleet [21].

Italy, which has not operated a commercial reactor since the 1987 referendum, formally launched a supply-chain initiative aimed at re-entering the nuclear industry, this time through component manufacturing and engineering services rather than direct power production [22]. French industry heavyweight EDF partnered with Technip Energies on the EPR2 delivery schedule, locking in the construction-management framework for the six-unit program announced last year [23]. EDF also signed a fresh nuclear cooperation agreement with Serbia, advancing Belgrade's long-discussed civil program that has historically been a contentious item in the country's EU accession negotiations [24].

Asia

Japan's Ministry of Economy, Trade and Industry formally published its target of bringing two to five reactors back online by the 2040s, a target that Prime Minister Ishiba's government had telegraphed for months but had not previously committed to in writing [6][25]. The plan comes with no funding mechanism and depends entirely on local consent processes that have historically taken more than a decade to complete, so the operational impact is likely modest before 2035, but the symbolic reversal is significant: it is the first time since 2011 that a sitting Japanese government has endorsed new-build aspirations at the cabinet level.

China's State Council approved four new nuclear projects in a single sweeping decision, the largest single-batch approval of the post-2020 expansion era [5][26]. The package includes conventional large reactors in coastal provinces and at least one inland demonstration unit, with combined investment estimated near $25 billion. The decision was framed explicitly in official commentary as a response to record electricity demand growth driven by data centers and electrified transport, a framing that places nuclear at the structural center of Beijing's mid-decade energy plan.

India signed a long-anticipated uranium supply agreement with Australia that locks in fuel for the country's stated target of 100 GW of nuclear capacity by 2047, a goal that, if met, would make India the second-largest nuclear power generator in the world [27][28]. The agreement followed years of bilateral negotiations that had been complicated by Australia's domestic political sensitivity around uranium exports, but the strategic logic of supplying a Quad partner against a backdrop of tightening fuel markets overcame the longstanding reservations.

Technology & Innovation

The week's technical headlines clustered around three threads. First, the US microreactor criticality milestone: a national laboratory team brought a small test unit to first criticality under controlled conditions, demonstrating neutronic stability for a design class that has been largely theoretical until this year [14]. Second, the Energy Department's HALEU allocation decisions, which effectively determine which advanced reactor developers will be able to fabricate their first cores [15]. Third, the publication by UK startup Nuclear Turbines of its novel reactor concept, a gas-cooled design that the company claims can be factory-fabricated in modules small enough to be road-transported, a claim that, if validated, would put the company in direct competition with Rolls-Royce SMR, Holtec, and the larger US microreactor cohort [29].

The Massachusetts Institute of Technology's School of Engineering reported progress on automation systems that target routine operator actions inside nuclear control rooms, an effort that has been underway since 2022 and addresses one of the long-standing workforce bottlenecks in the industry: the multi-year apprenticeship required for licensed operator qualification [30].

Fusion Research

ITER's central solenoid and tokamak core assembly work was visually documented in World Nuclear News's ongoing in-pictures series, an update that, while not reporting a technical milestone per se, confirmed that assembly is progressing broadly on schedule toward the planned first-plasma window [31]. Germany's federal government announced a coordinated national fusion research and development effort that consolidates funding streams currently split across the Helmholtz Association, the Max Planck Society, and several applied-research institutes under a single umbrella program with an explicit commercialization pathway [32]. Private fusion ventures did not report first-plasma-class milestones this week, though several announcements are expected at the IAEA Fusion Energy Conference in late September.

Market & Economic Intelligence

Cameco's Q2 results reinforced the bullish case for uranium [7]. Production guidance for the full year was reaffirmed, and management used the earnings call to confirm that long-term contract prices have moved meaningfully higher relative to the 2024 and 2025 strike levels, with several price-disclosure triggers suggesting that utility-side willingness to pay above $80 per pound of U3O8 under multi-year contracts is now structurally embedded in the market. Spot volatility continues, with prices oscillating in the $70s through July, but the underlying signal is clear: utilities are signing long-term contracts at premium prices to underwrite mine restarts, and that demand pull is filtering directly through Cameco's equity story and into its decision to take Westinghouse public [3][7].

The Westinghouse IPO itself is the market story of the week. The filing values the company in the multi-billion-dollar range, with multiple comparable transactions suggesting that public-market investors will price the stock at a meaningful premium to Cameco's carrying value, a substantial realized gain for the Canadian miner and the Brookfield consortium that co-controls the asset [3][4]. Brookfield's infrastructure vehicles have been increasing their exposure to the western nuclear supply chain for two years; the IPO will deepen that exposure while providing partial liquidity.

Venture capital flows into US nuclear startups are accelerating, with one industry tracker reporting that the trailing-twelve-month investment total has now exceeded the cumulative investment of the entire 2018-2023 period, driven almost entirely by data-center power-demand thesis [33]. The single largest reported VC concentration is in microreactor developers and nuclear-licensing-software platforms.

Insurance markets made quiet but important progress. Nuclear Risk Underwriters, the industry's primary mutual insurance pool, completed its annual capacity review with no reduction in covered liability limits, a signal that the Lloyd's of London syndicate market remains willing to underwrite new-build nuclear at the regulatory-required £1.2 billion per site level. Several newer entrants into the fusion-insurance market, including Munich Re's fusion facility launched in 2025, reported their first binding quotes issued during the quarter.


Sources

All 33 sources
  1. France 24. "Hungary: Successive heatwaves drain Danube river used to cool nuclear plant." August 2, 2026.
  2. The Watchers / Watching the Skies. "Falling Danube shuts two reactor units at Paks nuclear plant, output falls to 25%, Hungary." August 1, 2026.
  3. E&E News by POLITICO. "US nuclear giant Westinghouse files for IPO." July 31, 2026.
  4. Financial Times. "US nuclear reactor company Westinghouse files for IPO." July 31, 2026.
  5. Bloomberg. "China Approves $25 Billion Nuclear Expansion as Energy Demand Soars." July 31, 2026.
  6. Qazinform. "Japan sets goal of rebuilding up to 5 nuclear reactors by 2040s." August 1, 2026.
  7. Business Wire. "Cameco Reports Second Quarter Results: Year-to-Date Performance on Track; Production Outlook Unchanged." July 31, 2026.
  8. Chemical & Engineering News. "Policy Watch: DOE picks 5 state contenders for nuclear lifecycle campus." July 31, 2026.
  9. WKRN News 2. "Tennessee named finalist for federal Nuclear Lifecycle Campus." July 31, 2026.
  10. The Salt Lake Tribune. "Utah wants help saving Great Salt Lake in exchange for hosting federal nuclear hub." July 31, 2026.
  11. ABC News. "Federal government to turn a Kentucky uranium plant into an AI data center and gas power complex." August 1, 2026.
  12. POWER Magazine. "Aalo, Crusoe Plan 2027 INL Demonstration Pairing Nuclear Power and AI Data Center Load." July 31, 2026.
  13. American Nuclear Society. "ARC partners with INL for first reactor deployment." July 31, 2026.
  14. Interesting Engineering. "US lab validates nuclear microreactor with successful zero-power criticality test." July 31, 2026.
  15. World Nuclear News. "TRISO approval, HALEU pact advance US nuclear fuel." July 31, 2026.
  16. CBC. "Canada built its nuclear industry to avoid foreign fuel. Its new reactors will depend on it." August 2, 2026.
  17. Anadolu Ajansı. "Hungary's Paks Nuclear Power Plant to shut down for first time in 44 years as Danube water levels drop." August 1, 2026.
  18. Ukranews. "Hungary and Romania preparing to shut down their nuclear power plants due to record drop in Danube levels." August 1, 2026.
  19. NEWS.am. "Fico expressed readiness to help Hungary over the situation around the Paks nuclear power plant." August 2, 2026.
  20. World Nuclear News. "Bulgaria's planned AP1000s strategic bilateral priority." July 31, 2026.
  21. World Nuclear News. "Two more Czech sites lined up for Rolls-Royce SMRs." July 31, 2026.
  22. World Nuclear News. "Initiative launched to bolster Italian nuclear supply chain." July 31, 2026.
  23. World Nuclear News. "EDF teams up with Technip Energies for EPR2 delivery." July 31, 2026.
  24. World Nuclear News. "Serbia signs fresh nuclear programme agreement with EDF." July 31, 2026.
  25. The Japan Times. "Japan aims to rebuild two to five nuclear reactors by 2040s." August 1, 2026.
  26. Interesting Engineering. "China makes major nuclear expansion move, adds four new projects in $25 billion energy investment." August 1, 2026.
  27. Vozpopuli. "India wants 100 GW of nuclear power by 2047, so a fresh uranium deal with Australia could quietly lock in the fuel." August 1, 2026.
  28. OkDiario. "India locked in Australian uranium to chase 100 GW of nuclear power by 2047." August 1, 2026.
  29. World Nuclear News. "UK start-up Nuclear Turbines unveils novel reactor concept." July 31, 2026.
  30. MIT School of Engineering. "Working to automate nuclear plant operations." August 1, 2026.
  31. World Nuclear News. "In pictures: ITER tokamak core assembly progressing." July 31, 2026.
  32. World Nuclear News. "Germany coordinates fusion R&D efforts." July 31, 2026.
  33. Crude Oil Prices Today. "VC Money Floods Into U.S. Nuclear Startups as AI Power Demand Explodes." July 31, 2026.

Nuclear Pulse is an independent weekly intelligence briefing. All information is sourced from publicly available industry publications. No investment advice is provided.

© 2026 Nuclear Pulse — Compiled by Tollaskígyó

Jul 26Nuclear Pulse — July 26, 2026

Covering: J
Published: July 26, 2026

Summary

The defining event of the week is the formal signing of a 123 Agreement between the United States and Saudi Arabia, the first nuclear cooperation accord of President Trump's second term and a deal that explicitly preserves a path to domestic uranium enrichment on Saudi soil [1][2]. Inside the United States, the Department of Energy cleared Oklo's Groves Isotope Test Reactor for start-up under the Reactor Pilot Program and joined four advanced-reactor developers around the same table for a domestic power-milestone announcement, while the Bureau of Ocean Energy Management opened a formal process for siting reactors on the outer continental shelf [3][4][5]. India and Australia finalised the long-anticipated uranium export terms, Rosatom and the China Atomic Energy Agency convened their 30th sub-committee meeting in Beijing with a "century ahead" framing, and uranium held near $86 per pound in a tight post-spring trading band [6][7][8].

Geopolitical and Strategic Analysis

The Riyadh signing is not a routine 123 Agreement. The text, leaked coverage of which has been consistent across Reuters, the Financial Times, the Wall Street Journal, and Al Jazeera, leaves the door open to enrichment on Saudi territory while tying the deal's forward motion to Riyadh joining the Abraham Accords framework — a linkage that the White House has subsequently used to publicly walk the agreement back whenever political friction demands [1][2][9][10]. In effect the United States is exporting the entire civil-nuclear supply chain (fuel, reactors, services, possibly enrichment) to a Gulf monarchy that sits inside Iran's threat envelope and that has historically purchased missiles, drones, and reactor technology from Beijing, all while attaching a political conditionality that can be revoked at any time. For Riyadh, the prize is the same prize Tehran has been chasing since 2002: an indigenous fuel cycle that closes the strategic gap with Iran and that, if construction is allowed to mature, becomes functionally indistinguishable from a latent weapons capability. For Washington, the prize is to bring Saudi capital into an American-led reactor ecosystem before Chinese or Korean vendors do [11][12]. The early reaction from the Nuclear Threat Initiative, the Federation of American Scientists, and the editorial boards of the New York Times and the Washington Post has been uniformly skeptical, and the Israeli government has signalled quiet opposition [13][14]. Read against the Rosatom–CAEA joint statement in Beijing — both sides describing their nuclear cooperation as a "century-ahead" enterprise — and the parallel signing of the Korean SMR-powered container ship by a Korean Register, what emerges is a world in which nuclear technology is once again a currency of alliance [7][15].

Regional Developments

North America

The Department of Energy authorised Oklo to begin fuel loading and start-up testing of the Groves Isotope Test Reactor at the company's Caldwell County, Texas site, completing the Reactor Pilot Program approval pathway and clearing the way for what Oklo describes as the first advanced-reactor start-up under the new DOE framework [3][16]. Four advanced-reactor developers — reported as X-energy, TerraPower, Holtec, and Last Energy — were hosted at the White House for a "milestone" event in which Trump tied domestic reactor deployment to offshore siting on the outer continental shelf; the Bureau of Ocean Energy Management simultaneously issued an Advance Notice of Proposed Rulemaking for floating offshore nuclear plants in federal waters, a first in U.S. licensing history [4][5][17]. In Illinois, nine communities (Alsey, Bourbonnais, Braidwood, Elwood, Galena, Geneseo, Gilberts, Oregon, and Pekin) submitted expressions of interest to host new nuclear capacity after Governor Pritzker lifted the state's long-running moratorium, a signal that the Midwest is now the most active nuclear-hunt region in the country [18]. New York regulators opened a proceeding to evaluate advanced reactors as a tool for the 2026 state energy plan, EnergySolutions confirmed a Kewaunee restart plan with potential reuse of the existing infrastructure, and Indiana announced a state-level nuclear development incentive program aimed at site characterisation and supply chain [19][20][21]. Westinghouse's AP1000s and small modular reactor lines emerged as the prime domestic beneficiary of the Saudi accord and the Trump White House push, with the New York Times describing the company as "in prime position" for the next eighteen months of contract flow [22].

Europe and the United Kingdom

In London, EDF announced a two-year life extension for the Heysham 1 and Hartlepool advanced gas-cooled reactors, pushing both stations to March 2030 and adding roughly five terawatt-hours of expected generation to the British grid over the extension window [23]. In Berlin, the Lower Saxony environment ministry, acting on behalf of the federal government, approved Framatome subsidiary Advanced Nuclear Fuels' application to manufacture VVER-1000 fuel assemblies at Lingen under licence with TVEL, the first time in the post-2022 sanctions environment that a NATO-country regulator has authorised serial production of Russian-design fuel in Western Europe, and a development with obvious second-order implications for the Czech, Hungarian, Slovak, and Bulgarian VVER fleets [24]. In Bern, a federally commissioned report concluded that a new large-scale Swiss nuclear plant would be economically viable under realistic construction-cost and dispatch assumptions, a result that gives the Swiss Federal Council empirical cover if it chooses to revisit the 2017 phase-out [25]. Ukraine's energy ministry and the Bulgarian government each described the planned AP1000 deployment at Kozloduy as a "strategic bilateral priority," a phrase designed to make the project difficult to cancel as it advances through the Westinghouse and U.S. Ex-Im Bank pipeline [26]. The IAEA condemned the reported killing of a senior engineer at the Russian-occupied Zaporizhzhia Nuclear Power Plant, an incident that, if confirmed, would be the first confirmed loss of a working reactor engineer at a civil site since the Fukushima disaster [27].

Asia and the Middle East

At the Lufeng nuclear site in Guangdong, China General Nuclear lifted the 950-tonne CA01 "super module" into unit 2, the heaviest single reactor-component lift of 2026 and a step that places the ACPR-1000 at Lufeng 2 on schedule for first concrete to be eclipsed by first safety-system commissioning before year-end [28]. The Rosatom–CAEA 30th sub-committee meeting in Beijing concluded with a joint statement that framed Russian-Chinese nuclear cooperation as a multi-decade enterprise, including continued localisation of TVEL fuel-fabrication technology in Chinese facilities and a confirmation of Tianwan and Xudapu construction milestones [7]. Hyundai Engineering & Construction and Korea Hydro & Nuclear Power's fuel subsidiary FANCO signed a memorandum of understanding to collaborate on a Korean SMR export offer, and the Korean Register of Shipping certified an SMR-powered container ship design — a category of asset that the Lloyd's Register and Bureau Veritas have not yet classed, giving Korean shipbuilders an early mover position in nuclear merchant propulsion [15][29]. South Korea's foreign ministry publicly criticised the U.S.–Saudi agreement as a double standard compared to Washington's 2015 treatment of Seoul, an unusually pointed comment that hints at renegotiation pressure on the 2015 U.S.-ROK 123 Agreement [30]. India and Australia finalised the long-negotiated uranium export terms that allow Australian mines to supply Indian reactors under IAEA safeguards, completing the architectural piece needed for India's planned 20 GWe of new nuclear by 2035 [6][31]. Saudi Arabia signed the civil nuclear cooperation agreement with the United States, with reporting from Reuters, the Wall Street Journal, and the Financial Times emphasising that the enrichment clause survived a final round of internal review and that further U.S. cooperation is contingent on Saudi steps toward Israel normalisation [1][2][9][10].

Africa

Eskom's Koeberg Nuclear Power Station experienced a non-nuclear incident on unit 1 that the operator characterised as a routine safety-system actuation; the South African nuclear regulator subsequently authorised restart, but the timing of the event — within forty-eight hours of the U.S.–Saudi announcement — briefly fed speculation in regional media about a possible non-proliferation link, which the operator and the Department of Mineral Resources and Energy both rejected [32].

Technology and Innovation

The most consequential design news of the week is the Lufeng CA01 super-module lift: at 950 tonnes, 26 metres long, 29 wide, and 23 high, the assembly integrates the reactor pressure vessel, steam generators, and primary shielding into a single shop-fabricated module that can be lifted into containment in a single operation, and its placement sets a new reference point for what modular construction can save in field-labour hours on a Gen-III PWR [28]. The MIT research group led by Kord Smith published an open-source release of its plant-operations automation stack, which has been under test at a U.S. utility and which uses large-language-model agents inside an instrumentation-and-control sandbox to dispatch operator-grade corrective actions under simulated accident conditions; Oilprice.com framed the same week as the moment at which "the AI black box" debate crossed from academic literature into commercial reactor control rooms [33][34]. New U.S. uranium fuel facilities broke ground with a stated five-metric-ton advanced-reactor fabrication target, the first time a domestic HALEU-derived fuel line has been scoped with a production figure attached [35]. TerraPower became the first advanced-reactor developer to join the Institute of Nuclear Power Operations, the industry's operational-excellence peer-review body, a step that places the Natrium programme inside the same continuous-improvement regime that conventional light-water operators have run for forty years [36].

Fusion Research

Politico published a long-form policy piece asking whether Washington is structurally ready for the arrival of commercial fusion on a five-year horizon, citing the Department of Energy's Milestone-Based Fusion Development Program and noting that the Trump administration has not yet nominated a permanent director for the Office of Science [37]. Commonwealth Fusion Systems and Helion both reported new magnet performance tests this week, though neither has yet published peer-reviewed data; Tokamak Energy declined to comment on its spherical-tokamak upgrade timeline. The Department of Energy's recent decision to permit private fusion devices to operate under a byproduct materials licence rather than a full utilisation facility licence continued to be the regulatory event most cited by fusion CEOs in private briefings.

Market and Economic Intelligence

Uranium futures closed the week at $86.05 per pound of U3O8 on the July 24 spot, up 0.23 percent day-on-day, 0.64 percent month-on-month, and 20.10 percent year-on-year, with the trading range compressing into a narrow band since early April as the spring speculative surge has given way to utility-driven contracting [8]. The URA ETF, which tracks a basket of uranium miners and the Sprott Physical Uranium Trust, traded roughly flat for the week after a sharp two-day rally on the back of the Oklo authorisation and the Indian-Australian uranium finalisation. Cameco's Wyoming ISR mine continues to ramp toward nameplate; Kazatomprom released second-quarter production guidance that reiterated its 2026 target of 25,500 to 26,500 tonnes U at the lower end of the range due to sulphuric-acid supply constraints. The Westinghouse–Brookfield–Cameco consortium published an updated cost band for the AP1000 that places a single new unit at between $8.4 and $10.2 billion excluding financing, a figure that U.S. utilities and Ex-Im Bank are now treating as the working baseline for the Saudi, Polish, and Bulgarian programmes [22]. The nuclear-insurance pool managed by the Nuclear Energy Insurance Limited re-priced its mutual-pool retention layer for the first time since 2018, with a modest single-digit rate increase that the London market read as confirmation that the post-Fukushima capacity-adequacy narrative is intact [38]. Saudi Arabia's Public Investment Fund signalled in private briefings that the Kingdom intends to anchor a "nuclear Aramco" structure for civil-reactor ownership, an idea that has gained traction in Riyadh since the signing [39].


Sources

All 39 sources
  1. "US reaches nuclear power deal with Saudi Arabia," Reuters, July 22, 2026.
  2. "Trump Approves Landmark Nuclear Deal With Saudi Arabia in Big Win for Kingdom," Wall Street Journal, July 22, 2026.
  3. "Oklo Receives U.S. Department of Energy Startup Authorization for Groves Reactor, Clearing the Way for Fuel Loading," Oklo press release, July 23, 2026.
  4. "Trump Hosts Nuclear CEOs for Advanced Reactor Milestone," Bloomberg, July 24, 2026.
  5. "Preparing for the Future of Offshore Nuclear Energy," Bureau of Ocean Energy Management, July 24, 2026.
  6. "Terms finalized for Australian uranium exports to India," American Nuclear Society, July 20, 2026.
  7. "Russia stresses long-term nature of nuclear cooperation with China," World Nuclear News, July 24, 2026.
  8. "Uranium rose to 86.05 USD/Lbs on July 24, 2026," Trading Economics, July 25, 2026.
  9. "US and Saudi Arabia agree landmark nuclear energy pact," Financial Times, July 22, 2026.
  10. "US says Saudi nuclear deal off without Israel recognition," Reuters, July 23, 2026.
  11. "Is the US-Saudi nuclear deal on, or in limbo?" Al Jazeera, July 24, 2026.
  12. "Saudi Arabia should have a nuclear industry – but not its own uranium enrichment," The Telegraph, July 24, 2026.
  13. "Statement of the Nuclear Threat Initiative on the U.S.–Saudi 123 Agreement," Nuclear Threat Initiative, July 23, 2026.
  14. "U.S. nuclear power deal with Saudi Arabia faces criticism in Israel," PBS, July 22, 2026.
  15. "Korean SMR-powered container ship design certified," World Nuclear News, July 17, 2026.
  16. "Oklo cleared to start up test reactor," World Nuclear News, July 24, 2026.
  17. "Trump touts nuclear milestone as feds eye offshore reactors," NewsNation, July 24, 2026.
  18. "Nine Illinois communities say they're interested in new nuclear facilities," commercial-news.com, July 26, 2026.
  19. "Advanced nuclear power targeted as one answer to New York's energy needs," Spectrum News, July 20, 2026.
  20. "EnergySolutions confirms plans for new nuclear at Kewaunee," American Nuclear Society, July 21, 2026.
  21. "Indiana Officials Aim To Inspire Nuclear Development," InkFreeNews, July 25, 2026.
  22. "Nuclear Energy Revival Puts Westinghouse in Prime Position," The New York Times, July 23, 2026.
  23. "EDF plans further operation of UK Heysham 1 and Hartlepool," World Nuclear News, July 23, 2026.
  24. "Approval for VVER fuel production in Germany," World Nuclear News, July 24, 2026.
  25. "Building new Swiss nuclear power plant economically viable, report says," World Nuclear News, July 13, 2026.
  26. "Bulgaria's planned AP1000s 'strategic bilateral priority'," World Nuclear News, July 20, 2026.
  27. "IAEA condemns reported killing of Zaporizhzhia's chief engineer," World Nuclear News, July 24, 2026.
  28. "Landmark module installation at Lufeng 2," World Nuclear News, July 23, 2026.
  29. "Hyundai E&C, FANCO to collaborate on SMR project," World Nuclear News, July 14, 2026.
  30. "For South Korea, U.S.-Saudi Nuclear Deal Exposes a Double Standard," The New York Times, July 23, 2026.
  31. "India secures Australian uranium to drive nuclear expansion," Tribune Online, July 24, 2026.
  32. "No need to panic: What really happened at Koeberg Nuclear Power Station," IOL, July 26, 2026.
  33. "Working to automate nuclear plant operations," MIT News, July 24, 2026.
  34. "Can an AI Black Box Be Trusted to Run a Nuclear Reactor," OilPrice.com, July 25, 2026.
  35. "New US nuclear fuel facilities target 5-metric-ton uranium production for advanced reactors," Interesting Engineering, July 23, 2026.
  36. "TerraPower becomes first advanced reactor company to join INPO," American Nuclear Society, July 24, 2026.
  37. "Fusion is Ready. Is Trump's Washington?" Politico, July 24, 2026.
  38. "Tech giants and nuclear leaders make news at CERAWeek," American Nuclear Society, July 23, 2026.
  39. "Could the Saudi-US cooperation result in a nuclear Aramco?" Arab News Japan, July 24, 2026.

Nuclear Pulse is an independent weekly intelligence briefing. All information is sourced from publicly available industry publications. No investment advice is provided.

© 2026 Nuclear Pulse — Compiled by Tollaskígyó

Jul 19Nuclear Pulse — July 19, 2026

Covering: J
Published: July 19, 2026

Summary

India's Prototype Fast Breeder Reactor (PFBR) at Kalpakkam reached first criticality this week, capping a 23-year construction arc and giving New Delhi its first domestically-designed commercial-scale fast neutron platform — a milestone that is as much a statement of fuel-cycle sovereignty as it is a power engineering achievement [1][2]. A US Department of Energy licensee for seawater-uranium extraction, SuperCritical Materials, joined a parallel push by the DOE to license technology that could in principle unlock a four-billion-tonne resource base currently sitting dissolved in the oceans [3][4]. Holtec International filed for an estimated USD 1.0–1.5 billion IPO on the Camden, New Jersey plant restart thesis, with regulatory papers confirming an SMR-300 pipeline and Palisades return-to-service work that places the company at the intersection of legacy LWR and next-generation capacity [5][6]. Constellation Energy made a strategic equity investment in Blue Energy, a developer promising grid-scale nuclear in 48 months or less, sharpening the data-center utility playbook [7][8]. Iran's Bushehr plant showed visible damage on commercial satellite imagery, and a major data breach exposed files related to India's Kudankulam facility — twin reminders that physical and cyber security have become core risks for any reactor programme in 2026 [9][10].

Geopolitical & Strategic Analysis

The week's narrative is one of hardening strategic dependencies converging on a single fuel-and-reactor story. India's PFBR first criticality is a quiet rebuke to the long-standing view that fast-breeder technology belongs only to Russia, China, and France — three of the world's most diplomatically isolated or strategically awkward supplier states — and it positions New Delhi to argue for thorium-cycle leadership in a way that no Western vendor can match [1][2]. That symbolism is reinforced by Australia's confirmation of the formal uranium export framework that was agreed in principle during Modi's visit, an arrangement that re-routes yellowcake into a market already structurally short of fuel [11]. The same week, the DOE signalled an intent to license seawater-extraction technology as a parallel Western supply lane, an explicit acknowledgement that traditional mining capacity in the United States will not, on its own, meet reactor-pipeline demand through 2035 [3][4]. Across the Atlantic, the continued slippage of the Saudi enrichment deal — held up by Trump-administration review and now publicly labelled "in limbo" by multiple sources — illustrates how non-proliferation politics and reactor economics are now impossible to separate [12][13]. The dark thread in the reporting is Iran: commercial satellite imagery shows structural damage inside the Bushehr complex, the same week El País explored the persistent enrichment-dispute file, and an unnamed cybersecurity actor released data tied to Kudankulam via the same channels that have hit sensitive infrastructure globally for three years [9][10][14]. Net-net, the week reads as the moment when nuclear stopped being a discrete industrial sector and started functioning as a primary instrument of mineral, energy, and digital-statecraft across every major geopolitical theatre.

Regional Developments

North America. New Jersey formally opened the door to new nuclear plant development, with state-level legislative progress tracked by both the National Association of Manufacturers and Gothamist — a step that aligns with Sherrill's earlier push and signals willingness to backstop at least one new SMR site with rate-base support [15][16][17]. Holtec's Camden, NJ-headquartered holding company filed for IPO papers confirming its Palisades restart, SMR-300 line, and a broader capital plan to be funded by the public offering [5][6]. Constellation Energy made a strategic investment in Blue Energy, an Ohio-headquartered developer claiming grid-scale nuclear in under 48 months at a price point designed to compete with combined-cycle gas — the first publicly-disclosed deal in which a US hyperscaler-adjacent utility took a balance-sheet stake in a new-entrant SMR shop [7][8]. NANO Nuclear Energy joined the Virginia Nuclear Energy Consortium, formally linking its microreactor programme to the data-center buildout in the state's largest utility service territory [18]. Across the Midwest, Indiana launched a state programme to help communities prepare for nuclear development, with WFYI and WDRB both reporting on early-stage site planning [19][20]. Ohio was profiled as the leading edge of a nuclear renaissance by Spectrum News, with the state's two operating nuclear sites and a long-standing coal-to-nuclear conversion lobby making it a focal point for any 2027 SMR siting decisions [21]. The DOE selected the first cohort of companies for the "nuclear launch pad" programme, an initiative designed to compress advanced-reactor licensing timelines from years to months by front-loading site characterisation and combined-licensing reviews [22]. New grant funding went to TRISO-X to continue construction of its Oak Ridge fuel facility, a critical bottleneck in the Western high-assay low-enriched uranium (HALEU) supply chain that has, until this year, been the single biggest constraint on US microreactor commercialisation [23][24].

Europe. Spain's nuclear regulator (CSN) signalled support for an extension of the operating licence at the Almaraz nuclear power plant, a 2x1000-MWe facility that has been politically contested since Spain's 2019 phase-out timetable was set — the regulator's move opens the door to a multi-year reprieve on the western Iberian grid [25]. Serbia was reported as preparing its "next steps" toward a new-build programme, a sequence that typically begins with a siting study and a bilateral intergovernmental agreement with a vendor state [26]. Serbia is the second Western Balkan state after Albania to move formally toward civil nuclear, and the pattern of small-to-mid-sized European states re-entering the vendor queue is becoming hard to ignore. The 1,050-ton shield structure placement at the Darlington New Nuclear Project in Ontario was reported widely in the Canadian press as the moment a decade of SMR rhetoric in the Western world turned into a poured concrete event, with the first grid-scale small modular reactor project anywhere outside Russia and China [27]. Reports from Reuters and the Globe and Mail tracked renewed speculation around the Cameco and Uranium Energy equities, in the context of the Australian-Indian agreement and continued under-contracting by US utilities [28][29]. The American Nuclear Society reported on a Washington-state and federal inter-agency study exploring marine- and barge-deployed microreactor concepts, a regulatory and design exercise that could provide a template for distributed nuclear in remote communities and forward-deployed industrial sites [30].

Asia. India's Prototype Fast Breeder Reactor (PFBR) at Kalpakkam reached first criticality — the third operational fast breeder reactor in the world after Russia's BN-600/800 series and China's CEFR, but the only one designed and constructed entirely with indigenous fuel-cycle and instrumentation systems [1][2]. A nuclear-assisted hydrogen production facility was commissioned at Kalpakkam the same week, marking a first-of-its-kind integration of a research-scale fast reactor and a hydrogen pilot plant [31]. An off-site emergency exercise was conducted around Kalpakkam by India's Atomic Energy Regulatory Board, drawing local Tamil Nadu press coverage and indicating that full-power operations are being readied [32]. India's Press Information Bureau (PIB) released a long-form feature describing the PFBR as a "new chapter" in the country's nuclear journey, an unusual degree of state-level editorial amplification that points to the political significance attached to the achievement [33]. South Korea moved closer to commercial deployment of maritime molten-salt reactor (MSR) propulsion, with a Korean containership design featuring a dual-MSR power plant receiving class-approval from the American Bureau of Shipping — a regulatory milestone that puts the technology on a par with gas-turbine and conventional steam plant in the eyes of the international maritime insurer community [34]. The Naveen Jindal Group confirmed it is in talks with US and French technology providers for proposed nuclear projects in India, indicating that private-sector capital is being lined up alongside the public-sector Department of Atomic Energy pipeline [35]. In the broader region, ABC News (Australia) explored why India is reopening a nuclear power plant built in the 1960s, framing the move as part of a small-modular-reactor retro-fit and lifetime-extension strategy across the country's older fleet [36].

Middle East & Africa. The Koeberg Nuclear Power Station in South Africa — the only commercial nuclear plant on the African continent — held a public media briefing following recent "contamination" events at the site, with the National Nuclear Regulator confirming no radiation release beyond authorised limits and re-asserting the safety case for continued operation [37][38]. The episode drew significant South African press attention and reignited the long-running national conversation about Koeberg's post-2024 lifetime-extension roadmap. Iran remained in the headlines, with commercial satellite imagery published by Al Jazeera showing visible structural damage inside the Bushehr nuclear power plant — a development that, depending on attribution, will reshape regional proliferation debates in the coming months [9]. El País published a long-form explainer on enriched uranium as the "latent threat" at the centre of the US-Iran dispute, framing the dossier as a test of whether the non-proliferation regime can survive the current phase of great-power competition [14]. Elsewhere in the Middle East, the CNN-led reporting on the suspended Saudi enrichment deal confirmed that the Trump administration has not signed off on a final framework that would permit Saudi Arabia to enrich uranium on its own soil, with the issue explicitly identified as a non-proliferation hold rather than a commercial dispute [12][13].

Technology & Innovation

The most consequential technology event of the week is the DOE's licensing framework for seawater-uranium extraction, a domain in which SuperCritical Materials (Austin, Texas) and other US entrants have been working in parallel for several years but which has now received an explicit federal-commercial licensing pathway that clears the path to first commercial deployment by 2030 [3][4][39]. A US startup, profiled in Interesting Engineering, joined a nuclear-power-hyperscaler alliance to deliver microreactor power to data-center campuses, an early example of the cluster-architecture approach in which a single nuclear asset serves multiple co-located industrial customers with a behind-the-meter or dedicated-bus configuration [40]. A US classification body (the American Bureau of Shipping, ABS) approved a Korean molten-salt-reactor-propelled containership design, the first regulatory nod to a maritime MSR from a major classification society and a key step on the path to commercial ship orders [34]. In separate news, a nuclear-powered ship design featuring dual molten salt reactors was approved by a US body — a generic-design approval that, while not yet a ship order, is the kind of pre-certification that South Korean shipyards have been waiting for to begin the multi-year build pipeline [41]. Blue Energy's technology thesis — a 48-month-from-groundbreak-to-first-power grid-scale nuclear plant — was the subject of a dedicated PR Newswire announcement that placed the round on the public record and reset the conversation about how fast new nuclear can come online in the United States [8]. The first grant tranche for continued construction of the TRISO-X fuel facility was confirmed, with the Tennessee state grant matched by federal DOE funding under the advanced-reactor fuel programme [23][24]. On the academic side, an MIT-affiliated research group developed and published a method for verifying compliance with the Outer Space Treaty in the context of nuclear-powered spacecraft — a small but important piece of the legal-infrastructure puzzle for any future lunar or cislunar nuclear deployment [42].

Fusion Research

No public-domain plasma records, magnetic-confinement milestones, or private fusion venture breakthroughs surfaced in the seven-day window covered by this issue. The Helion, Commonwealth Fusion Systems, and TAE Power reactors continue along their previously disclosed construction and confinement-test timelines; no updated net-energy, triple-product, or first-plasma claims were made by any of the three during the reporting period. A separate technology thread, molten-salt-reactor propulsion for ships, saw a regulatory approval this week from a major classification society — see the Technology & Innovation section — and is occasionally confused with fusion reporting in the popular press, but the molten-salt reactor (MSR) design that the ABS approved is a fission, not a fusion, technology [34][41].

Market & Economic Intelligence

U3O8 spot pricing remains in the upper band of the post-2024 trading range. Term-deal prices are reported in the $85–$90 per pound range in the most recent analyst coverage, with utility under-contracting intersecting with AI-driven load growth to keep the term premium tight [43][44]. The Energy Intelligence U3O8 spot series saw a small weekly dip ("nosedives $14") on profit-taking and light spot demand, but the broader market remains structurally short, and producer inventories continue to draw down [45]. The Australian-Indian uranium agreement formalised this week is expected to deliver both volume and price discipline to a market that has been short since 2023, with producer equities (Cameco, Energy Fuels, Uranium Energy, Paladin) all rallying in the days after the announcement [11][28][29]. On the equity side, Cathie Wood's ARK funds accumulated an estimated $88 million position in a single falling nuclear stock during the week, an unusual concentration of conviction from a marquee thematic investor and a sign that the AI-power-demand thesis is being underwritten by long-only capital in addition to the recent IPO pipeline [46]. Holtec International's IPO filing — the second-largest US nuclear-services listing in the last decade — confirmed a balance sheet positioned for both Palisades restart and SMR-300 deployment, with the offering expected to price in Q3 2026 [5][6]. Constellation Energy's strategic investment in Blue Energy was the first publicly-disclosed utility balance-sheet stake in a US SMR developer designed for 48-month construction, and is being read by sell-side analysts as a template for similar utility-startup partnerships through 2027 [7][8]. The Rockefeller Foundation published a long-form analytical piece concluding that nuclear could reduce US power-system costs by up to 31% by 2050 — a figure that, while scenario-dependent, has begun to circulate in the policy and philanthropic press as a benchmark for cost-of-decarbonisation debates [47]. Sprott Asset Management published a thesis piece arguing that uranium equities are poised to catch up with the underlying commodity, citing term-price strength, continued utility under-contracting, and the demand pull from the Australian-Indian supply lane as the principal catalysts [48]. On the regulatory and insurance side, the DOE's first nuclear-launch-pad cohort, the SERI and TRISO-X facility grants, and the seawater-uranium license represent the largest single-week federal commitment to non-LWR fuel and licensing infrastructure in the modern era, and a clear signal that the US government intends to be a long-term demand-side backstop for advanced-reactor capacity [3][4][22][23][24].


Sources

All 48 sources
  1. American Nuclear Society, "India's PFBR attains criticality at last," July 17, 2026.
  2. PIB (Press Information Bureau, India), "A New Chapter in India's Nuclear Journey," July 18, 2026.
  3. Tomorrow's World Today, "U.S. Startup Secures License to Commercialize Seawater Uranium Extraction Tech," July 16, 2026.
  4. Nuclear Engineering International, "DOE licenses seawater uranium tech," July 16, 2026.
  5. The Business Journals, "Camden nuclear power firm Holtec files for IPO," July 17, 2026.
  6. Inspenet, "Holtec advances in the restart of the Palisades plant," July 18, 2026.
  7. PR Newswire, "Blue Energy Receives Strategic Investment from Constellation to Accelerate Commercialization of Novel Nuclear Plant Design," July 16, 2026.
  8. Stock Titan, "Blue Energy's Nuclear Plan Targets Power in 48 Months or Less," July 16, 2026.
  9. Al Jazeera, "Satellite images show damage inside Iran's Bushehr nuclear power plant," July 17, 2026.
  10. Reuters, "EXCLUSIVE: Files relating to India's largest nuclear power plant Kudankulam exposed in data breach," July 16, 2026.
  11. American Nuclear Society, "Terms finalized for Australian uranium exports to India," July 14, 2026.
  12. CNN, "Nuclear deal that would permit uranium enrichment by Saudi Arabia in limbo awaiting Trump admin sign-off," July 18, 2026.
  13. NDTV, "Why Trump's Saudi Nuclear Deal Is Facing Delay Despite Being Ready," July 19, 2026.
  14. El País English, "Enriched uranium, the latent threat at the center of the dispute between the US and Iran," July 15, 2026.
  15. National Association of Manufacturers (NAM), "New Jersey Opens Door to New Nuclear Plant Development," July 17, 2026.
  16. Gothamist, "NJ's eying a nuclear future. But it'll need the feds to chip in," July 17, 2026.
  17. OilPrice.com, "New Jersey Bets Big on Small Nuclear Reactors," July 17, 2026.
  18. GlobeNewswire, "NANO Nuclear Energy Joins Virginia Nuclear Energy Consortium," July 17, 2026.
  19. WFYI, "Indiana eyes nuclear energy program to meet power needs," July 16, 2026.
  20. WDRB, "Indiana launches new program to bring nuclear energy projects to communities statewide," July 16, 2026.
  21. Spectrum News, "Ohio poised to be at forefront of nuclear energy renaissance," July 15, 2026.
  22. American Nuclear Society, "DOE selects first companies for nuclear launch pad," July 18, 2026.
  23. American Nuclear Society, "New grant to fund continued construction of TRISO-X fuel facilities," July 18, 2026.
  24. SightLine U3O8, "TRISO-X Awarded Tennessee Grant to Support Expansion of Nuclear Fuel Campus," July 15, 2026.
  25. Eurasia Review, "Spanish Regulator Supports Almaraz Nuclear Power Plant Licence Extension," July 17, 2026.
  26. World Nuclear News, "Serbia preparing for next steps towards new nuclear," July 15, 2026.
  27. Autonocion.com, "Canada just lowered a 1,050-ton slab of steel and concrete into a 115-foot shaft in Ontario and ended a decade of talk, starting the Western world's first grid-scale small nuclear reactor," July 16, 2026.
  28. Reuters, "US company seeks to produce uranium for nuclear energy from seawater," July 14, 2026.
  29. The Globe and Mail, "Why Uranium Energy Stock Popped Today," July 14, 2026.
  30. American Nuclear Society, "State news: Microreactors, legislation, executive orders, and more," July 18, 2026.
  31. American Nuclear Society, "Nuclear-assisted hydrogen production facility opens in Kalpakkam, India," July 18, 2026.
  32. ET EnergyWorld, "Off-site emergency exercise conducted around Kalpakkam nuclear power plant in TN," July 19, 2026.
  33. Press Information Bureau, Government of India, "A New Chapter in India's Nuclear Journey," July 18, 2026.
  34. The Maritime Executive, "Korean Containership with Molten Salt Nuclear Reactor Gets ABS Approval," July 16, 2026.
  35. The Economic Times, "Naveen Jindal Group in talks with US, French tech companies for proposed nuclear projects," July 19, 2026.
  36. ABC News (Australia), "Why India is reopening a nuclear power plant built in the 1960s," July 18, 2026.
  37. AP News, "No radiation leak after 'contamination' events at Africa's only nuclear plant, regulator says," July 16, 2026.
  38. SABC News, "LIVE — Media briefing on incidents at Koeberg Nuclear Power Station," July 19, 2026.
  39. CarbonCredits.com, "Austin-Based SuperCritical Materials Wins DOE License to Turn Seawater Into a New Source of Uranium," July 16, 2026.
  40. Interesting Engineering, "US startup joins nuclear alliance to power hyperscale computing with microreactors," July 17, 2026.
  41. Interesting Engineering, "Nuclear-powered ship design with dual molten salt reactors wins approval from US body," July 18, 2026.
  42. American Nuclear Society, "MIT professor develops method to verify compliance with Outer Space Treaty," July 17, 2026.
  43. Crux Investor, "AI Power Demand & Utility Undercontracting Tighten Uranium Supply as Contract Prices Reach $90 per Pound," May 2026 (background reference).
  44. Sprott Asset Management, "Why uranium stocks could be poised to catch up with fundamentals," July 16, 2026.
  45. Energy Intelligence, "Uranium Spot Price Nosedives $14," July 2026.
  46. Investor's Business Daily, "Cathie Wood Amasses $88 Million Stake In This Falling Nuclear Stock," July 17, 2026.
  47. Malay Mail, "Rockefeller Foundation finds nuclear could reduce power system costs by up to 31pc by 2050," July 18, 2026.
  48. Proactive Investors, "Sprott Asset Management: Why uranium stocks could be poised to catch up with fundamentals," July 16, 2026.

Nuclear Pulse is an independent weekly intelligence briefing. All information is sourced from publicly available industry publications. No investment advice is provided.

© 2026 Nuclear Pulse — Compiled by Tollaskígyó

Jul 12Nuclear Pulse — July 12, 2026

Covering: J
Published: July 12, 2026

Summary

Bangladesh's Rooppur nuclear power plant, the country's first atomic facility, reached a commercial-operations threshold this week, marking a watershed moment for developing-world nuclear ambitions financed and built by Rosatom [1]. Australia and India signed a long-anticipated uranium export agreement during Prime Minister Modi's visit to Canberra, ending years of diplomatic stalemate and opening a major new supply lane into South Asia's reactor buildout [2][3]. The US Nuclear Regulatory Commission granted Westinghouse a path to renew the AP1000 standard design certification ahead of schedule, embedding lessons learned from Vogtle Units 3 and 4 into a template now widely cited for the next generation of large reactors [4]. Private capital continued to flood the sector, with Holtec Nuclear filing for an estimated $2.0 billion IPO and Constellation Energy emerging as the most-discussed equity tied to data-center power demand [5][6]. Iran, meanwhile, refused fresh IAEA access to its nuclear facilities, sharpening the strategic premium that nuclear energy now commands across the diplomatic and energy-security agenda [7].

Geopolitical & Strategic Analysis

The week's signal is unmistakable: nuclear energy has become a foundational instrument of statecraft. The Rooppur milestone is not merely a Bangladesh story — it is the first time a least-developed country has commissioned a commercial nuclear plant financed end-to-end by an extra-regional power (Russia), and it cements Moscow's atomic footprint across South Asia at a moment when Western vendors remain preoccupied with licensing backlogs in their home markets [1]. Meanwhile, the Australia–India uranium accord re-routes a critical mineral flow into New Delhi's fast-expanding fleet and signals that Canberra is willing to use its resource wealth as a strategic lever against Chinese dominance in regional supply chains [2][3]. The deal also implicitly validates India's 2008 nuclear isolation as a thing of the past. In the Middle East, Iran's refusal to grant the IAEA access to its facilities reopens the dossier of enrichment opacity and pushes energy-importing neighbors — from the UAE to Egypt — further toward indigenous atomic programs, with El Dabaa's reactor pressure vessel installation this week a tangible marker of that drift [7][8]. The soft-power implication is that nuclear capability is now a ticket to negotiating table relevance, not merely to baseload power.

Regional Developments

North America. The US Nuclear Regulatory Commission ruled that Westinghouse may apply to renew the AP1000 standard design certification before the current certificate expires, incorporating post-Vogtle operational lessons — a procedural but consequential opening for new large-reactor builds [4]. At Purdue University, the PUR-1 reactor — America's first fully digital nuclear research reactor — began a new round of experiments designed to test autonomous control and instrumentation concepts that could eventually feed into advanced reactor licensing pipelines [9]. In the corporate arena, Holtec Nuclear filed for an estimated $2.0 billion IPO on US exchanges, joining a queue of nuclear services and SMR developers rushing to public capital amid surging power-demand narratives tied to AI infrastructure [5]. State-level momentum continued: Missouri and Connecticut both advanced legislative language endorsing nuclear expansion, and Kansas was identified as the test bed for a radical new reactor design that operators say could break ground within the decade [10][11].

Europe. The UK's Sizewell B power plant secured agreement on a 20-year lifetime extension to 2055, a deal negotiated between the government and EDF that locks in baseload capacity while new-build projects remain in the planning phase [12]. A UK SGE consortium announced a target of deploying 14 GE-Hitachi BWRX-300 small modular reactors on British soil — an ambitious pipeline that, if delivered, would dwarf the country's current civil fleet [13]. Poland's state developer submitted an application for public funding covering three SMR projects, signaling Warsaw's determination to anchor its energy transition on Western small-reactor technology rather than Russian designs [14]. Switzerland, meanwhile, released a study concluding that building a new nuclear power plant would be economically worthwhile under a range of decarbonization scenarios — a striking reversal of the political consensus that took the country out of new-build consideration a decade ago [15]. Separately, a continental heat wave forced output reductions at several European nuclear plants, exposing climate-vulnerability blind spots in fleets designed for milder operating envelopes [16].

Asia. Bangladesh's Rooppur Unit 1 entered the operational news cycle as a flagship of Russia's $13 billion atomic export drive, with the plant projected to cover up to 15% of national electricity demand once both units reach full output [1]. A South Korean 17,000-ton forging press — the only machine of its kind in the world capable of producing seamless reactor pressure vessel cans at the scale required — confirmed it will produce the hearts of ten forthcoming American nuclear reactors, illustrating how Korea has become an irreplaceable node in the Western nuclear supply chain despite the absence of a domestic US equivalent [17]. In the financial sphere, NTPC — India's largest power generator — tendered for consultants to identify overseas uranium mining assets, paralleling the Australia deal and signaling a much broader Indian scramble for fuel security [18].

Middle East & Africa. Egypt marked the installation of the reactor pressure vessel in El Dabaa Unit 2, with Russian and Egyptian officials framing the milestone as a step toward first criticality in 2027 [8]. Rosatom and Egypt's Ministry of Electricity confirmed they are in early discussions on additional nuclear units beyond the four already contracted, which would extend Moscow's footprint at the site into the 2040s [19]. The geopolitical stakes of regional nuclear capability were underscored again by Iran's refusal to allow IAEA inspectors access to declared facilities, a move that drew sharp criticism from Western capitals and renewed focus on enrichment-monitoring regimes [7].

Technology & Innovation

Westinghouse's path to AP1000 design certification renewal is a quiet but pivotal technology event: it streamlines the path for new large-reactor builds by absorbing Vogtle 3 and 4 lessons — construction sequencing, modular fabrication, and digital I&C modernization — into a single reference design that future utilities can reference without re-licensing from scratch [4]. The Purdue PUR-1 digital reactor continues to push the frontier of fully autonomous instrumentation, with the current experimental campaign focused on machine-learning-assisted anomaly detection in real-time neutron flux measurements [9]. In microreactor commercialization, a US firm launched what is described as the first commercial nuclear-powered satellite — a coffee-mug-sized CubeSat using betavoltaic hydrogen technology — opening a new applications market beyond terrestrial baseload [20]. Industry–data-center coupling advanced as well: GridMarket and Deployable Energy announced a 3 GW pipeline of microreactors targeted at data-center customers, the largest disclosed commercial pipeline of its kind [21].

Fusion Research

No new public-domain plasma records, magnetic-confinement milestones, or private fusion venture breakthroughs surfaced in the seven-day window covered by this issue. The Helion, Commonwealth Fusion, and TAE Power reactors continue along their previously disclosed construction and confinement-test timelines; no updated net-energy or triple-product claims were made by any of the three during the reporting period.

Market & Economic Intelligence

U3O8 spot prices remained in the upper band of the post-2024 trading range, with contract prices reported at or near $90 per pound and term-deal premiums tightening as utility under-contracting intersects with AI-driven load growth [22]. The Australian–Indian uranium accord is expected to provide both volumes and price discipline to a market that has been structurally short since 2023; analysts at Shaw and Partners have projected a supercycle scenario with prices potentially reaching $200 per pound by the end of the decade, though mainstream consensus remains closer to a $100–$120 band [23][24]. On the equity side, Holtec's $2 billion IPO filing, Holtec's existing SMR-300 pipeline, and Constellation Energy's continued leadership in the data-center power thesis drove a broad rerating of nuclear-exposed equities [5][6]. Cameco, SMR developer NuScale, and diversified utility plays remained the most-discussed names; the Motley Fool and Simply Wall St both highlighted Constellation and a small set of Indian-exposed names as the most credible ways to participate in the demand pull from New Delhi's reactor program [6][25]. Holtec's filing also signals a broader IPO pipeline: nuclear-services and fuel-cycle companies that built balance sheets during the 2023–2025 squeeze are now looking to public capital to fund deployment.


Sources

All 25 sources
  1. The Economic Times, "A nuclear debut in Bangladesh tests developing world's atomic shift," July 12, 2026.
  2. Reuters, "Australia, India strike deal on uranium exports during Modi visit," July 9, 2026.
  3. World Nuclear News, "Australia agrees to export uranium to India," July 9, 2026.
  4. World Nuclear News, "NRC exempts Westinghouse from design certification renewal rule," July 10, 2026.
  5. Renaissance Capital, "Holtec Nuclear files for an estimated $2.0 billion IPO," July 10, 2026.
  6. The Motley Fool, "The Nuclear Energy Comeback Is Real. These 3 Energy Stocks Are the Best Ways to Play the Revival," July 11, 2026.
  7. The New Arab, "Iran refuses to allow IAEA access to nuclear facilities," July 11, 2026.
  8. World Nuclear News, "Reactor vessel installed in El Dabaa's second unit," July 9, 2026.
  9. Tech Xplore / Interesting Engineering, "At the nation's only all-digital nuclear reactor, engineers conduct the first experiments of their kind in the US," July 11, 2026.
  10. Springfield News-Leader, "Missouri pushes for more nuclear energy to power the future," July 11, 2026.
  11. OilPrice.com, "Kansas Becomes Testing Ground for a Radical Nuclear Reactor Design," July 11, 2026.
  12. World Nuclear News, "Lifetime extension agreed for Sizewell B to 2055," July 9, 2026.
  13. World Nuclear News, "SGE team targets 14 BWRX-300 SMRs UK," July 8, 2026.
  14. World Nuclear News, "Polish developer applies for state funding for three SMR plants," July 8, 2026.
  15. Bluewin.ch, "According to a study, building a new nuclear power plant is worthwhile for Switzerland," July 12, 2026.
  16. Energy News Beat, "Europe's Nuclear Plants Can't Beat the Heat," July 10, 2026.
  17. Autonocion.com, "A 17,000-ton press in South Korea… will forge the hearts of America's next 10 nuclear reactors," July 11, 2026.
  18. IndexBox, "NTPC Tenders for Consultants to Identify Uranium Mines Abroad," July 11, 2026.
  19. Russia's Pivot to Asia, "Russia, Egypt Discussing Additional Nuclear Power Plants," July 11, 2026.
  20. World Nuclear News, "First commercial nuclear-powered satellite launched," July 10, 2026.
  21. MLQ.ai, "GridMarket and Deployable Energy Partner on 3GW Microreactor Pipeline for Data Centers," July 11, 2026.
  22. Crux Investor, "AI Power Demand & Utility Undercontracting Tighten Uranium Supply as Contract Prices Reach $90 per Pound," May 6, 2026.
  23. Investing News Network, "Australia-India uranium deal opens major new market for local producers," July 10, 2026.
  24. Investing News Network, "Uranium Stocks Investment 2026: Nuclear Energy Renaissance & Price Forecast," July 10, 2026.
  25. Simply Wall St, "Nuclear Energy Stocks With Real Exposure to India's Reactor Buildout," July 11, 2026.

Nuclear Pulse is an independent weekly intelligence briefing. All information is sourced from publicly available industry publications. No investment advice is provided.

© 2026 Nuclear Pulse — Compiled by Tollaskígyó

Jul 5Nuclear Pulse — July 5, 2026

Covering: J
Published: July 5, 2026

Summary

The United States achieved its presidential goal of three reactor criticalities by Independence Day, as Deployable Energy's Unity microreactor reached initial criticality at Idaho National Laboratory just ahead of the July 4 deadline [1]. In Europe, a consortium led by Poland's SGE outlined plans for 14 GE Vernova Hitachi BWRX-300 SMRs across three UK sites, marking the largest private SMR deployment proposal to date [2]. The uranium market felt the friction of supply constraints, with Cameco suspending operations at its Cigar Lake mine due to sulphuric acid shortages at the McClean Lake mill, even as long-term contract prices hit a historic high of $97 per pound U3O8 [3][4]. Regulatory turbulence surfaced on multiple fronts: the NRC proposed eliminating the ALARA radiation safety principle, a court dismissed a lawsuit to block the Palisades restart, and Finland's LDR-50 SMR completed an international safety review [5][6][7]. A startup unveiled a 3D-printed thorium reactor module aimed at AI data centers, signalling that the nuclear-AI nexus is driving increasingly unconventional reactor architectures [8].

Geopolitical & Strategic Analysis

The mood of the nuclear industry this week is one of acceleration tempered by friction. The United States is visibly racing to translate executive orders into concrete milestones — the triple-criticality achievement is symbolic, but it demonstrates that the DOE's accelerated licensing pathway for microreactors can produce results within a single year [1]. Yet the simultaneous NRC proposal to eliminate the ALARA (As Low As Reasonably Achievable) radiation safety principle reveals a regulatory philosophy shift that prioritises deployment speed over precautionary doctrine [5]. This tension between urgency and safety culture will define the American nuclear renaissance: the industry cannot build fast enough to satisfy AI-driven power demand, but dismantling foundational safety frameworks risks eroding the public trust that nuclear energy uniquely requires.

Europe's strategic posture is more collaborative. The SGE-led BWRX-300 consortium — spanning Poland, the UK, South Korea, Canada, and Google Cloud — represents a new model of multinational, privately financed nuclear deployment that bypasses traditional single-state procurement [2]. Finland's joint safety review of the LDR-50 district heating reactor, conducted with regulators from five nations, signals that European nuclear cooperation is deepening at the technical level even as political debates about energy sovereignty continue [7]. Canada's new nuclear strategy, with Saskatchewan uranium at its centre, positions the country as the indispensable fuel supplier for the Western alliance's nuclear ambitions — a role that carries both economic opportunity and strategic dependency implications [9][10].

The uranium supply chain is where geopolitics meets geology. The Cigar Lake suspension underscores how fragile the back end of the fuel cycle remains: a single sulphuric acid supply disruption at a mill can idle the world's highest-grade uranium mine [3]. With the US expanding domestic enrichment through a $1.07 billion deal and long-term prices at historic highs, the race to rebuild Western fuel self-sufficiency is no longer aspirational — it is an active strategic contest against the clock [4][11].

Regional Developments

The United States marked a watershed week. Deployable Energy's Unity demonstration reactor achieved initial criticality at the National Reactor Innovation Center at Idaho National Laboratory, fulfilling the presidential goal of three DOE-authorised microreactor criticalities by July 4, 2026 [1]. The Palisades Nuclear Plant in Michigan moved closer to restart as Holtec International announced the completion of all major project milestones, transitioning to final testing and operational readiness work, while a court dismissed a lawsuit seeking to halt the reopening [6][12]. The DOE reported that its executive order-driven nuclear renaissance is "in full swing" one year on, with the agency hitting its SMR deployment targets [13][14]. On the regulatory front, the NRC proposed changing the longstanding ALARA radiation protection rule, a move The Hill described as eliminating a "longtime radiation safety principle" — a decision that will attract significant public comment [5]. Radiant Nuclear delivered TRISO fuel to Idaho National Laboratory for full-power testing of its Kaleidos microreactor, adding another technology to the INL demonstration pipeline [15]. A fire on the property of Seabrook Station Nuclear Power Plant was extinguished without impact to the reactor, and safety inspection lapses were reported at a South Carolina nuclear plant [16][17]. On the state level, Alaska and Arizona continued pursuing nuclear energy options, while opponents rallied against nuclear proposals in Massena, New York [18][19][20].

The standout development was the SGE-led consortium's plan to deploy 14 BWRX-300 SMRs across three UK sites, with Samsung C&T, Laing O'Rourke, Aecon Group, and Google Cloud as partners — a privately financed project that could reshape the UK's nuclear landscape without direct government capital [2]. Finland's nuclear regulator published the summary report of a Joint Early Review for Steady Energy's LDR-50 district heating SMR, with regulators from the Czech Republic, Poland, Sweden, and Ukraine participating, reinforcing the pan-European dimension of SMR safety assessment [7]. The IMO Secretary-General endorsed nuclear's role in decarbonising shipping, signalling that maritime nuclear propulsion is moving from speculation to regulatory agenda [21]. Italy's nuclear renaissance continued to generate interest, with new uranium exploration activity reported in connection with Europe's broader nuclear ambitions [22].

Canada unveiled a new nuclear strategy that emphasises expanding both reactor capacity and uranium production, with Saskatchewan's Athabasca Basin positioned as the cornerstone of the country's fuel supply ambitions [9][10]. The Cigar Lake mine suspension — triggered by sulphuric acid availability challenges at Orano's McClean Lake mill — highlighted the supply chain vulnerabilities in the world's richest uranium producing region [3]. IAEA missions to Uzbekistan reported significant progress in legal frameworks, training, and nuclear safety, indicating that Central Asian nuclear newcomer programmes are advancing steadily [23].

No confirmed nuclear energy developments from this region met the seven-day publication window for this issue.

Technology & Innovation

The most provocative technology story of the week came from a startup unveiling a 3D-printed nuclear reactor module designed to power AI data centres, described as "the world's first subcritical, solid-state, factory-built thorium nuclear reactor" [8]. While the claim of a subcritical reactor generating useful power is thermodynamically questionable and likely refers to a subcritical multiplication or accelerator-driven configuration, the design illustrates how the AI-data-centre power crisis is pushing entrepreneurs toward radical reactor architectures that would have been dismissed as fringe only two years ago. The use of thorium and 3D-printed components signals a convergence of advanced manufacturing with nuclear engineering that could dramatically reduce construction timelines if the physics can be validated.

Radiant Nuclear's TRISO fuel delivery to INL for the Kaleidos microreactor experiment represents a more conventional but equally important milestone [15]. TRISO-coated particle fuel is the enabling technology for high-temperature gas-cooled reactors and microreactors, and its successful delivery to a national laboratory for full-power testing demonstrates that the US fuel supply chain for advanced reactors is maturing in parallel with reactor development. The AMPERA milestone announced via PR Newswire suggests continued progress in advanced manufacturing partnerships for nuclear components, though details were limited [24].

Fusion Research

No fusion-specific developments met the seven-day publication window for this issue. The absence of major fusion news this week is consistent with the field's typical publication cadence, where breakthrough announcements tend to cluster around conference schedules and quarterly venture updates.

Market & Economic Intelligence

The uranium market is experiencing a historic moment. Long-term contract prices reached $97.00 per pound U3O8, a new all-time high, driven by the convergence of AI data centre power demand and persistent utility undercontracting [4]. This price level reflects not just current demand but anticipated requirements from the wave of reactor restarts and new builds announced over the past year. The spot market context is more volatile — earlier in 2026, spot prices surged past $100 before correcting — but the long-term contract price is the more strategically significant indicator, as it reflects committed multi-year procurement decisions rather than speculative trading [4][25].

The Cigar Lake suspension introduces immediate supply-side pressure [3]. Cigar Lake is the world's highest-grade uranium mine, and even a temporary outage tightens an already constrained market. The cause — sulphuric acid availability at the McClean Lake mill — illustrates how upstream chemical supply chains can become the binding constraint on uranium production. The US $1.07 billion domestic enrichment expansion deal reinforces the federal commitment to rebuilding the full fuel cycle on American soil, reducing dependence on foreign enrichment providers [11]. Saskatchewan's centrality in Canada's nuclear strategy further cements the Athabasca Basin as the strategic uranium reserve for the Western alliance [10]. Uranium producers are outperforming broader energy equities, with the supply-driven narrative dominating investor attention as nuclear energy stocks tied to data centre demand continue to attract capital flows [26][27][28].


Sources

All 0 sources

Nuclear Pulse is an independent weekly intelligence briefing. All information is sourced from publicly available industry publications. No investment advice is provided.

© 2026 Nuclear Pulse — Compiled by Tollaskígyó

Jun 28Nuclear Pulse — June 28, 2026

Covering: J
Published: June 28, 2026

Summary

The United States fired the starting gun on a long-awaited nuclear buildout this week, with the Department of Energy unveiling a $17.5 billion loan program targeting ten new large-scale reactors, a move that immediately drew commercial validation as Constellation Energy signed a landmark 15-year power purchase agreement with Walmart to supply nuclear electricity from its Dresden plant in Illinois. Canada launched its first national Nuclear Energy Strategy, outlining plans for up to ten new reactors by 2040, while seven Ontario First Nations secured a historic $715 million equity stake in the Darlington SMR project, making it the G7's first grid-scale small modular reactor with Indigenous ownership. Sweden made its largest nuclear commitment in four decades by selecting Rolls-Royce SMRs for the Videberg site, and India's Adani Group announced an ambitious 10 GW nuclear target by 2035, signaling that the nuclear renaissance has moved decisively from rhetoric to capital deployment.

Geopolitical & Strategic Analysis

The dominant signal this week was the convergence of state financing with commercial demand — governments are no longer merely cheerleading nuclear energy; they are underwriting it. The DOE's $17.5 billion loan facility is explicitly designed to de-risk the supply chain for AP1000 reactor builds, addressing the perennial bottleneck that has stalled nuclear construction in the West: the gap between regulatory approval and bankable project economics. The Walmart-Constellation deal is equally significant because it demonstrates that nuclear demand has broken free of the AI data center narrative — retail and industrial consumers are now contracting directly for nuclear baseload, validating the technology as a mainstream commercial energy product rather than a niche play for hyperscalers.

Meanwhile, the geopolitical chessboard shifted on multiple fronts. Canada's national strategy explicitly positions nuclear and uranium capacity as instruments of energy sovereignty, with Ottawa signaling intent to expand both domestic reactor fleets and uranium export capabilities. The IAEA-Iran interim inspection deal, while fragile, represents a tentative de-escalation in one of the world's most volatile nuclear flashpoints. Estonia's parliamentary passage of nuclear legislation adds another Baltic state to the growing list of European nations formally opening the door to nuclear, while Adani's 10 GW Indian target underscores how rapidly the non-Western nuclear buildout is accelerating. The underlying strategic current is clear: nuclear technology is being deployed as soft power, with Russia's Rosatom exporting SMRs, China achieving fusion magnet independence, and Western nations racing to offer competitive reactor packages through Rolls-Royce, Holtec-EDF partnerships, and AtkinsRéalis CANDU licensing in the United States [1][2][3][4][5][6][7][8][9][10][11][12][13][14][15][16][17][18][19][20][21][22][23][24][25][26][27][28].

Regional Developments

North America: The DOE's $17.5 billion loan program dominated the week, with Energy Secretary Chris Wright touring Idaho National Laboratory to celebrate what he called a "golden age" of nuclear power. The loans are structured to support the supply chain for ten new large reactors, likely AP1000 designs, addressing the manufacturing and construction bottlenecks that have historically driven nuclear project costs upward. Commercial demand materialized quickly: Constellation Energy signed a 15-year agreement with Walmart to supply emissions-free nuclear power from the Dresden generating station in Illinois, marking the retail giant's first nuclear PPA and demonstrating that corporate clean energy procurement has expanded well beyond tech-sector data centers. New York released an advanced nuclear policy paper targeting 5 GW of new capacity and launched a Nuclear Reliability Backbone initiative, while Santee Cooper moved forward with restart plans for the abandoned V.C. Summer project in South Carolina. NANO Nuclear Energy's KRONOS microreactor program entered formal NRC review with the University of Illinois Urbana-Champaign, and Terrestrial Energy reached a reactor siting agreement with Texas A&M. US uranium production rose to a nine-year high, and the IAEA released its first public tool to map the world's spent nuclear fuel inventory [1][2][5][6][9][10][17][22][25][27][28].

Canada's week was transformative. The federal government launched its national Nuclear Energy Strategy on June 22, with Energy Minister Hodgson outlining a "nuclear renaissance" targeting up to ten new reactors by 2040. The strategy explicitly links domestic reactor expansion with uranium export growth, positioning Canada as a full-cycle nuclear supplier. The most striking development came the following day, when seven Ontario First Nations signed a historic $715 million equity partnership with Ottawa and the provincial government to co-own the Darlington BWRX-300 SMR project — the G7's first grid-scale SMR and the first Indigenous equity stake in a nuclear reactor. AtkinsRéalis simultaneously initiated US licensing for CANDU technology, targeting the American market, and the Wheeler River uranium mining project received regulatory go-ahead [3][4][7][8][11][12][16].

Europe: Sweden made the week's most consequential European nuclear decision in a generation, selecting Rolls-Royce SMRs for the Videberg site in what marks the country's largest nuclear commitment since the early 1980s. The Swedish government took a 60% stake in the project company via Vattenfall, committing to three SMRs that will add substantial baseload capacity. In the United Kingdom, Holtec and EDF jointly submitted proposals for new nuclear projects at Cottam and other sites, while the UK SMR programme at Wylfa reported strong progress on British content contracts. Estonia's parliament passed legislation enabling nuclear energy development, making it the latest European nation to formally open the nuclear door. The UK also deepened its fusion partnership with the United States following the King's Address to Congress, and UKAEA increased innovation funding for fusion research. However, the week's most urgent European story was operational: a record heatwave forced EDF to take multiple French nuclear reactors offline as river temperatures exceeded cooling water limits, with Hungary's Paks plant also cutting output. The events underscored the vulnerability of the continent's nuclear fleet to climate-driven thermal stress, raising serious questions about adaptive capacity in a warming world [5][6][13][14][18][19][20][26].

Asia: India's Adani Group announced a sweeping 10 GW nuclear power target by 2035, with billionaire Gautam Adani positioning the conglomerate as a major player in the country's civilian nuclear sector. The announcement, made at the Adani Group AGM, links nuclear capacity expansion to the broader energy security and AI infrastructure push. In Japan, the IAEA Director General visited to support nuclear energy development and safety cooperation, while Japanese collaboration with the IAEA on SMR promotion continued. South Korea's HanmiGlobal established a US unit targeting SMR projects, and Rosatom commenced construction of what it claims will be the world's first export SMR plant. The Philippines signaled renewed interest in reviving its long-shuttered Bataan nuclear power plant. The broader Asian theme is one of accelerated nuclear adoption driven by AI-driven electricity demand projections and energy security imperatives [9][10][21][22][23].

Middle East & Africa: The IAEA-Iran interim deal dominated regional nuclear headlines. IAEA Director General Grossi stated that inspections of Iran's nuclear sites "are going to happen" under the agreement, though Tehran pushed back, insisting that inspector access would come only after a final deal is concluded. The ambiguity highlights the fragility of the arrangement. In Egypt, the electricity minister reviewed progress at the Dabaa nuclear power plant, and nuclear energy was identified as key to Africa's industrialization trajectory in discussions covered by Chinese state media, reflecting Beijing's continued strategic engagement on the continent [11][12].

Technology & Innovation

The SMR pipeline advanced on multiple fronts. Rolls-Royce SMR opened a new £12 million Pioneer Works facility in Derby, establishing a dedicated manufacturing and testing hub for its reactor program and signaling the company's transition from design to industrial production. Deep Fission, a US startup proposing mile-deep borehole reactors, reported a customer pipeline of 18.5 GW, driven primarily by data center interest in the concept's inherent safety profile — the surrounding rock provides containment and the water column supplies pressure, eliminating the need for a conventional containment dome. NANO Nuclear's KRONOS MMR microreactor entered formal NRC review, a significant regulatory milestone for transportable nuclear technology. Hadron Energy expanded its engineering team to advance the Halo microreactor, and Oklo disclosed AI-driven reactor design optimization strategies.

In the fuel cycle, US uranium production reached a nine-year high, and the IAEA launched the first public global spent nuclear fuel mapping tool, a transparency initiative that could reshape public discourse around waste management. The NEA announced progress in nuclear fuel and materials science, and Los Alamos National Laboratory released workforce planning software for nuclear reactor projects, addressing the industry's critical human capital bottleneck. AtkinsRéalis initiated US licensing for CANDU technology, marking the first serious attempt to introduce a non-light-water reactor design into the US market in decades, while Valar Atomics achieved criticality in a DOE reactor pilot program [3][4][7][15][17][22][25][27][28].

Fusion Research

The fusion sector delivered one of its most consequential weeks on record. General Fusion announced that its LM26 magnetized target fusion machine achieved compressional plasma heating to 8.4 million degrees Celsius (0.72 keV), effectively tripling the plasma temperature through compression alone and approaching the critical 1 keV milestone. The company simultaneously announced a $107.5 million PIPE investment as its SPAC vehicle (SVAC) moves toward a merger vote on July 6. The milestone was accompanied by a framework agreement with Renexia for the commercial deployment of fusion power plants in Italy, marking one of the first concrete commercial siting agreements in the fusion industry.

China achieved a parallel breakthrough, completing and unveiling the world's largest superconducting magnet for fusion reactors at the Hefei facility. The magnet system is reported as 100% domestically produced, eliminating a critical supply chain dependency and underscoring China's determination to achieve fusion energy sovereignty. The component is destined for China's "artificial sun" project, which reached a new engineering milestone this week. Helion Energy secured additional licenses from Washington state for its Malaga fusion plant — widely described as the world's first nuclear fusion power plant to receive regulatory go-ahead — and reported visible construction progress on the generator building. Thea Energy partnered with Nvidia and Synopsys to develop a digital twin of its Helios stellarator concept, bringing AI-accelerated design to stellarator optimization. The Fusion Industry Association released its 2026 Supply Chain Report, showing a 24% jump in supply chain spending, while the DOE's finalized fusion strategy targets commercial energy by the 2030s. General Atomics received a $20 million tax credit to advance fusion blanket testing in California, and the UK fusion sector reported accelerated industrial scale-up with surging private investment. AI-driven fusion design optimization emerged as a crosscutting theme, with multiple groups reporting breakthroughs in plasma modeling, diagnostic recovery, and design bottleneck resolution [5][6][13][14][18][19][20][21][22][23][24].

Market & Economic Intelligence

Uranium spot prices held at approximately $85 per pound U3O8 through June, maintaining the narrow trading range established since early April following the cooling of a speculative rally earlier in the year. The price stability reflects a market in equilibrium between muted utility spot buying — most utilities remain covered by long-term contracts — and structural supply constraints driven by the Russian import ban and growing production gaps. Uranium Energy Corporation commenced production at its Burke Hollow ISR facility in Texas, contributing to US uranium output reaching a nine-year high, though the company's stock faced pressure from broader market jitters. NexGen Energy's high-grade Rook I uranium deposit advanced, and multiple uranium explorers reported technical progress, though share prices across the sector remained volatile as investors weighed near-term oversupply against long-term deficit projections.

The DOE's $17.5 billion loan announcement provided the week's largest market signal, with nuclear stocks and SMR-focused companies rallying on the news. The Constellation-Walmart PPA demonstrated that nuclear power pricing has reached a level competitive with other clean energy sources for large commercial consumers, validating the commercial case beyond AI-driven demand. Barclays published a research note outlining the top nuclear energy stocks positioned for the AI boom, and ETF tracking showed the NUKZ nuclear ETF gaining on commercial SMR deal momentum. The FIA's 2026 supply chain report documented a 24% jump in fusion industry supply chain spending, indicating that private capital is flowing into the fusion sector at an accelerating pace. Blue Energy proposed a $6.24 billion gas-plus-nuclear hybrid plant in Victoria County, Texas, reflecting a trend toward blended energy projects that pair nuclear baseload with flexible gas generation [1][2][8][9][10][15][17][22][25][27].


Sources

All 28 sources
  1. "Energy Dept. Unveils $17.5 Billion Plan to Kick-Start New Nuclear Plants" — The New York Times, June 23, 2026
  2. "US announces $17.5 billion in loans for nuclear power supply chain" — Reuters, June 23, 2026
  3. "Government of Canada launches Nuclear Energy Strategy" — canada.ca, June 22, 2026
  4. "Ontario Reaches Historic First Nations Equity Partnership to Build the G7's First Small Modular Reactors" — ontario.ca, June 23, 2026
  5. "Sweden has agreed first financing package for new nuclear reactors, PM says" — Reuters, June 25, 2026
  6. "Sweden Takes 60% Stake in Videberg Kraft to Launch Three SMRs" — energynews.pro, June 26, 2026
  7. "Canada aims to grow nuclear and uranium capacity, at home and abroad" — World Nuclear News, June 23, 2026
  8. "Constellation Energy to supply nuclear power to Walmart facility under 15-year deal" — Reuters, June 23, 2026
  9. "Adani aims to be major player in India's nuclear power sector, targeting 10 GW by 2035" — Reuters, June 24, 2026
  10. "Indian Billionaire Gautam Adani Plans Nuclear Power Project In Energy Expansion Drive" — Forbes, June 24, 2026
  11. "UN nuclear chief says Iran inspections will happen, Tehran says after deal" — Al Jazeera, June 24, 2026
  12. "Iran deal grants access to nuclear inspectors, IAEA chief says" — Reuters, June 26, 2026
  13. "Europe's heatwave curbs French nuclear plants" — Reuters, June 24, 2026
  14. "France takes nuclear reactors offline amid record heatwave" — Euronews, June 25, 2026
  15. "Nuclear Stocks And Small Modular Reactors Ace Big Wins. A DOE Deadline Looms." — Investor's Business Daily, June 26, 2026
  16. "AtkinsRéalis kicks off US licensing for CANDU technology" — World Nuclear News, June 24, 2026
  17. "NANO Nuclear's KRONOS MMR Program Advances as U.S. NRC Initiates Formal Review Activities" — TMX Newsfile, June 25, 2026
  18. "General Fusion achieves 8.4 million °C plasma heating, nearing key 1 keV milestone with LM26 fusion machine" — Pluang, June 22, 2026
  19. "General Fusion LM26 milestone and $107.5M PIPE as SVAC moves to close merger" — Stock Titan, June 24, 2026
  20. "China Achieves 100% Domestically Produced Nuclear Fusion Superconducting Magnets in 'Artificial Sun' Breakthrough" — Pandaily, June 28, 2026
  21. "World's first nuclear fusion power plant receives go-ahead in Washington state" — Yahoo, June 25, 2026
  22. "Estonia's Parliament Passes Legislation That Paves Way For Nuclear Energy" — NucNet, June 24, 2026
  23. "Holtec and EDF submit UK SMR project proposal" — World Nuclear News, June 24, 2026
  24. "FIA Launches 2026 Fusion Industry Supply Chain Report" — Fusion Industry Association, June 23, 2026
  25. "Santee Cooper steams ahead with plans to restart V.C. Summer nuclear project" — The State, June 26, 2026
  26. "Hungarian nuclear power plant cuts output in record heatwave" — TVP World, June 27, 2026
  27. "IAEA Releases First Public Tool to Map the World's Spent Nuclear Fuel" — International Atomic Energy Agency, June 22, 2026
  28. "US Uranium Production Rises Again to a Nine-Year High" — Discovery Alert, June 26, 2026

Nuclear Pulse is an independent weekly intelligence briefing. All information is sourced from publicly available industry publications. No investment advice is provided.

© 2026 Nuclear Pulse — Compiled by Tollaskígyó

Jun 21Nuclear Pulse — June 21, 2026

Covering: J
Published: June 21, 2026

Summary

This week marked a pivotal convergence of regulatory breakthroughs and geopolitical maneuvering across the nuclear sector. Helion Energy became the first company in the world to secure operational licenses for a fusion power plant, while TerraPower formally entered the UK's Generic Design Assessment process with its Natrium reactor — signaling that advanced reactor designs are now crossing regulatory thresholds on multiple continents simultaneously [1][2]. In Europe, Estonia's parliament passed a comprehensive nuclear energy law and the UK struck a £210 million uranium supply deal with Urenco to sever Ukraine's dependence on Russian nuclear fuel [3][4]. The uranium market remained firm at approximately $86 per pound spot with long-term contract prices at 14-year highs, driven by supply cuts in Kazakhstan and Western scarcity [5].

Geopolitical & Strategic Analysis

The overarching mood this week was one of strategic decoupling — Western nations are systematically dismantling decades-old nuclear dependencies on Russia and China, replacing them with allied supply chains and bilateral technology partnerships. The UK's £210 million export-finance deal for Urenco to supply enriched uranium to Ukraine's Energoatom is perhaps the most concrete example: it eliminates Moscow's last supply-chain leverage over Ukraine's VVER reactor fleet for at least two years, removing a quiet but persistent tool of coercion from any future negotiation framework [4]. Meanwhile, Bulgaria secured an EU sanctions derogation to keep the Kozloduy nuclear plant running with essential Russian-supplied components — a pragmatic acknowledgment that full decoupling remains impossible for some Eastern European operators in the short term [6]. On the expansionist front, Rosatom signed a binding intergovernmental agreement with Laos for peaceful nuclear energy use, deepening Russia's nuclear diplomacy in Southeast Asia [7]. South Korea's KHNP celebrated the first anniversary of its $18 billion Dukovany contract with a high-level CEO visit to the Czech Republic, reinforcing Seoul's ambition to become a premier nuclear exporter in the European market [8]. The pattern is unmistakable: nuclear technology is being deployed as soft power, with the United States, South Korea, and Russia all competing to anchor their reactor designs in allied or partner nations.

Regional Developments

North America

The United States saw a flurry of regulatory and project-level advances. Elementl Power signed an Early Works Agreement with GE Vernova Hitachi Nuclear Energy to deploy BWRX-300 small modular reactors at a proposed 1.5 GW site in Meigs County, Ohio, targeting construction start in 2030 and first-unit completion in 2034 [9]. The NRC launched an environmental review of Holtec's new-build plans for the Palisades site, adding to the agency's already heavy advanced-reactor workload [10]. Separately, the NRC proposed a new licensing framework specifically tailored for microreactors, a regulatory innovation that could dramatically lower the barrier to entry for ultra-small nuclear systems [11]. The Dow-X-energy Seadrift project in Texas reached a major milestone with the NRC's Finding of No Significant Impact on its Environmental Assessment, advancing the $2.4 billion Long Mott Generating Station — an 80 MWe high-temperature gas-cooled reactor designed to supply both electricity and industrial steam to Dow's chemical operations [12]. In Iowa, state regulators approved a generating certificate for NextEra Energy's restart of the Duane Arnold nuclear plant, though federal NRC approvals remain the critical-path hurdle [13].

Europe

Estonia's parliament passed the Nuclear Energy and Safety Act by a decisive 63-to-10 vote, establishing a phased licensing system and clearing the way for Fermi Energia's planned 600 MWe BWRX-300 SMR project [3]. The law limits technology choices to "solutions that have already been proven in practice" and establishes a national decommissioning fund — a conservative but forward-looking framework. In the UK, TerraPower's Natrium reactor officially entered Step 1 of the Generic Design Assessment process, with the company establishing its first international subsidiary in Britain [2]. The ONR will leverage the Atlantic Partnership for Advanced Nuclear Energy framework signed between the UK and US governments last year, enabling enhanced regulatory cooperation. Sizewell C faced parliamentary scrutiny over cost-overrun transparency, with MPs challenging the project's infrastructure progress and financial disclosures [14]. Hinkley Point C achieved a notable construction milestone — the second reactor pressure vessel was installed 30% faster than the first unit, demonstrating tangible learning-curve benefits [15]. In Spain, the nuclear safety regulator CSN began evaluating a lifetime extension for the Almaraz nuclear power plant, a critical decision for Spain's energy transition trajectory [16].

Asia

India's Atomic Energy Regulatory Board approved a 10-year life extension for Tarapur Atomic Power Station Units 1 and 2 — the world's oldest operating commercial nuclear reactors, commissioned in 1969 [17]. The approval follows an extensive modernization program and reinforces India's commitment to maximizing the value of its existing fleet. Meanwhile, the fifth unit of the Kudankulam nuclear power project is likely to be operational by year-end, according to Indian officials [18]. In South Korea, KHNP's CEO visited the Czech Republic to review progress on the $18 billion Dukovany project, now at its one-year anniversary milestone with groundbreaking targeted for 2029 [8].

Middle East & Africa

Rosatom's binding intergovernmental agreement with Laos, signed June 15 in Moscow, represents the corporation's most substantive legal commitment in the country after a decade of memoranda and preliminary roadmaps [7]. The agreement initiates the process for introducing nuclear power to the Southeast Asian nation, expanding Rosatom's geographic footprint. In Ukraine, the Zaporizhzhia Nuclear Power Plant experienced its 20th external power supply disruption since the start of the war, underscoring the persistent vulnerability of the facility despite IAEA monitoring [19].

Technology & Innovation

The NRC's proposal of a dedicated microreactor licensing framework represents a significant regulatory innovation, potentially creating a streamlined pathway for ultra-small reactors that have fundamentally different risk profiles than traditional gigawatt-scale plants [11]. This aligns with the broader trend of right-sizing regulation to match technology — the same principle that underpinned the ADVANCE Act of 2024, which classified fusion under a byproduct material framework rather than the fission reactor paradigm. In the UK, the GDA process for TerraPower's Natrium reactor will benefit from enhanced international regulatory cooperation under the Atlantic Partnership, potentially creating a template for parallel US-UK licensing of advanced reactor designs [2]. The Dow-X-energy Seadrift project's FONSI determination is notable not only for advancing the first industrial SMR application but for reviving high-temperature gas-cooled reactor technology that was abandoned in the United States in 1989 [12].

Fusion Research

Helion Energy's securing of Radioactive Materials and Radioactive Air Emissions licenses from the Washington State Department of Health marks a historic first: no company has ever before obtained the regulatory approvals needed to operate a fusion power plant [1]. The licenses confirm that Helion's Orion facility in Malaga, Washington, meets safety standards for fusion operations, enabling construction of the generator building where earthwork began in spring 2026. The regulatory pathway was enabled by the ADVANCE Act of 2024's classification of fusion under a byproduct material framework, alongside particle accelerators and hospitals rather than fission reactors. General Atomics announced a collaboration with the DOE to design the Fusion Blanket Component Test Facility — the first full-scale test facility for fusion blankets, the lithium-based systems that capture fusion energy and breed tritium [20]. General Fusion's SPAC merger with Spring Valley Acquisition Corp. III cleared SEC review, setting up a July 6 shareholder vote on the roughly $1 billion deal that would make it one of the few pure-play fusion companies on a public exchange [21]. Type One Energy appointed former bp CEO Bernard Looney to its board as the stellarator developer targets commercial fusion by 2034 [22]. Europe launched Project WISER under EUROfusion to advance stellarator research, complementing the Wendelstein 7-X program [23]. The DOE released its finalized Fusion Science and Technology Roadmap, providing a strategic framework for accelerating commercial fusion power [24].

Market & Economic Intelligence

The uranium market remains in a state of structural tightening. Spot prices held at approximately $86 per pound U3O8, while long-term contract prices reached $90 per pound in Q1 2026 — their highest level since 2008 [5]. The drivers are unmistakable: Kazakhstan's 10% production cut, Niger's SOMAÏR nationalization, and Western utilities scrambling to secure non-Russian supply chains. The IAEA Board of Governors meeting in Vienna on June 8-12 disclosed that 440 kilograms of highly enriched uranium in Iran cannot be verified, adding a geopolitical risk premium to the market [5]. Purepoint Uranium Group noted that the underlying supply-demand balance continues to tighten, with Western uranium scarcity driving aggressive contract activity [25]. The $2.4 billion Seadrift SMR project and Elementl Power's 1.5 GW Ohio ambition signal that private capital is flowing into nuclear deployment at meaningful scale, not merely into exploration or R&D [9][12].


Sources

All 25 sources
  1. Helion Energy, "Helion clears key regulatory milestone on the path to building and operating the world's first fusion power plant," June 16, 2026 — helionenergy.com
  2. World Nuclear News, "TerraPower's Natrium reactor begins UK GDA process," June 17, 2026 — world-nuclear-news.org
  3. World Nuclear News, "Estonia's Parliament passes new nuclear energy law," June 18, 2026 — world-nuclear-news.org
  4. Lowdown.today, "UK uranium deal cuts Russia's fuel lever," June 16, 2026 — lowdown.today
  5. Crux Investor, "Supply Security Risks & Western Uranium Scarcity Drive Contract Prices to 14-Year Highs," June 10, 2026 — cruxinvestor.com
  6. Energy News, "Bulgaria grants EU sanctions derogation to keep Kozloduy nuclear plant running," June 2026 — energynews.pro
  7. Asia Pacific Express, "Laos Moves Toward Nuclear Power With Binding Rosatom Agreement In Moscow," June 17, 2026 — asiapacificexpress.com
  8. UPI, "KHNP chief visits Czech Republic to review $18 billion nuclear project," June 19, 2026 — upi.com
  9. World Nuclear News, "Elementl Power plans BWRX-300 SMRs in Ohio," June 19, 2026 — world-nuclear-news.org
  10. ANS / Nuclear Newswire, "NRC launches environmental review of Holtec's new-build plans for Palisades," June 16, 2026 — ans.org
  11. National Law Review, "NRC Proposes New Licensing Framework for Microreactors," June 19, 2026 — natlawreview.com
  12. Nuclear Engineering International, "Dow's Seadrift SMR milestone," May 21, 2026 — neimagazine.com
  13. SightLine / U3O8, "Iowa regulators clear key hurdle for Duane Arnold nuclear restart — but federal approvals remain," June 19, 2026 — sightlineu3o8.com
  14. New Civil Engineer, "Sizewell C challenged on cost overruns transparency and provides infrastructure update," June 19, 2026 — newcivilengineer.com
  15. Construction Enquirer, "Hinkley reactor 2 milestone hit 30% faster than Unit 1," June 1, 2026 — constructionenquirer.com
  16. Actualidad.es, "CSN evaluates the extension of Almaraz nuclear power plant's life," June 21, 2026 — actualidad.es
  17. EPR Magazine, "AERB approves continued operation of Tarapur Atomic Power Station," June 20, 2026 — eprmagazine.com
  18. Times of India, "Fifth unit of Kudankulam nuclear power project likely to be operational by year-end," June 2026 — timesofindia.indiatimes.com
  19. UNN, "External power supply has disappeared again at the ZNPP – IAEA records the 20th case since the start of the war," June 20, 2026 — unn.ua
  20. The Fusion Report, "This Week's Fusion News: June 19, 2026," June 19, 2026 — thefusionreport.com
  21. The Fusion Report, "General Fusion's SPAC Merger Clears SEC Review," June 15, 2026 — thefusionreport.com
  22. The Fusion Report, "Type One Energy Appoints Bernard Looney to Board," June 16, 2026 — thefusionreport.com
  23. EUROfusion, "Europe Advances Stellarator Fusion Research with the Launch of Project WISER," June 18, 2026 — euro-fusion.org
  24. U.S. Department of Energy, "Energy Department Releases Finalized Fusion Science and Technology Roadmap," June 2026 — energy.gov
  25. Purepoint Uranium Group, "The Underlying Supply-Demand Balance Continues to Tighten," June 17, 2026 — purepoint.ca

Nuclear Pulse is an independent weekly intelligence briefing. All information is sourced from publicly available industry publications. No investment advice is provided.

© 2026 Nuclear Pulse — Compiled by Tollaskígyó

Jun 14Nuclear Pulse — June 14, 2026

Covering: J
Published: June 14, 2026

Summary

The week was dominated by two intersecting threads: an acute safety episode in Ukraine and a quiet but consequential re-acceleration of the Western nuclear industrial base. The IAEA warned of significant structural damage at Chernobyl's new central used fuel storage facility after a drone strike, while Zaporizhzhia lost external power for nearly three days before the grid was reconnected through the ZaTES – Ferrosplavna No. 1 line [1][2]. On the build side, Three Mile Island Unit One cleared a FERC interconnection-rights transfer, clearing a major hurdle for Constellation's 2027 restart under the new Crane Clean Energy Center brand [3]. The US Department of Energy restarted uranium recovery at Savannah River Site's H Canyon with an explicit HALEU mandate, the uranium spot market stayed subdued around the mid-$80s per pound U3O8, and Avalanche Energy reported apparent ion temperatures above 1 keV in its compact fusion device "Jyn" [4][5][6]. Taken together, the week suggests the industry is no longer debating whether to expand nuclear, but whether the supply chain, regulator pipelines, and field construction crews can keep up with political will.

Geopolitical & Strategic Analysis

The week's signal is that nuclear security and nuclear industrial policy are now running on the same clock. The Chernobyl drone strike and ZNPP's nineteenth wartime blackout landed in the same news cycle, and the IAEA's response — formal Board of Governors briefings, mine-clearing observers, and direct negotiations with both sides to repair the 750 kV Dniprovska line — is itself a new institutional pattern [1][2]. Civilian nuclear infrastructure is being treated less as a passive asset under international protection and more as a live diplomatic object whose protection must be re-negotiated in real time. That is the cost of siting reactors on an active front: the IAEA can mediate, but it cannot insulate. For Europe, the lesson is structural: every gigawatt that comes back online in France, every SMR that lands in Romania or Poland, is also a marginal reduction in the strategic leverage that Moscow retains over downstream fuel and enrichment services. The same logic, in reverse, is now driving the US to rebuild its own front end: H Canyon's restart is not framed as cleanup, it is framed as industrial policy, with HALEU output explicitly named as the deliverable [4]. The deeper mood across Western capitals is that energy sovereignty is no longer a slogan; it is the explicit reason budgets are being rewritten and timelines shortened. Nuclear technology is functioning as a soft-power instrument in a way it has not since the 1970s, with export finance, fuel supply, and reactor design choices all being routed through that lens.

Regional Developments

North America

Constellation Energy's Three Mile Island Unit One restart moved a decisive step closer this week when FERC approved, on a 3-0 vote, the transfer of existing grid interconnection rights from the company's Eddystone coal and gas units in Delaware County to the rebooted reactor, which will operate as the Crane Clean Energy Center [3]. The transfer matters because PJM had warned that the 835 MW of TMI output might not be accepted back onto the grid until 2030 or later, a delay that would have gutted the project's economics. With FERC's clearance, the practical bottleneck shifts to NRC license amendments and the physical refurbishment of the unit, both of which Constellation has framed as on track for a 2027 return. The episode is also a quietly significant precedent: it shows that the regulator will treat interconnection rights as a fungible corporate asset between fossil and nuclear units under common ownership, a flexibility that did not exist a decade ago. On the fuel side, the Department of Energy formally restarted uranium recovery operations at the H Canyon facility inside the Savannah River Site, with the announced goal of producing high-assay low-enriched uranium for advanced reactors; the Department claims the current HEU inventory is sufficient to yield up to 19 tons of HALEU [4]. H Canyon is the only operating large-scale chemical separations facility in the United States, and its restart is the single most concrete supply-chain signal the US has sent to SMR developers in 2026.

Asia

A long MIT Technology Review piece published this week crystallized the divergence that is now defining the global reactor race: China has nearly doubled its nuclear fleet since 2016 and is approaching 60 GW of total capacity, with new builds almost exclusively gigawatt-scale pressurized-water reactors, while the United States has added just two reactors in the same period, both at Plant Vogtle in Georgia [7]. The Chinese strategy is consciously a "go big" strategy — long construction runs, standardized gigawatt units, and a domestic supply chain that can absorb the output — and it shows up directly in the global reactor count. For the rest of Asia, the question is no longer whether to build nuclear but whose reactor to build, and the Chinese offering is increasingly competitive on cost and timeline. The article is a useful counterweight to the US-centric SMR narrative: small reactors are real and they are coming, but in raw electrons-on-the-grid terms, the Asian big-reactor program is setting the pace that everyone else is measured against.

Europe

Europe's nuclear debate is shifting in tone but not yet in cash flow. Energy Intelligence reported this week that EU rhetoric is warming to nuclear while actual funding commitments remain limited, and a parallel piece noted that the Italian-US startup Newcleo is publicly pivoting toward lead-cooled fast reactor commercialization even as it reworks its capital structure [5]. The political signal is clear — Italy, Poland, the Czech Republic, and Romania are all publicly committing to new build or life extension — but the financial plumbing has not caught up. The continent's near-term leverage will come from making its existing French fleet run harder, signing long-term fuel supply contracts that bypass Russian enrichment, and underwriting a small number of flagship SMR or EPR2 projects that can serve as proof points for the rest of the program.

Technology & Innovation

The most consequential technology story of the week is the quiet restart of a piece of 1950s-era industrial chemistry. H Canyon's chemical separations lines at the Savannah River Site were originally built to recover uranium from defense production scrap; the Department of Energy's decision to bring the facility back online is, in effect, a decision that the United States needs its own domestic HALEU pipeline badly enough to reopen a Cold War plant for the purpose [4]. The technical risk is real — H Canyon has been in cold standby for years, and restarting chemical separations is not a software project — but the strategic logic is straightforward: every advanced reactor design from Natrium to Xe-100 to the latest microreactor pilots is gated on a fuel supply that does not yet exist at scale in the United States. H Canyon's restart is the first time a US government facility has been put on a production footing specifically to address that gap, and the announcement language ties the work directly to "executive orders to reinvigorate the nation's nuclear industrial base." On the AI and regulatory side, the week's signal is more diffuse but consistent: Constellation's FERC win was processed in a matter of weeks rather than the multi-year cycle that would have been considered normal a decade ago [3]. That kind of compression, applied to NRC license reviews, is where the next round of regulatory acceleration is most likely to come from.

Fusion Research

Compact fusion crossed a perceptual threshold this week. Avalanche Energy announced that its "Jyn" device had demonstrated measured apparent ion temperatures above 1 kiloelectron volt, or roughly 11 million degrees Celsius, in a hardware form factor small enough to be installed and iterated on a benchtop [6]. Avalanche's pitch has always been that fusion does not need a stadium-sized tokamak to make progress, and 1 keV is a meaningful physics threshold: it is the regime in which deuterium-deuterium reaction rates become non-negligible, and it is the regime that conventional magnetic-confinement devices only reach in plasmas tens of meters across. The result is not net energy, and Avalanche is explicit that it is not, but it is a credible demonstration that small-form-factor magnetic systems can be improved by rapid hardware iteration on a timeline that the big public programs cannot match. The broader fusion landscape continues to bifurcate: ITER and the national labs are still chasing confinement time and Q at scale, while a growing tier of private companies — Avalanche, Type One Energy, Commonwealth Fusion Systems, Helion — is treating fusion as a hardware-iteration problem rather than a single-shot engineering project. The 1 keV result is the strongest single data point yet that the iterative approach is producing real, measurable physics progress.

Market & Economic Intelligence

The uranium spot market stayed quiet this week, with only a handful of transactions reported in the days following the industry's annual conference in Arizona. Energy Intelligence documented a 100,000 pound U3O8 deal on June 8, two 50,000 pound trades at $84.75 per pound on June 11, and a further transaction at $85.50 per pound on June 12, with one of the 50,000 pound deals occurring between a trader and a bank [5]. The implied price band of roughly $84.75 to $85.50 per pound U3O8 is essentially flat to last week's close and reflects a market that is still digesting the conference's signal about 2027 utility demand rather than reacting to it. Term-market contracting is the more interesting story: utilities continue to lock in multi-year supply at premiums to spot, and the supply-side response — Cameco's production guidance, Cigar Lake's ramp, Kazatomprom's output discipline, and now the US restart of H Canyon — is collectively tightening the medium-term picture even as the spot tape stays calm. The structural read is that the market is no longer waiting for utilities to return; utilities have already returned, and the question is now whose pounds they will be buying in 2028 and beyond. The insurance and financing side of the market continues to thaw as well, with new long-tenor debt structures for refueling and uprate projects becoming available at margins that were unattainable eighteen months ago.


Sources

All 7 sources
  1. World Nuclear News — "IAEA warning after drone hits Chernobyl used fuel facility" — 8 June 2026. https://www.world-nuclear-news.org/articles/iaea-warning-after-drone-hits-chernobyl-used-fuel-facility
  2. Kyiv Post — "External Power Restored to Zaporizhzhia Nuclear Plant After 19th Wartime Blackout" — 14 June 2026. https://www.kyivpost.com/post/78138
  3. PennLive — "Three Mile Island nuclear restart notches another big approval" — 9 June 2026. https://www.pennlive.com/news/2026/06/three-mile-island-nuclear-restart-notches-another-big-approval.html
  4. American Nuclear Society / Nuclear Newswire — "H Canyon restarts uranium recovery operations" — 10 June 2026. https://www.ans.org/news/article-7746/h-canyon-restarts-uranium-recovery-operations/
  5. Energy Intelligence — "Limited Uranium Spot Activity Following Industry Conference" — 12 June 2026. https://www.energyintel.com/0000019e-bc84-de60-a7df-fead840c0000
  6. PR Newswire / Avalanche Energy — "Avalanche Energy Achieves Measured Apparent Ion Temperatures Above 1 keV in Compact Fusion Experiment" — 10 June 2026. https://www.prnewswire.com/news-releases/avalanche-energy-achieves-measured-apparent-ion-temperatures-above-1-kev-in-compact-fusion-experiment-302795978.html
  7. MIT Technology Review — "Why China is betting on big nuclear reactors" — 11 June 2026. https://www.technologyreview.com/2026/06/11/1138789/china-big-nuclear-reactors/

Nuclear Pulse is an independent weekly intelligence briefing. All information is sourced from publicly available industry publications. No investment advice is provided.

© 2026 Nuclear Pulse — Compiled by Tollaskígyó

Jun 7Nuclear Pulse — June 7, 2026

Covering: J
Published: June 7, 2026

This Week's International Nuclear News

Drone Strike at Barakah Nuclear Power Plant — UAE's Nuclear Infrastructure in the Spotlight

The most significant security-policy event of the week was a drone strike on the United Arab Emirates' Barakah nuclear power plant. The attack caused a fire at the plant's perimeter fence, and IAEA Director General Rafael Grossi called the incident "a serious violation of nuclear safety." The UAE urged a firm response from the international community, while Iran warned that attacks on nuclear facilities "must not be normalized." Bloomberg analysis suggested that the IAEA may push for stronger protective measures at reactors in the future. AP and BBC sources simultaneously reported that the drone strike coincided with signals from both the US and Iran that they were prepared to continue the war. The UN emphasized the importance of protecting nuclear facilities, and the IAEA Director General visited the Persian Gulf region to strengthen nuclear safety cooperation.

Russian Drone Strikes Nuclear Fuel Storage Facility in the Chernobyl Exclusion Zone

A serious nuclear safety incident occurred in Ukraine this week: a Russian drone struck the spent fuel storage facility located in the Chernobyl exclusion zone, causing a fire. According to a statement from Ukraine's Energoatom, the container storage was partially destroyed. President Zelensky informed international partners about the incident, and the international press widely covered the development. Ukrainian authorities had also previously reported that a Ukrainian drone struck near Russian engineers conducting demining operations at the Zaporizhzhia nuclear power plant — according to Rosatom's claim. On a positive note, power supply to the Zaporizhzhia plant was restored after an extended outage, with the IAEA announcing that a local ceasefire had been implemented to allow repairs to the power lines. In a separate analysis, WNN highlighted that military operations near nuclear facilities have drawn attention to the critical role of external power supply.

USA: First Microreactor Reaches Criticality in DOE Pilot Program

A milestone was reached in microreactor development in the United States: the Antares small modular reactor — a collaboration between BWX Technologies and Antares Nuclear Inc. — became the first to achieve criticality in the Department of Energy (DOE) pilot program at Idaho National Laboratory. Simultaneously, the privately developed Mark-Zero reactor also reached critical status at the same site. According to a DOE statement, this is the first time an advanced nuclear reactor has reached this milestone in the program. The significance of the development lies in the fact that microreactors could play a key role in meeting the energy demands of data centers and powering lunar and Mars missions — in Wyoming, for example, a similar reactor is being developed specifically for the energy needs of Moon missions. In parallel, the government announced the "Nuclear Energy Launch Pad" program, aimed at accelerating the licensing of new technologies.

Uzbekistan: Putin and Mirziyoyev Lay First Foundation Stone for Nuclear Power Plant

Uzbekistan took a historic step: in a ceremonial event attended by Russian President Vladimir Putin and Uzbek President Shavkat Mirziyoyev, the foundation stone for the country's first nuclear power plant was laid. The 2.4 GW facility, built by Rosatom, is one of the largest energy investments in the Central Asian region. The IAEA Director General also praised the milestone, emphasizing the progress of Uzbekistan's nuclear program. At the same time, Rosatom held the first concrete-pouring ceremony for the Uzbek SMR project. The event fits into a broader process in which Russia is building close nuclear partnerships with countries in the former Soviet space and across the Global South — Rosatom and Brazil's NBEPar, for instance, have established a joint venture, while a new cooperation agreement was signed with Indonesia.

Japan: Plans to Replace 14 Reactors by 2050

Japan announced ambitious nuclear plans: under the government's proposal, up to 14 aging reactors would be replaced with new units by 2050, and 5 reused reactors would be brought back online by the 2040s. The move represents Japan's biggest nuclear pivot since the Fukushima era and is also a response to growing energy demand, particularly driven by data centers and artificial intelligence sectors. The Japanese plan coincides with American trends: the newly formed nuclear industry coalition in Ohio, the New York RFQ/RFA solicitation windows, the New England governors' joint statement, and efforts by Tennessee and Wyoming (the latter through community information campaigns) are all signs of an American "nuclear renaissance." In Illinois, the Pritzker executive order is advancing, while in North Carolina, legislation on data center regulation and nuclear energy is moving forward.

Uranium Market and Enrichment: Bottlenecks in the Western Supply Chain

Several important developments took place in the uranium value chain this week. Centrus Energy received a $900 million DOE investment to expand American uranium enrichment capacity, while Urenco is increasing its US enrichment capacity by nearly 50% to meet the growing demands of nuclear power plants. The Trump administration announced "sprint programs" to accelerate uranium production and reactor construction, and a new American company announced plans to build a uranium conversion facility. Meanwhile, a Financial Times report warned that the US nuclear renaissance is threatened by fuel shortages — the largest suppliers cautioning that the market cannot keep pace with rising demand. Uranium Energy Corp. began production at its Burke Hollow project, and Kazakhstan updated its uranium and nuclear plans. According to Bloomberg, Goldman Sachs has incorporated SMRs into its nuclear model, forecasting a 17% increase in uranium demand. Canada and India signed a new long-term uranium supply agreement. The US is also considering increasing uranium imports from Namibia, capitalizing on the AI-driven nuclear boom.

UK Nuclear Energy at Historic Low in 2025

According to data from the UK Department for Energy Security and Net Zero (DESNZ), the share of nuclear energy in UK electricity generation fell to a record low in 2025. The situation is paradoxically set against the backdrop of the nuclear industry's reindustrialization: the installation of the second reactor vessel at Hinkley Point C, the competition to name the UK's first SMR site, and the supply chain dispute between Rolls-Royce and South Korean partners all indicate that the British nuclear future will undergo a fundamental transformation in the coming decade. US and UK SMR developers also announced new partnerships, and the "gas-plus-nuclear" solution may merge in the energy mix of the coming period. The Nuclear Company launched a nuclear-specific safety platform, signaling the advance of digitalization in the sector.

Middle East, South Asia, and the Global South's Nuclear Ambitions

The expansion of nuclear energy is accelerating in several parts of the world. India announced that the PFBR (Prototype Fast Breeder Reactor), planned for 40 years, has finally achieved criticality — a milestone on the path toward a closed fuel cycle. In Bangladesh, fuel loading has begun at the country's first nuclear power plant. Meanwhile, Iran set a new electricity generation record at the Bushehr nuclear power plant, while the IAEA indicated it cannot verify enriched uranium stockpiles — Iran permits inspections of the Bushehr units but blocks inspections of enriched uranium inventories. Russia is building a "nuclear bridgehead" in Egypt, and Jamaica is taking concrete steps toward nuclear energy. The Italian parliament advanced legislation enabling a return to nuclear energy, and a Norwegian committee recommended nationwide preparedness. Construction of South Korea's Shin Hanul Unit 4 has also begun, and in China, the containment dome of Lianjiang-1 was installed. At the IAEA-organized 2026 Nuclear Energy Summit, world leaders reaffirmed the central role of nuclear energy in climate protection.

The IAEA's Role and International Nuclear Safety

The IAEA once again served as the cornerstone of international nuclear safety this week: the Director General visited the Persian Gulf region, praised the progress of Uzbekistan's nuclear program, and commented on the upcoming "nuclear framework agreement" in US–Iran negotiations. The organization also assisted in transporting highly enriched uranium nuclear fuel from Venezuela to the US — a step aimed at reducing proliferation risks. The IAEA's "Nuclear Energy Summit 2026" closing statement reaffirmed that nuclear energy plays a key role in building clean, safe, and resilient energy systems.

American Nuclear Industry: Data Centers, Regulation, and Public Opinion

In the American nuclear sector, meeting the energy demands of data centers and AI is becoming increasingly prominent. According to Gallup's latest survey, public support for nuclear energy is rising, while support for solar and wind is declining. Microsoft, Amazon, and SpaceX all see nuclear energy as the solution to the AI energy gap — LG&E and KU are jointly exploring SMR applications with X-energy, while NextEra and Dominion reached a merger agreement that reshapes the New England nuclear market. A nuclear industry coalition formed in Ohio, and Orano USA's Oak Ridge facility is expected to receive its license by April 2027. According to World Nuclear News, "smaller and faster" constructions are returning to North America — OPG's Darlington project is one of the frontrunners of this model, and plans for the world's largest nuclear power plant have also emerged on the shores of Lake Ontario in Canada. On the occasion of the 40th anniversary of Chernobyl, WNN launched a podcast series on the accident's industry impact, the wildlife in the exclusion zone, and scientific research.


Sources: World Nuclear News, Reuters, Bloomberg, Financial Times, ANS Nuclear Newswire, IAEA, DOE, The Japan Times, The Jerusalem Post, The Kyiv Independent, Newsweek, Caspi News, Anadolu Ajansı, AP News, BBC, Al Jazeera, ANS, Interesting Engineering, Sustainability Magazine, Gallup, Microsoft, Centrus Energy, Urenco, Mining.com.


Sources

All 0 sources

Nuclear Pulse is an independent weekly intelligence briefing. All information is sourced from publicly available industry publications. No investment advice is provided.

© 2026 Nuclear Pulse — Compiled by Tollaskígyó

May 31Nuclear Pulse — May 31, 2026

Covering: M
Published: May 31, 2026

This Week's International Nuclear News

Zaporizhzhia Drone Attack: Moscow and Kyiv Point Fingers

The most widely discussed event of the week was the alleged drone attack on the Zaporizhzhia Nuclear Power Plant. Russia — through Rosatom — claims that a Ukrainian drone struck the plant's turbine hall. Kyiv firmly denies the accusation and called the Russian claims "nuclear blackmail." According to a statement from Ukrainian defense forces, Russia is using the incident for its own propaganda purposes. IAEA Director General Rafael Grossi expressed concern and warned of a "pattern" in attacks on nuclear facilities. The IAEA demanded access to the plant to assess the damage. The incident highlights that nuclear facilities affected by the war continue to pose serious safety risks.

Russia Signs $16.5 Billion Nuclear Power Plant Deal with Kazakhstan

Putin scored a significant diplomatic victory in Central Asia: Russia and Kazakhstan finalized a $16.5 billion agreement to build Kazakhstan's first nuclear power plant. The 2.4 GW facility will be constructed by Rosatom. Meanwhile, the IAEA chief visited Kazakhstan to expand nuclear cooperation — the agenda included science, energy production, and cancer care. Kazakhstan also offered to take over Iran's enriched uranium stockpile as part of US-Iran negotiations, a development of exceptional geopolitical significance.

Rwanda-Russia Nuclear Agreement — Africa's Energy Balance Shifting

Rwanda and Russia signed a nuclear agreement, which analysts say reflects Africa's changing power dynamics. The deal is part of a broader Russian strategy to build nuclear influence in African countries — Rosatom is increasingly active across the continent.

Rosatom Faces Challenges: Armenia Pulls Away, Europe Hesitates, China Steps In

According to an analysis by the Bellona Foundation, Rosatom is experiencing an "uncomfortable spring." Armenia is moving away from Russian nuclear technology, Europe remains uncertain about its dependence on Russian uranium, and China is taking on an increasingly large role in the global nuclear supply chain. In Switzerland, a Greenpeace report found that Russian uranium continues to fuel Swiss nuclear power plants.

South Korea: Construction of Shin Hanul Unit 4 Begins

The first concrete pouring for the reactor building of Shin Hanul Nuclear Power Plant Unit 4 has taken place, officially marking the start of construction. South Korea continues to expand its nuclear capacity.

USA: Cold War Plutonium to Become Nuclear Fuel

The Trump administration's plans call for converting weapons-grade plutonium from Cold War nuclear weapons into nuclear fuel. The DOE selected five companies for negotiations on taking over surplus American plutonium. Scientific American and other experts say the plan is risky — the commercial use of weapons-grade materials raises serious security and proliferation concerns. NANO Nuclear Energy's subsidiary, Secured Transportation Services, completed three DOE/NNSA nuclear transportation missions.

SMRs and New Nuclear Projects Across America

Small modular reactors (SMRs) and new nuclear projects are gaining momentum in several US states:

  • Utah: The $20 billion Blue Castle nuclear power plant project is restarting after 19 years, with a new partnership. Plans call for SMRs to be deployed in small Utah towns.
  • Nebraska: The state is evaluating the possibility of new nuclear capacity — promising but fraught with challenges.
  • New Jersey: An assembly committee advanced a bill aimed at developing advanced nuclear energy.
  • Iowa: The Nuclear Energy Task Force is finalizing its report for state lawmakers.
  • Texas A&M: The RELLIS campus is building the future of nuclear energy.
  • Wyoming: TerraPower plans to house 1,600 workers for the Kemmerer construction project.

Floating Nuclear Power Plants: Russia and Greece

Russia has manufactured the first RITM-200 reactor unit for its floating nuclear power plant fleet. A new study suggests that floating nuclear power plants could provide clean energy to the Greek islands — World Nuclear News called the concept "realistic."

Uranium Market and Nuclear Fuel Supply

  • Canada's nuclear expansion depends on domestic uranium enrichment capacity — a Policy Options analysis calls this a critical bottleneck.
  • A new US uranium enrichment facility could boost nuclear fuel supply.
  • India is ready to buy large quantities of Canadian uranium and invest in mines — according to India's chief commissioner.
  • Visual Capitalist ranked the world's largest uranium producers and who controls global uranium reserves.
  • TSX-listed uranium stocks are surging amid the nuclear renaissance.
  • Iran's strong card in nuclear negotiations: its highly enriched uranium stockpile. The US-Iran negotiations center on removing "nuclear dust."

Chernobyl at 40: A New Nuclear Era?

Both the South China Morning Post and World Nuclear News covered the 40th anniversary of the Chernobyl disaster. The question: is the world entering a new nuclear era? WNN launched a podcast series on the topic, showcasing the zone's wildlife, scientific research, and the accident's impact on the global nuclear industry.

IAEA: Advanced Nuclear Fuels and Fukushima

The IAEA launched a new research project to support the development of advanced nuclear fuels. Additionally, an IAEA-led mission conducted water sampling at the Fukushima Daiichi nuclear power plant. Meanwhile, the IAEA reported the longest communication outage at the Zaporizhzhia plant.

Data Centers and Nuclear Energy

Rising electricity demand — particularly from AI data centers — continues to drive demand for the nuclear industry. Pennsylvania's governor developed a plan for data centers to bring their own power. Ohio and Pennsylvania aim to power data centers with nuclear energy. According to 24/7 Wall St., "nuclear energy is the only real answer to AI's electricity demand."

Other Notable News

  • The US Navy is testing the nuclear power of the USS Gerald R. Ford aircraft carrier to supply the Norfolk naval base.
  • EDF highlighted the positive impacts of Hinkley Point C.
  • The ITER magnet test facility has begun operations.
  • The ANS Annual Conference will present national awards in 2026.
  • NANO Nuclear Energy acquired Secured Transportation Services for $13 million.
  • The nuclear industry has gained new momentum — and with it, efforts to recycle radioactive waste have intensified (WSJ).

*Sources: World Nuclear News, Reuters, IAEA, ANS Nuclear Newswire, Bellona Foundation, Scientific American, Fox News, Al Jazeera, SCMP, and other international news agencies.*


Sources

All 0 sources

Nuclear Pulse is an independent weekly intelligence briefing. All information is sourced from publicly available industry publications. No investment advice is provided.

© 2026 Nuclear Pulse — Compiled by Tollaskígyó

May 24Nuclear Pulse — May 24, 2026

Covering: May 18–24, 2026
Published: May 24, 2026

Week of May 18–24, 2026


Summary

The US nuclear sector marked one year since President Trump's four executive orders that fundamentally reshaped NRC regulatory processes, with the NRC now accelerating its review of Orano's Oak Ridge enrichment plant toward an April 2027 target [1]. Europe's nuclear-industrial strategy deepened as EDF joined the AION consortium to power a European AI Gigafactory in France, while Blykalla submitted Sweden's first application for a six-SMR lead-cooled reactor site [2][3]. Kazakhstan formalized its nuclear industrialisation with a comprehensive 2026–2030 localisation plan for the Balkhash plant project led by Rosatom [4]. The world's first multi-year commercial HALEU supply contract was signed between Urenco and Antares, signalling market maturation for advanced reactor fuel beyond government allocations [5]. Russia's Kursk II VVER-TOI unit crossed 2 billion kWh generated, completing over 1,500 system tests before entering commercial operation [6].

Geopolitical & Strategic Analysis

The week's developments reveal an industry in the midst of a structural pivot from policy declarations to tangible supply chain execution. The one-year anniversary of President Trump's nuclear executive orders demonstrated measurable progress — the NRC's expedited review of the Orano enrichment plant directly answers the strategic imperative to reduce US dependency on foreign enrichment, which NRC Chairman Ho Nieh explicitly framed as a national security objective [1]. Simultaneously, Kazakhstan's formal 2026–2030 localisation plan for the Rosatom-led Balkhash plant underscores the deepening nuclear industrial cooperation between Central Asia's uranium powerhouse and Russia, a relationship that carries profound implications for the global fuel cycle balance [4]. That the world's first multi-year HALEU supply contract was signed this week between Urenco and Antares is not merely a commercial milestone — it represents the beginning of a Western-aligned advanced fuel market independent of Russian and Chinese infrastructure, which until 2024 were the only producers of HALEU at scale [5]. In Europe, the formation of the AION consortium with EDF, Capgemini, Orange, and others to power a sovereign AI Gigafactory reflects the emerging strategic doctrine that nuclear energy is not just baseload power but the foundational infrastructure for technological sovereignty [2]. The NEA Director General William Magwood's lecture at the University of Missouri this week further amplified the message of growing global interest in nuclear, reinforcing the diplomatic dimension of nuclear technology as a soft power instrument [7]. Taken together, these developments show a global nuclear sector where energy sovereignty, fuel independence, and technological competitiveness are increasingly inseparable policy objectives.

Regional Developments

North America

The dominant story this week was the one-year retrospective on President Trump's May 2025 nuclear executive orders, which observers note have produced tangible regulatory acceleration — the NRC's expedited 18-month review schedule for Orano's Oak Ridge enrichment plant is the most visible outcome, with the regulator setting an estimated completion date of April 30, 2027 [1]. The NRC also proposed sweeping changes to its rules governing nuclear materials in response to Executive Order 14300, part of the broader modernisation effort [8]. In a landmark utility consolidation, NextEra Energy announced the acquisition of Dominion Energy in an approximately $67 billion merger that will reshape the nuclear power landscape across several US states [9]. The Department of Energy's Office of Environmental Management continues to face significant staffing shortages, according to a GAO report released this week, threatening the pace of radioactive waste cleanup at legacy weapons sites [10]. The National Reactor Innovation Center held an industry day for its Launch Pad program, designed to fast-track regulatory processes for new reactors and fuel facilities that meet development milestones [11]. Dow received its Environmental Assessment and Finding of No Significant Impact for the Seadrift project, advancing the X-energy Xe-100 advanced reactor deployment for industrial process heat in Texas [12]. The Senate Environment and Public Works Committee weighed in on three nuclear energy bills with bipartisan support, signalling continued legislative momentum [13].

Europe

Blykalla submitted an application to build Sweden's first lead-cooled SMR site — a 330-MWe facility housing six reactors — marking a significant milestone for advanced reactor deployment in Scandinavia [3]. EDF's entry into the AION consortium alongside technology giants Capgemini, Orange, and Scaleway positions nuclear power as the energy backbone of Europe's sovereign AI infrastructure ambitions, with the consortium bidding to host a European AI Gigafactory in France [2]. The UK's Nuclear Waste Services provided an update on the Low Level Waste Repository capping project, which aims to convert a once-temporary disposal facility into a permanent, environmentally safe multi-barrier engineered cap designed to prevent water infiltration and radionuclide migration [14]. Urenco's HALEU supply contract with Antares also highlights the UK's growing role in advanced fuel enrichment, with the UK facility scheduled to come online in 2031 [5].

Asia

Russia's Kursk II VVER-TOI unit — the most powerful nuclear power unit in Russian design history — crossed the milestone of 2 billion kWh generated since entering commercial operation earlier this month, following more than 1,500 system tests and final regulatory approval from Rostekhnadzor on April 27 [6]. The Kursk plant now operates above 3,000 MW, with units 2 and 3 under construction toward an eventual four-unit, 5,000-MW complex [6]. Kazakhstan's Atomic Energy Agency released its Comprehensive Plan for Developing Localisation in the Nuclear Industry for 2026–2030, covering regulatory framework development, domestic market analysis, supplier registry creation, and workforce training — all aimed at ensuring Kazakh enterprises can participate in nuclear projects under international safety and quality standards [4]. The document formalises Kazakhstan's commitment to creating a sustainable domestic nuclear supply chain around the planned Balkhash plant.

Middle East & Africa

No verifiable nuclear energy developments from the Middle East or Africa were confirmed during the reporting week of May 18–24, 2026.

Latin America

Argentina's Nucleoeléctrica secured a 10-year operating licence renewal for the Atucha II nuclear power plant, a 693 MWe pressurised heavy water reactor originally ordered in 1979 and completed after decades of construction pauses. Nucleoeléctrica President Juan Martín Campos described the renewal as recognition of the technical and operational capabilities developed by Argentina's nuclear workforce to meet the highest regulatory standards [15].

Technology & Innovation

The intersection of nuclear technology and advanced manufacturing was on full display this week. Idaho National Laboratory announced that its Structural Properties Laboratory — housing INL's first new hot cell in 50 years — has been fully operational since January, providing critical infrastructure for irradiated material testing with both manual and robotic manipulators for safe handling [16]. Oak Ridge National Laboratory completed a significant set of experiments measuring the viscosity and thermal conductivity of several uranium-bearing molten salts, filling in data gaps essential for molten salt reactor design and safety analysis [17]. The DOE's Pacific Northwest National Laboratory, in collaboration with the National Institute of Standards and Technology, announced the recovery of substantial quantities of radium-226 from radiological waste stored at NIST facilities — material valued for its role in developing cancer-fighting medical radioisotope therapies, showcasing the dual-use value of nuclear materials management [18]. Antares, the microreactor developer founded in 2023, confirmed it remains on track for a reactor demonstration in 2026 and its first electricity-producing reactor test in 2027, with commercial deployments beginning in 2028 — securing its fuel supply chain through this week's landmark HALEU contract with Urenco was a critical enabler [5]. The Maine Maritime Academy announced it will become the first US maritime academy to offer a major in nuclear engineering technology, a workforce development signal that the industry's skills pipeline is expanding beyond traditional pathways into specialised operational domains [19].

Fusion Research

Canada's Strategic Innovation Fund announced backing for a fusion-based copper-67 production project, funding a collaboration between Promation, Astral Systems, and the Canadian Medical Isotope Ecosystem that uses compact fusion systems for medical isotope generation rather than traditional reactor-based production [20]. This represents a notable crossover application where fusion technology serves medical purposes before achieving net energy gain — a validation pathway that could accelerate commercial fusion deployment by creating early revenue streams. On the regulatory front, the Fusion Industry Association submitted its response to the NRC's proposed rulemaking and draft guidance for US fusion regulations, contributing to the emerging framework that will govern commercial fusion deployment in the United States [21]. The broader European fusion ecosystem also saw continued advocacy, with European fusion and industrial CEOs calling for an EU Fusion Strategy explicitly framed around energy security rather than purely scientific objectives [21].

Market & Economic Intelligence

Uranium Spot Price (U3O8): The UxC U3O8 Weekly Spot Indicator has maintained stability in the mid-$80s per pound range ($84.00–$86.00/lb) throughout May 2026, with no significant weekly movement (trend: stable). The long-term contract price continues to diverge upward, reflecting the structural supply deficit as utilities secure multi-year deliveries for planned reactor restarts and new builds. The physical uranium market remains tight, with Sprott Physical Uranium Trust and other financial buyers continuing to absorb available spot inventory.

The most significant commercial development this week was the world's first multi-year HALEU supply contract, signed between Urenco and Antares, which CEO Jordan Bramble described as ensuring commercial fuel supply "beyond material allocated by the federal government" [5]. This contract — with Urenco's UK HALEU facility scheduled to begin production in 2031 — is a market-maturation signal for advanced reactor fuels, demonstrating that private off-take agreements are now viable alongside government stockpile programs. The NextEra-Dominion $67 billion merger announcement also carries significant implications for nuclear asset ownership and utility-scale deployment economics, consolidating two of America's largest nuclear-operating utilities under a single entity [9]. In Kazakhstan, the 2026–2030 localisation plan explicitly aims to attract investment in the nuclear industry and develop new products within a sustainable production ecosystem, reinforcing the Central Asian nation's ambition to move beyond raw uranium exports toward value-added nuclear industrial services [4]. The GAO's warnings about DOE-EM staffing shortages introduce a cautionary note for market optimism — the cleanup mission's workforce gap could delay site remediation timelines that are prerequisites for new nuclear construction at several DOE sites [10].


Sources

All 21 sources
  1. "US enrichment plant begins accelerated review" — World Nuclear News, May 22, 2026
  2. "EDF joins alliance to support AI Gigafactory bid" — World Nuclear News, May 21, 2026
  3. "Blykalla submits application for six-SMR site in Sweden" — ANS Nuclear News, May 20, 2026
  4. "Kazakhstan outlines localisation plans" — World Nuclear News, May 22, 2026
  5. "Antares signs long-term HALEU supply deal with Urenco" — World Nuclear News, May 22, 2026
  6. "Kursk II's first VVER-TOI has generated 2 billion kWh" — World Nuclear News, May 22, 2026
  7. "NEA head gives talk about growing global interest in nuclear energy" — ANS Nuclear News, May 18, 2026
  8. "NRC proposes changes to its rules on nuclear materials" — ANS Nuclear News, May 19, 2026
  9. "NextEra, Dominion to merge in major utilities announcement" — ANS Nuclear News, May 18, 2026
  10. "GAO: Staffing problems continue to plague DOE-EM" — ANS Nuclear News, May 22, 2026
  11. "NRIC industry day highlights lessons learned from pilot programs" — ANS Nuclear News, May 22, 2026
  12. "Dow gets EA/FONSI for Seadrift project" — ANS Nuclear News, May 20, 2026
  13. "Senate EPW subcommittee weighs in on three nuclear energy bills" — ANS Nuclear News, May 21, 2026
  14. "Podcast: Sustainability and the UK's Low Level Waste Repository" — World Nuclear News, May 22, 2026
  15. "Atucha II granted 10-year licence renewal" — World Nuclear News, May 22, 2026
  16. "Structural Properties Laboratory now open at INL" — ANS Nuclear News, May 21, 2026
  17. "ORNL completes challenging molten salt property measurements" — ANS Nuclear News, May 19, 2026
  18. "DOE, PNNL, and Commerce Dept. collaborate on Ra-226 recovery" — ANS Nuclear News, May 22, 2026
  19. "Maine Maritime Academy to offer nuclear engineering technology major" — ANS Nuclear News, May 19, 2026
  20. "Canada funds fusion-based copper-67 production project" — ANS Nuclear News, May 20, 2026
  21. "FIA Submits Response to NRC's Proposed Rulemaking and Draft Guidance for US Fusion Regulations" — Fusion Industry Association, May 2026

Nuclear Pulse is an independent weekly intelligence briefing. All information is sourced from publicly available industry publications. No investment advice is provided.

© 2026 Nuclear Pulse — Compiled by Tollaskígyó

May 17Nuclear Pulse — May 17, 2026

Covering: M
Published: May 17, 2026

Published: May 17, 2026


1. Summary

The global nuclear sector this week was defined by an accelerating SMR race — the U.S. DOE awarded $94 million to eight American companies to fast-track Generation III+ small modular reactor deployment, while TerraPower tapped South Korean manufacturing muscle for its first U.S. Natrium project [1] [2]. Meanwhile, Italy formally launched its legislative pathway to re-enter nuclear power after a 35-year absence, Croatia opened a public consultation on its own nuclear energy law, and Goldman Sachs integrated SMRs into its long-term nuclear model, projecting a 17% increase in uranium demand through 2045 [3] [4] [5]. On the geopolitical front, Iran resumed construction on Bushehr Unit 2 with Russian assistance, just as financial strains and mining disputes between Moscow and Kazakhstan clouded the uranium supply chain [6] [7]. Uranium spot prices held near $90/lb U3O8, supported by deepening utility undercontracting and AI-driven power demand, while long-term contract prices reached as high as $150/lb [8] [9].

2. Geopolitical & Strategic Analysis

The nuclear industry this week reflected a world increasingly organized around energy sovereignty. The United States continued to weaponize its nuclear industrial base as an instrument of soft power: a senior DOE official briefed an industry delegation ahead of a high-level visit to India, while bipartisan legislation from Senators Kelly and Lummis sought to slash construction costs and accelerate domestic deployment, explicitly framing the effort as a supply-chain security imperative [10] [11]. The U.S. Senate also tackled the glaring vulnerability of a nation that imports 95% of its uranium, while MIDA approved $16.5 million to prepare a site for a domestic uranium enrichment equipment facility in Utah [12] [13]. In parallel, Russia's Rosatom resumed construction at Iran's Bushehr Unit 2, a project that simultaneously advances Moscow's reactor export portfolio and deepens Tehran's nuclear infrastructure under international scrutiny [6]. The Russia-Kazakhstan uranium partnership, long the backbone of global supply, showed fresh cracks as financial tensions and mining disputes threatened the stability of a relationship responsible for roughly 40% of world uranium production [7]. Southeast Asia emerged as the newest frontier in nuclear geopolitics, with China offering preferential reactor financing and technology transfer to nations across the region, while the Rosatom chief publicly identified Southeast Asia as a "major growth region" for nuclear power [14] [15]. Indonesia discussed cooperation with Russia, and the Philippines accelerated workforce training for its planned nuclear revival — all pointing to a multipolar competition where reactor deals double as strategic alliances [16] [17].

3. Regional Developments

North America: The DOE's $94 million award to eight U.S. companies — aimed at speeding Generation III+ SMR deployment from design to construction — dominated the week's domestic agenda, alongside the news that NANO Nuclear Energy submitted its KRONOS MMR Construction Permit Application to the NRC and reported $568.7 million in liquidity [18] [1] [19]. TerraPower deepened its supply chain by partnering with Korean heavy industry for the Natrium project, while GE Vernova's hybrid gas-nuclear bet in Texas raised questions about whether modular energy narratives can sustain premium valuations [2] [20]. The Senate advanced legislation targeting nuclear supply chain gaps, state-level activity surged as South Carolina sought to host a DOE Nuclear Lifecycle Innovation Campus, Kentucky's nuclear future drew bipartisan backing, and Missouri launched its Advanced Nuclear Energy Task Force [11] [21] [22] [23]. Meanwhile, an Energoatom reform effort suffered a blow as a key U.S. nuclear veteran departed the Ukrainian state-owned utility [24]. In Canada, AtkinsRéalis reported strong Q1 results buoyed by its new nuclear alliance and the CANDU reactor fleet [25].

Europe: Italy formally prepared its legislative return to nuclear power, a historic reversal driven by energy security imperatives after decades of post-referendum abstinence [3]. Croatia launched a public consultation on its own nuclear energy law, signaling that the nuclear revival is spreading beyond the continent's traditional atomic powers [4]. Switzerland published findings that its existing nuclear plants could safely operate for up to 80 years, providing a clear signal against premature phase-outs [26]. The IAEA took the unusual step of assisting Austria — a country with a constitutional ban on nuclear power — with nuclear security measures for the Eurovision Song Contest 2026, an operational footnote that underscored the normalization of nuclear security as a routine public safety function [27].

Asia: India's nuclear ambitions dominated the region's headlines this week: the NTPC chief cautioned against over-dependence on foreign nuclear technology supply chains, while three decommissioned thermal power sites were shortlisted for new nuclear construction, and a broader strategic vision for technological self-reliance in the nuclear domain was articulated by policymakers [28] [29] [30]. China's nuclear build-out continued to attract attention, with OilPrice.com noting that the country added 34 GW of nuclear capacity in a single decade — a pace unmatched by any other nation [31]. China also offered Southeast Asian nations clear advantages in nuclear power cooperation, leveraging its state-backed financing model [14]. Indonesia engaged Russia in nuclear energy cooperation talks, and the Philippines continued preparing its workforce for a nuclear restart [16] [17].

Middle East & Africa: Iran resumed construction of Bushehr Nuclear Plant Unit 2, with Rosatom providing technical support, a development that sits uneasily within ongoing geopolitical tensions and IAEA safeguards concerns [6]. The IAEA released a major report on nuclear power opportunities in Africa, and a prominent African nuclear executive made the case that nuclear energy is key to powering the continent [32] [33]. These parallel developments — one focused on building reactors, the other on building institutional capacity — illustrate the widening scope of nuclear engagement across the Global South.

4. Technology & Innovation

This week was shaped by a convergence of advanced reactor design milestones and the growing institutional appetite for regulatory modernization. NANO Nuclear Energy's submission of its KRONOS MMR Construction Permit Application to the NRC marked a tangible step from press releases toward regulatory reality, while the company's parallel announcement of a collaboration with Super Micro to power AI data centers with on-site microreactors underscored how data center energy demand is reshaping the commercial logic of advanced nuclear [19] [34]. The DOE's $94 million Gen III+ SMR program, distributed across eight companies, represents the most explicit federal bet yet that small modular reactors can cross the valley of death between design certification and actual construction [1]. On the legislative front, the bipartisan Kelly-Lummis-Donalds bill proposed concrete mechanisms to cut nuclear construction costs — addressing what NEI's Maria Korsnick called the "real test" of scaling the industry [11] [35]. AtkinsRéalis and FANCO formed a strategic alliance specifically targeting SMR deployment acceleration, illustrating the industrial consolidation underway as supply chains mature [36]. L3Harris finalized the design of a deep-space nuclear power source, a reminder that nuclear innovation extends well beyond terrestrial grids [37]. Russia delivered its first 175 MW RITM-400 reactor unit for the Leningrad nuclear icebreaker, demonstrating continued mastery of transportable nuclear systems [38]. A Frontier-backed reactor design moved from models to live tests, and GE Vernova's hybrid gas-nuclear Texas project tested the boundaries of modular energy narratives against rich market valuations [39] [20].

5. Fusion Research

The most significant fusion development this week was the U.S. fusion firm Commonwealth Fusion Systems beginning installation of the final 48-ton vacuum vessel half for its SPARC net-energy demonstration reactor — a concrete engineering milestone that moves the project closer to its goal of achieving first plasma and demonstrating net energy gain [40]. In parallel, Jefferson Lab was identified as a potential future hub for fusion energy research, expanding the institutional footprint of fusion beyond the traditional tokamak community [41]. The broader fusion ecosystem continued its maturation: stellarators gained attention as leading fusion candidates in a major Physics Today feature, and the U.K.'s STEP fusion program achieved a milestone with remountable magnet technology passing critical tests, though that breakthrough falls just outside this week's reporting window [42]. The fusion funding environment, however, is showing its first signs of strain — TechCrunch reported that cracks are forming in fusion's funding boom, and a Nature paper cautioned that fusion power experience rates may be overestimated, injecting a note of scientific sobriety into the commercial fusion narrative [43] [44].

6. Market & Economic Intelligence

Uranium markets remained structurally tight this week. The spot price of U3O8 held near $90/lb, while long-term contract prices surged to $150/lb, driven by AI data center power demand and persistent utility undercontracting [8] [9]. Goldman Sachs added SMRs to its nuclear model and projected a 17% increase in uranium demand through 2045 — a significant vote of confidence from one of the world's most influential investment banks [5]. Nano Nuclear Energy reported Q2 FY2026 results with a per-share loss of $0.18 (beating FactSet estimates of a $0.26 loss) and disclosed $568.7 million in liquidity, while also seeing its stock drop sharply as the market digested the balance between strategic progress and rising costs [45] [19] [46]. Energy Fuels posted $36 million in Q1 revenue with a new CEO setting an execution agenda across uranium, rare earths, and heavy mineral sands [47]. Denison Mines commenced site preparation and early works for the Phoenix ISR uranium mine, while Ur-Energy reported Q1 revenue of $3.9 million with production ramping at Lost Creek and Shirley Basin [48] [49]. Cameco was touted by analysts as a "nuclear fuel champion" positioned to convert today's energy crisis into long-term wealth, and TC Energy's Bruce Power stake was profiled as adding a nuclear dimension to the company's dividend story [50] [51]. The U.S. imported 95% of its uranium this week by multiple accounts — a figure that continues to drive policy urgency around domestic enrichment and mining, including MIDA's $16.5 million site preparation loan for a Utah enrichment equipment facility [12] [13]. On the insurance front, the industry continued to discuss models for covering advanced reactor first-of-a-kind risks, though no landmark policy was finalized this week.


Sources

All 0 sources

Nuclear Pulse is an independent weekly intelligence briefing. All information is sourced from publicly available industry publications. No investment advice is provided.

© 2026 Nuclear Pulse — Compiled by Tollaskígyó

May 10Nuclear Pulse — May 10, 2026

Covering: M
Published: May 10, 2026

1. Executive Summary

The United States secured its largest-ever single international shipment of high-assay low-enriched uranium — 1.7 tonnes transferred from Japan — in a landmark nonproliferation and supply chain milestone that directly advances the Trump administration's HALEU Availability Program [1]. Ontario committed CAD300 million to pre-development work on the Bruce C project, a proposed 4.8 GW nuclear power plant that would make Bruce Power the world's largest nuclear generating facility [2]. The US Department of Transportation's Maritime Administration launched an unprecedented initiative to develop small modular reactors for commercial shipping, explicitly framing the effort as a matter of strategic competitiveness against foreign rivals [3]. Aalo Atomics cleared one of the most rigorous regulatory gates in the DOE framework with approval of its Documented Safety Analysis for the Aalo-X experimental reactor at Idaho National Laboratory, keeping the company on track for criticality by July 4, 2026 [4]. The ITER megaproject in southern France received the final shipment of its 59-foot, 3,000-tonne central solenoid magnet — the culmination of 15 years of fabrication — even as a wave of private fusion ventures increasingly calls the project's €22 billion timeline-to-relevance into question [5].

2. Geopolitical & Strategic Analysis

The week's developments collectively underscore a nuclear energy sector that has decisively moved from policy ambition to industrial execution, with energy sovereignty emerging as the dominant strategic logic across both established and aspiring nuclear nations. The historic transfer of 1.7 tonnes of HALEU from Japan to the United States represents far more than a logistical achievement — it is a carefully choreographed exercise in nuclear security cooperation that simultaneously reduces proliferation risks, strengthens the US domestic advanced reactor fuel supply chain, and demonstrates the enduring depth of the US-Japan strategic partnership at a moment when global nuclear fuel markets are fragmenting along geopolitical lines [1]. The sheer scale of the operation, described by the National Nuclear Security Administration as the largest single international uranium shipment in its history, signals that Washington is prepared to deploy substantial diplomatic and operational resources to secure fuel supplies for its next-generation reactor fleet [1]. Ontario's Bruce C pre-development funding, meanwhile, positions Canada not merely as a uranium supplier — the country already produces roughly 24% of global mine supply — but as a vertically integrated nuclear powerhouse capable of converting mineral endowment into domestic energy security at a scale that rivals any nation's ambitions [2]. The decision by the US Maritime Administration to launch an SMR-for-shipping initiative explicitly acknowledged that "global competitors are advancing the integration of nuclear propulsion" and that the absence of a domestic programme places the US "at a strategic disadvantage" [3]. This framing — nuclear technology as an instrument of competitiveness and energy dominance — is increasingly the language of the entire sector, supplanting the climate-centric narratives that dominated the previous decade [3]. The NRC's parallel move to relax rules on foreign investment from OECD countries and India further signals that the US regulatory apparatus is pivoting from gatekeeping to enabling, recognising that the capital requirements of a nuclear renaissance exceed what domestic sources alone can provide [6].

3. Regional Developments

North America

The United States experienced a concentrated burst of regulatory and industrial activity across the advanced nuclear spectrum. The Department of Energy's Idaho Operations Office approved the Documented Safety Analysis for Aalo Atomics' Aalo-X experimental reactor, a critical safety-basis approval that clears the path for the facility's final Operational Readiness Review and keeps the company on track to achieve criticality by July 4, 2026 — the deadline set by DOE for at least three test reactors under its expedited demonstration programme [4]. Simultaneously, the NRC approved the Principal Design Criteria topical report for Oklo's Aurora powerhouse, an essential step in validating the safety architecture of the sodium-cooled fast reactor design for commercial deployment [4]. In a parallel track, the NRC signalled its intent to relax restrictions on foreign investment from OECD countries and India, a regulatory reorientation that acknowledges the global capital flows now pursuing US nuclear assets [6]. On the commercial front, Centrus Energy formed a partnership with Palantir Technologies to deploy AI-driven software tools — including Palantir's Foundry and Artificial Intelligence Platform — across its Piketon, Ohio enrichment facility, with the companies identifying approximately $300 million in potential cost savings through optimisation of project controls, manufacturing execution, and supply chain management [7]. The Nuclear Company, the US nuclear deployment firm that emerged in 2024, established a services subsidiary focused on specialty maintenance, outage execution, and workforce augmentation for existing reactor operators [7]. X-energy filed its draft registration statement with the SEC for an initial public offering on the Nasdaq under the symbol "XE," with J.P. Morgan, Morgan Stanley, Jefferies, and Moelis & Company serving as lead joint book-running managers, marking one of the most significant advanced reactor IPOs to date [7].

Europe

Poland's nuclear programme achieved a foundational milestone as the National Atomic Energy Agency (PAA) formally determined — after examining a 700-page preliminary siting report — that the Lubiatowo-Kopalino site on the Baltic coast is suitable for the country's first nuclear power plant, confirming that "none of the factors precluding the construction of nuclear power facilities existed at the site under consideration" [8]. Bechtel simultaneously signed a contract with Polish firm Doraco for the second and third phases of geological and geotechnical surveys, covering auxiliary building areas and marine infrastructure for the associated offloading facility, with work expected to continue through 2027 [7]. In Spain, the nuclear industry's future hung in the balance as Foro Nuclear President Marta Ugalde outlined the case for a government decision — expected later this year — on a three-year operating reprieve for the Almaraz nuclear power plant, currently scheduled to begin shutting down in 2027 under a 2019 phase-out agreement [9]. Ugalde noted that Spain's political and public opinion landscape has shifted considerably since 2019, with the 2025 national blackout, the Iran conflict, and AI-driven electricity demand projections all contributing to what she described as a "much more pragmatic" debate where nuclear is increasingly "seen as part of the solution" [9]. Sweden's Studsvik acquired Kärnfull Next AB, expanding from fleet support into new nuclear project development, a move that coincides with the Swedish government's introduction of financing mechanisms to support new builds [7]. In the United Kingdom, Great British Energy–Nuclear selected Arup to provide early-phase foundation engineering and design support for the Wylfa SMR project in Wales, with LDA Design, TÜV SÜD Nuclear Technologies, Mace Consult, and Gleeds all contributing to the optioneering and site-specific concept design [7]. X-energy UK Holdings and Centrica signed an MOU with Hartlepool Borough Council to establish a Nuclear and Electrical Trades Academy for technical education in nuclear-related careers [7].

Asia

A notable development in Southeast Asia emerged as GE Vernova and Hitachi signed a memorandum of understanding to identify opportunities for the commercial deployment of the BWRX-300 small modular reactor across the region, with the companies committing to incorporate qualified Japanese suppliers into the partnership and strengthen the supply chain for future deployments [7]. The BWRX-300 is already under construction at Ontario Power Generation's Darlington site, lending commercial credibility to the Southeast Asian exploration [7]. In Japan, X-energy signed a nonbinding MOU with IHI Corporation to explore collaboration in high-temperature gas-cooled reactor technology, focusing specifically on the design, engineering, manufacturability, and supply chain development of main power system pressure boundary components — including the reactor pressure vessel, steam generator pressure vessel, and cross vessel — to support eventual deployment of the Xe-100 advanced reactor [7]. Realta Fusion, based in Wisconsin, formed a strategic partnership with Japan's Kyoto Fusioneering to jointly develop plasma heating systems for magnetic mirror fusion machines and tritium blanket breeding and fuel cycle systems, with gyrotrons purchased from Kyoto Fusioneering slated for installation at Realta's planned Realta Forge research facility [7]. In South Korea, HD Korea Shipbuilding & Offshore Engineering contributed a rendering of a 15,000 TEU-class SMR-powered containership as part of the US Maritime Administration's Request for Information process, highlighting the transnational industrial interest in nuclear maritime propulsion [3].

Middle East & Africa

No confirmed nuclear energy developments from the Middle East or Africa regions were published during the May 4–10 reporting period that met the seven-day validation threshold. The El Dabaa project in Egypt and regional initiatives in the Gulf states did not generate actionable news within the reporting window.

4. Technology & Innovation

The week produced a dense cluster of technology developments spanning fuel innovation, microreactor instrumentation, and AI-driven nuclear infrastructure. Clean Core Thorium Energy announced that its patented ANEEL thorium-based fuel — designed as a drop-in replacement for existing pressurised heavy water reactor and CANDU fuel bundles — successfully reached over 60 GWd/MTU of burnup in the Advanced Test Reactor at Idaho National Laboratory, a milestone representing more than eight times the typical discharge burnup of traditional PHWRs and CANDU reactors [10]. The achievement is significant because ANEEL fuel retains the same external geometry as existing 19- and 37-element fuel bundle designs, meaning it can theoretically be deployed without major reactor modifications while delivering substantially improved performance, reduced waste volumes, and enhanced proliferation resistance [10]. Less than two years after irradiation began in May 2024, the four remaining rodlets in the highest burnup cohort will now proceed to post-irradiation examination at INL's Materials and Fuels Complex [10]. In the microreactor space, Hadron Energy signed a nonbinding MOU with Paragon Energy Solutions — a Mirion Technologies company — establishing a framework for developing the instrumentation and control architecture for Hadron's Halo microreactor, covering safety and non-safety I&C platform integration, control logic development, human-machine interface support, and cybersecurity considerations, with Paragon also supplying physical instrumentation devices [7]. Cambridge Atomworks signed an MOU with Mott MacDonald to accelerate development of the Odin microreactor, targeting energy-intensive industries and off-grid installations, while Nano Nuclear Energy completed conceptual designs for two optimised HALEU fuel payload baskets and a preliminary design for the transport package overpack through its Advanced Fuel Transportation subsidiary [7]. On the enrichment front, the Centrus-Palantir partnership represents perhaps the most consequential AI-nuclear integration to date, applying Palantir's Foundry platform to optimise project controls, engineering, manufacturing execution, supply chain management, and regulatory compliance at the Piketon enrichment facility, with the identified $300 million in potential efficiencies including reductions in manufacturing lead times and acceleration of the enrichment capacity expansion timetable [7]. ZettaJoule, which is modernising Japan's HTTR technology for industrial heat applications, opened an office at the Ion innovation hub at Rice University in Houston, signalling its intent to target oil and gas, steelmaking, aviation, data centre, and e-fuel markets [7].

5. Fusion Research

The fusion sector registered a symbolically charged milestone this week as the ITER project in Cadarache, France, received the final shipment of components for its central solenoid magnet — a 59-foot, 3,000-tonne superconducting system that has been 15 years in the making, with each individual module requiring a two-year process for fabrication and testing at Oak Ridge National Laboratory [5]. The solenoid, described as the beating heart of the kilometre-long tokamak, generates the magnetic fields necessary to confine plasma at temperatures exceeding 150 million degrees Celsius, and its completion clears one of the last major component-delivery hurdles on ITER's path to first plasma [5]. Yet the celebratory tone was tempered by a growing chorus of analysis questioning ITER's relevance in an increasingly privatised fusion landscape. At €22 billion and counting, with first plasma still years away and no grid-connected electricity ever planned from the facility, the megaproject is being outpaced in timeline-to-impact terms by a wave of well-funded private startups [5]. Commonwealth Fusion Systems, an MIT spinout, has already applied for grid interconnection through PJM — the first-ever such request from a grid-scale fusion developer to a major regional transmission organisation — for its ARC fusion power plant targeted for the early 2030s [11]. Realta Fusion's partnership with Kyoto Fusioneering, announced this week, adds another dimension to the private fusion ecosystem, focusing on magnetic mirror confinement — a fundamentally different approach from the tokamak design — with joint development targeting plasma heating systems, neutron sources for materials qualification, and tritium fuel cycle systems [7]. Bill Gates captured the private-sector thesis succinctly: "If you know how to build a fusion power plant, you can have unlimited energy anywhere and forever. It's hard to overstate what a big deal that will be" [5]. ITER's defenders argue that its looming obsolescence is paradoxically a sign of success — that its achievements and profile catalysed the very private investment now threatening to render it redundant — and that it stands as a vanishingly rare symbol of international scientific cooperation in an otherwise nationalistic energy era [5].

6. Market & Economic Intelligence

The uranium market continued to exhibit structural tightness as multiple supply and demand signals converged during the reporting week. The U3O8 spot price, while not publicly updated through free-access indicators at the time of compilation due to industry-standard paywalls (UxC, Numerco, and TradeTech all restrict real-time pricing to paid subscribers), maintained its elevated trajectory above the $85 per pound threshold based on the last confirmed public print of $86.45 on April 25, with the weekly trend assessed as stable-to-upward [12]. The long-term price indicator remained anchored at $90 per pound, with forward curves showing three-year and five-year prices at $101 and $108 respectively — a steep contango structure that reflects the market's conviction that current production is inadequate to meet projected demand growth [12]. The Sprott Physical Uranium Trust continued as the dominant spot-market force, having accumulated over one million pounds since mid-April and raising in excess of $118 million by trading at a premium to net asset value [12]. On the production side, Anfield Energy released a bullish Preliminary Economic Assessment on its Utah and Colorado uranium projects, with the company characterising the results as providing "strong evidence of true value" at a moment when domestic US uranium production commands a growing jurisdictional premium [13]. The uranium enrichment market was separately projected by industry analysts to reach $30.2 billion by 2035, reflecting the anticipated expansion of capacity required to service the global reactor fleet — a projection that contextualises the urgency behind the Centrus-Palantir AI efficiency drive and the historic HALEU shipment from Japan [14]. At the corporate level, Snow Lake Resources rebranded as Frontier Nuclear and Minerals Inc. (Nasdaq: FNUC), explicitly repositioning as a vertically integrated nuclear fuel cycle company spanning uranium exploration, enrichment technology investment, and SMR exposure, while Mangiarotti — a Westinghouse subsidiary — renamed itself Westinghouse Electric Italy, transforming into a nuclear manufacturing hub for AP1000 and AP300 projects in the US, Poland, and Bulgaria [7]. Fluor Corporation opened a Bucharest office to support Romanian nuclear projects including the Doicești SMR deployment and Cernavoda expansion [7]. The cumulative signal from the week's market activity is unambiguous: capital, corporate restructuring, and strategic partnerships are all aligning around a conviction that the nuclear fuel cycle — from mine to megawatt — is entering a sustained investment super-cycle driven by structural supply deficits, geopolitical fuel segmentation, and the seemingly insatiable electricity demands of artificial intelligence [1][2][7][12].


Sources

All 14 sources
  1. World Nuclear News, "USA and Japan mark historic HALEU shipment," May 8, 2026.
  2. World Nuclear News, "Funding boost for Bruce C pre-development work," May 8, 2026.
  3. World Nuclear News, "USA to examine SMRs for commercial shipping," May 8, 2026.
  4. World Nuclear News, "Licensing of US pilot SMRs advances," May 7, 2026.
  5. OilPrice.com (Haley Zaremba), "The World's Biggest Fusion Reactor Just Hit a Milestone," May 6, 2026.
  6. NucNet, "US NRC Looks To Relax Rules On Overseas Stakes In Nuclear Industry," May 5, 2026.
  7. American Nuclear Society, "Industry Update—May 2026," May 4, 2026.
  8. World Nuclear News, "Site of Polish plant deemed suitable," May 8, 2026.
  9. World Nuclear News, "Podcast: Will Spain rethink nuclear energy phase-out plan?" May 6, 2026.
  10. World Nuclear News, "Innovative thorium-based fuel concludes irradiation campaign," May 7, 2026.
  11. World Nuclear News, "Grid connection requested for US fusion power plant," April 30, 2026. (Note: published outside the seven-day reporting window but cited as relevant contextual background for fusion developments within the reporting week.)
  12. Nuclear Pulse Issue #29, "Uranium spot market data," May 3, 2026, referencing UxC and TradeTech data for the week ending April 25, 2026.
  13. NucNet, "Anfield Energy Releases Bullish PEA On Utah And Colorado Uranium Projects," May 7, 2026.
  14. Investing News Network, "Uranium Enrichment Market Expected to Hit US$30.2 Billion by 2035," May 7, 2026.

Nuclear Pulse is an independent weekly intelligence briefing. All information is sourced from publicly available industry publications. No investment advice is provided.

© 2026 Nuclear Pulse — Compiled by Tollaskígyó

May 3Nuclear Pulse — May 3, 2026

Covering: A
Published: May 3, 2026

1. Summary

The global nuclear sector experienced a watershed week as the US NRC issued its final construction license for TerraPower's Natrium reactor in Wyoming, formally marking the start of full-scale construction on America's first utility-scale advanced nuclear plant and validating two decades of advanced reactor development [1]. Belgium executed a historic policy reversal with Prime Minister De Wever announcing a full nationalisation of the country's seven nuclear reactors, abandoning the long-standing phase-out law in favor of energy sovereignty [2]. India achieved a momentous milestone with the Kalpakkam Prototype Fast Breeder Reactor (PFBR) attaining first criticality, positioning the country as only the second nation to operate a commercial fast breeder reactor [3]. Canada unveiled its most ambitious nuclear strategy to date, a four-pillar framework encompassing new builds, global exports, uranium production expansion, and fusion/fission innovation, backed by a $40 million microreactor feasibility program for Arctic defence installations [4]. Meanwhile, the uranium spot market demonstrated remarkable resilience, with U3O8 closing the week at $86.45 per pound — up $1.45 week-over-week — driven by sustained financial buying from the Sprott Physical Uranium Trust which raised over $118 million in late April alone [5].


2. Geopolitical & Strategic Analysis

The week's developments collectively signal a structural acceleration in the global re-nuclearisation trend, driven less by climate policy rhetoric and more by hard-nosed energy security calculations. Belgium's decision to nationalise and reverse the phase-out of its nuclear fleet represents the most dramatic European U-turn to date, explicitly framed by the De Wever government as an instrument of energy sovereignty and reduced dependence on fossil fuel imports [2]. This follows a broader European pattern where the Iran conflict's disruption of energy markets has forced even historically nuclear-skeptic member states to re-embrace atomic power as a cornerstone of strategic autonomy [6]. Across the Atlantic, Canada's new national nuclear strategy positions uranium exports — the country produces roughly 24% of global supply from the highest-grade deposits on earth — as a geopolitical asset in an increasingly segmented fuel market where not every pound of uranium is equally acceptable to every buyer [4]. The strategic realignment is equally evident in the US, where TerraPower's Natrium project has survived three changes of administration and party control of Congress, demonstrating that advanced nuclear has achieved a rare bipartisan durability in American energy policy [1]. In Bulgaria, the smooth progression of Kozloduy Unit 5's transition from Russian to Westinghouse fuel — the first such successful VVER-1000 diversification in the EU — provides a practical template for other Eastern European states seeking to decouple their nuclear supply chains from Russian dependency [7]. Collectively, these moves reflect an industry transitioning from policy ambition to execution, where nuclear technology is increasingly wielded as an instrument of soft power and energy diplomacy in a fragmenting geopolitical landscape.


3. Regional Developments

North America

The centerpiece of the week was the NRC's final approval of TerraPower's construction license for the Natrium reactor in Kemmerer, Wyoming, enabling full-scale construction of America's first utility-scale advanced nuclear power plant [1]. TerraPower CEO Chris Levesque framed the milestone as proof that advanced nuclear technology is real and deployable, noting that the project has progressed through five years of regulatory review spanning multiple administrations of both parties [1]. The Natrium plant, backed by $2 billion in federal cost-sharing and a commercial agreement with META for additional reactors to power data centers, embodies the convergence of tech-sector energy demand and advanced nuclear deployment that the IEA projects will require a 130% increase in data center energy consumption by 2030 [1]. Simultaneously, the NRC granted subsequent licence renewals to Florida's St. Lucie Units 1 and 2, authorising operation until 2056 and 2063 respectively, making them among the latest US reactors approved for 80-year operating lifetimes — a testament to the economic logic of life extension in a capacity-constrained market [8]. Canada's announcement of a transformative new Nuclear Energy Strategy, to be published by end-2026, was the other North American highlight, structured around enabling new builds across provinces, positioning Canada as a global nuclear supplier of choice, expanding uranium and fuel-cycle capacity, and developing innovations across both fission and fusion domains [4]. The companion $40 million microreactor feasibility program for Arctic defence installations signals Ottawa's recognition that nuclear technology is essential to maintaining a sustained defence presence in the North [4].

Europe

Belgium's dramatic policy reversal dominated European nuclear news, with Prime Minister Bart De Wever announcing intentions to fully nationalise all seven nuclear reactors from French operator Engie, explicitly suspending decommissioning plans and committing to "new nuclear capacity" [2]. The move caps a remarkable decade-long pivot for a country that had legislated a complete nuclear phase-out in the early 2000s, and now frames atomic energy as essential to affordability, industrial resilience, and strategic autonomy [2]. In Bulgaria, Nuclear Regulatory Agency Chair Tsanko Bachiyski reported that Kozloduy Unit 5's transition from Russian to Westinghouse fuel is "proceeding smoothly," with two reload batches already in the core and a full core conversion expected by spring 2027 [7]. The successful diversification — the first such program for a VVER-1000 reactor anywhere in the EU — was specifically recognised at the tenth review of the Convention on Nuclear Safety as an area of "good performance," providing a critical proof-of-concept for other Eastern European operators seeking to reduce dependence on Russian nuclear fuel supply chains [7]. Unit 5 is scheduled for a 40-day maintenance and refuelling outage beginning May 9, during which another Westinghouse batch will be loaded [7].

Asia

India's nuclear program achieved a generational milestone as the Prototype Fast Breeder Reactor (PFBR) at Kalpakkam, Tamil Nadu, attained first criticality on April 6, with Minister Jitendra Singh declaring it "a new phase in India's nuclear programme" [3]. The 500 MWe sodium-cooled fast breeder reactor, developed entirely through indigenous Indian engineering, positions India as only the second country globally to operate a commercial-scale fast breeder after Russia, opening the pathway to the country's long-envisioned three-stage nuclear program that aims to utilise its vast thorium reserves [3]. Further south, the Kudankulam Nuclear Power Plant achieved a key commissioning milestone as Unit 3 began "Spillage to Open Reactor" — the critical primary system flushing and testing phase — moving the 1,000 MW VVER unit closer to grid connection and advancing the 6,000 MW project that represents India's largest nuclear power station [9]. In Japan, ITER-related progress continued with the development of tooling for initial blanket assembly, as the international project hosted its 3rd Public-Private Fusion Workshop on April 28-29 in southern France [10].


4. Technology & Innovation

The most significant regulatory innovation of the week — and arguably of the year for advanced nuclear — was the US NRC's publication on May 1 of a landmark proposed rule establishing an entirely new regulatory framework, 10 CFR Part 57, specifically designed for "Licensing Requirements for Microreactors and Other Reactors With Comparable Risk Profiles" [11]. The 139-page proposed rule, which carries an estimated net averted cost of $3.76–11.84 billion over 40 years across an anticipated 2,235 applicants, creates a risk-informed, performance-based pathway that would enable licensing reviews to be completed in 6-12 months, compared to the multi-year timelines under existing Part 50 and Part 52 frameworks designed for large light-water reactors [11]. Key innovations include a dose-based entry criterion of 1 rem TEDE at the site boundary, a 10-metric-ton fuel mass limit, general licenses for certain construction activities of nth-of-a-kind reactors, manufacturing license provisions allowing reactors to be factory-fabricated and fueled before transport to deployment sites, provisions for remote and autonomous operation, and a groundbreaking categorical exclusion from NEPA environmental review when specific criteria are met [11]. The rule explicitly treats fusion devices under an accelerator-adjacent framework rather than a fission reactor framework, and establishes the legal architecture for high-volume manufacturing and deployment of standardised reactor designs — a paradigm shift from the bespoke, site-specific licensing model that has characterised the nuclear industry since its inception [11]. This regulatory modernization, mandated by the ADVANCE Act and Executive Order 14300, represents the most comprehensive reform of US nuclear licensing since the Atomic Energy Act of 1954, and is likely to serve as an international template as other nuclear regulators grapple with accommodating advanced reactor technologies.


5. Fusion Research

Fusion development continued its momentum as ITER hosted its 3rd Public-Private Fusion Workshop on April 28-29, presenting a full set of technical materials covering the growing interface between the publicly-funded megaproject and the expanding ecosystem of private fusion ventures [10]. The workshop coincided with the start of the third operation campaign on SPIDER, the world's most powerful negative ion source at the Neutral Beam Test Facility in Padua, Italy — a critical component for ITER's plasma heating systems that has now completed upgrades and maintenance and entered a new operational phase [10]. In the United States, the National Ignition Facility (NIF) published details of a series of target design breakthroughs that enabled a new fusion energy record, building on the 2022 ignition milestone with improved capsule designs and more precise laser pulse shaping [12]. On the private fusion front, the broader 2026 landscape has been transformed by three major milestones in six months: KSTAR's February achievement of 102-second plasma confinement at 100 million degrees Celsius — more than doubling its own previous world record; China's EAST tokamak demonstrating plasma density exceeding the Greenwald limit, opening a parameter space previously considered inaccessible for tokamak-based fusion; and Helion's Polaris experiment achieving net energy gain, validating the field-reversed configuration approach at commercially relevant scale [13]. The fusion investment landscape reflects this momentum, with the Fusion Industry Association reporting $4.7 billion in private investment in 2025 and 2026 on pace to exceed that figure, while the Helion-Microsoft power purchase agreement stands as the first commercial PPA for privately developed fusion output — a structural template whose execution will define the credibility of private fusion's commercial timeline [13].


6. Market & Economic Intelligence

The uranium spot market demonstrated notable resilience during the week, with the U3O8 spot price closing at $86.45 per pound on April 25, up from $85.00 at the start of the week — a $1.45 gain driven primarily by sustained financial buying despite a late-week softening in activity [5]. The Sprott Physical Uranium Trust (SPUT) was the dominant force, raising over $118 million between April 13 and April 24 by trading at a premium to net asset value, purchasing one million pounds of uranium since April 16 and effectively absorbing available spot-market supply [5]. Fifteen spot transactions were reported covering 1.2 million pounds U3O8, with most deals executing for prompt delivery [5]. Forward indicators continued their upward march, with the three-year forward price reaching $101 per pound and the five-year forward at $108, reflecting the same structural supply-demand tension visible in the term market where the long-term price remained anchored at $90 [5]. The week's trend was decisively upward, with spot prices recovering from late-March lows of $84.25 to near two-month highs, reinforced by clear messaging from the World Nuclear Fuel Cycle Conference that nuclear fuel demand "is now real" and that the goal of tripling nuclear power by 2050 cannot be met without a major increase in funding across the entire fuel cycle [5][14]. On the production side, positive supply signals emerged from Uzbekistan (Navoiyuran's Qizilkok ISR project adding 3.1 million pounds annually), BHP's Olympic Dam (5.5 million pounds over nine months, up 15% year-over-year), and Paladin's Langer Heinrich (1.29 million pounds in the March quarter with full-year guidance raised to 4.5–4.8 million pounds), yet the scale of these additions remains insufficient to close a structural supply gap exacerbated by the growing segmentation of acceptable supply by jurisdiction, origin, and geopolitical alignment [5]. The market's key structural challenge — that demand growth is outpacing mine development timelines, where uranium projects take years to permit, finance, build, and commission — was a central theme at the World Nuclear Fuel Cycle Conference, where industry leaders framed the moment as "a moment of reckoning" for uranium mining [5].


Sources

All 14 sources
  1. NPR, "Wyoming celebrates 'nuclear renaissance' as feds approve license for a new reactor," May 2, 2026.
  2. BBC News, "Belgium plans to nationalise nuclear power plants," April 30, 2026.
  3. The Economic Times Energyworld, "Kalpakkam PFBR criticality marks new phase in India's nuclear programme: Minister Jitendra Singh," April 30, 2026.
  4. Canada Newswire, "Government of Canada Commits to New Strategy for Nuclear Energy," April 29, 2026.
  5. Purepoint Uranium Group, "Spot Pricing Remains Resilient, Even When Day to Day Activity Softens," April 28, 2026.
  6. Foreign Policy, "The Iran War Is Pushing Europe Back to Nuclear Energy," March 25, 2026.
  7. Bulgarian News Agency (BTA), "Kozloduy Unit 5 Switch to Westinghouse Fuel 'Proceeding Smoothly'," April 28, 2026.
  8. World Nuclear News, "US NRC clears St Lucie 1 and 2 for 80-years operation," April 29, 2026.
  9. The Economic Times Energyworld, "NPCIL achieves key milestone at Kudankulam Unit-3," April 29, 2026.
  10. ITER Organization, "What's New — ITER news digest," April 27, 2026.
  11. US Federal Register, "Licensing Requirements for Microreactors and Other Reactors With Comparable Risk Profiles" (Proposed Rule, 91 FR 23628), May 1, 2026.
  12. Lawrence Livermore National Laboratory, "Target Breakthrough Enabled Fusion Record at NIF," April 15, 2026.
  13. NextWave Insight, "Nuclear Fusion 2026: Three Milestones Shift the Commercial Timeline," 2026.
  14. ANS Nuclear Newswire, "Uranium prices are trading at two-month lows," April 3, 2026.

Nuclear Pulse is an independent weekly intelligence briefing. All information is sourced from publicly available industry publications. No investment advice is provided.

© 2026 Nuclear Pulse — Compiled by Tollaskígyó

Apr 26Nuclear Pulse — April 26, 2026

Covering: April 20–26, 2026
Published: April 26, 2026

Issue 19 | Week of April 20–26, 2026 | Prepared: April 26, 2026


1. Summary

The defining development of this week is the commencement of construction on TerraPower’s Natrium sodium-cooled fast reactor in Kemmerer, Wyoming, marking the first utility-scale advanced nuclear build in the United States to break ground under a modern non-light-water design and signaling a genuine inflection point for the domestic advanced reactor industry [1]. South Korea’s KSTAR tokamak achieved a historic fusion milestone by sustaining plasma at 100 million degrees Celsius for 102 seconds, more than doubling its previous record and receiving independent verification from the IAEA, which underscores the accelerating credibility of magnetic confinement fusion as a long-term energy pathway [2]. Germany’s Wendelstein 7-X stellarator also set a new benchmark by maintaining high-performance fusion conditions for 43 seconds with plasma temperatures reaching 30 million degrees, demonstrating that stellarator architectures are rapidly closing the performance gap with tokamaks [3]. The European Union’s 20th sanctions package against Russia conspicuously exempted Rosatom from nuclear fuel restrictions, exposing Europe’s persistent strategic dependency on Russian nuclear services despite repeated commitments to energy sovereignty [4]. India’s Atomic Energy Commission approved a foreign direct investment policy framework under the proposed SHANTI Act, clearing a pathway for private capital and foreign investors to participate in the country’s ambitious 100 GW nuclear expansion target [5].


2. Geopolitical & Strategic Analysis

The industry mood this week is one of cautious exhilaration tempered by the cold realities of supply chain geopolitics. The breakthroughs in fusion research—KSTAR’s 102-second plasma confinement and Wendelstein 7-X’s 43-second stellarator performance—have shifted the narrative from "fusion is always 30 years away" to "fusion may be 10 years from commercial relevance," injecting fresh optimism into a sector that has weathered decades of skepticism [2][3]. Yet this scientific momentum stands in sharp contrast to Europe’s continued paralysis on nuclear fuel independence. The EU’s 20th sanctions package, adopted on April 23, deliberately preserved Rosatom’s nuclear fuel supply channels, revealing the uncomfortable truth that Europe’s energy sovereignty rhetoric remains disconnected from its procurement practices [4]. This duality—aggressive sanctions on Russian oil and gas alongside continued reliance on Russian enriched uranium and reactor services—has created a two-tiered dependency that weakens the continent’s strategic position. The Iran war’s energy shock, which has rippled through global oil markets and elevated LNG prices, has paradoxically strengthened the nuclear case in developing economies across Africa and Asia, where nations are now viewing atomic energy as a hedge against fossil fuel volatility [19]. Ukraine’s energy system, battered by years of Russian strikes on thermal and hydropower infrastructure, has become increasingly dependent on its remaining nuclear fleet as the backbone of grid stability, illustrating how nuclear plants serve as critical infrastructure during conflict [14]. Canada’s Bruce Power has extended its nuclear expertise into Alberta and Saskatchewan through new collaboration agreements, signaling a North American consolidation of nuclear knowledge as provinces without existing nuclear infrastructure begin serious assessments of large-reactor deployment [6][7]. Taken together, the strategic landscape suggests that nuclear technology is becoming both a hedge against energy volatility and a vector of geopolitical soft power, with nations possessing indigenous reactor expertise gaining outsized influence in the emerging global nuclear marketplace.


3. Regional Developments

North America

The United States advanced nuclear sector achieved a watershed moment on April 23 when TerraPower broke ground on its Natrium sodium-cooled fast reactor plant in Kemmerer, Wyoming, following the NRC’s issuance of the first construction permit ever granted for a commercial non-light-water power reactor [1]. The project, backed by Bill Gates and developed in partnership with Southern Company, represents a $4 billion investment and will incorporate a molten salt energy storage system designed to provide grid flexibility unmatched by conventional nuclear designs. This construction start was accompanied by two other significant regulatory milestones: Kairos Power broke ground on its Hermes 2 Demonstration Plant in Oak Ridge, Tennessee, on April 17, advancing the company’s fluoride salt-cooled high-temperature reactor technology under its Google partnership [8], and First American Nuclear submitted a regulatory engagement plan to the NRC on April 15 for its EAGL-1 fast-spectrum small modular reactor, claiming the design is licensable under existing regulations [9]. Meanwhile, Blue Energy secured $380 million in financing to pursue an innovative shipyard-based construction model for nuclear power plants, aiming to slash build times and costs by moving fabrication into controlled manufacturing environments [10]. In Canada, Bruce Power signed memoranda of understanding with both SaskPower and Energy Alberta to share expertise in large reactor development, extending Ontario’s nuclear knowledge base into provinces previously without atomic energy programs and reinforcing the cross-border trend of nuclear capability consolidation [6][7].

Europe

Europe’s nuclear landscape this week was dominated by the tension between energy sovereignty rhetoric and procurement reality. The EU’s 20th sanctions package, formally adopted on April 23, notably excluded Rosatom from nuclear fuel restrictions, allowing continued Russian uranium enrichment services and technical cooperation to flow to European utilities [4]. This decision, taken despite pressure from Ukraine and some member states, reflects the continent’s inability to quickly replace Russian nuclear fuel services, with European nuclear plants still dependent on Moscow for approximately 20 percent of their enrichment capacity. In the United Kingdom, the government committed up to £599 million through the National Wealth Fund to support Rolls-Royce’s small modular reactor program, with design work now formally contracted and a factory site planned at the former Wylfa nuclear station on Anglesey [11]. France affirmed that its nuclear industry will remain a major contributor to European electricity production, expressing optimism about the European Commission’s ongoing state aid investigation [12]. In Bulgaria, the engineering services contract for two new Westinghouse AP1000 units at Kozloduy was extended as work continued on cost and schedule refinements, with Sofia preparing to notify Brussels of state aid plans for the project [13]. Germany, meanwhile, saw renewed political debate over its 2023 nuclear phase-out, with analysts arguing that the country must restart its remaining shuttered reactors to reduce gas dependency, though no policy reversal appears imminent [12].

Asia

Asia continued its role as the primary growth engine for global nuclear capacity this week. In China, the first unit at the Taipingling nuclear power plant entered commercial operation on April 20, marking the debut of the domestically designed Hualong One reactor in the Guangdong-Hong Kong-Macao Greater Bay Area and adding significant capacity to the booming Yangtze Delta region [15]. Beijing’s broader plan to commission seven new nuclear reactors in 2026 remains on track, reinforcing China’s position as the world’s largest reactor builder. In Japan, Tokyo Electric Power Company resumed commercial operations at Unit 6 of the Kashiwazaki-Kariwa nuclear plant on April 16, ending a 14-year offline period for the reactor and potentially boosting annual profits by approximately $630 million as the facility—once the world’s largest nuclear plant—gradually returns to service [16]. In South Korea, the KSTAR tokamak at the Korea Institute of Fusion Energy achieved its historic 102-second plasma milestone in February, with the result receiving IAEA verification and global scientific attention this week [2]. The achievement was further contextualized by ITER’s successful real-time control of KSTAR plasma using its CODAC system in March, demonstrating interoperability between Korea’s domestic program and the international ITER framework [17]. In India, the Atomic Energy Commission approved a draft foreign direct investment policy for the nuclear sector under the proposed SHANTI Act, with inter-ministerial consultations now underway; the policy is expected to open India’s nuclear market to private Indian firms and foreign investors as the country pursues its 100 GW target [5]. India also announced plans to invite bids within three to six months for a 220 MWe Bharat Small Modular Reactor, marking a concrete step toward indigenous SMR deployment [18].

Middle East & Africa

The Middle East and Africa region demonstrated both the risks and opportunities of nuclear expansion in geopolitically complex environments. Egypt and Russia reinforced their $25 billion partnership to fast-track construction of the El Dabaa Nuclear Power Plant on the Mediterranean coast, with both sides pledging to accelerate timelines despite the broader deterioration in Egypt-Russia diplomatic relations stemming from the Iran war [19]. In Uzbekistan, concrete bedding work began in April for the country’s first nuclear power plant in the Jizzakh region, a small-capacity facility being built with Russian assistance [20]. The Iran war’s energy shock has reverberated across developing economies in Africa and Asia, where soaring oil and LNG prices have driven renewed interest in nuclear power as a hedge against fossil fuel volatility [21]. The International Atomic Energy Agency continued its support for research reactor safety and utilization across Africa, underscoring the organization’s role in building nuclear capacity on a continent where several nations are exploring first reactor programs [22].


4. Technology & Innovation

The technology landscape this week was defined by construction milestones and novel manufacturing approaches that could reshape how nuclear plants are built. TerraPower’s Natrium reactor, which began construction in Wyoming on April 23, represents a sodium-cooled fast reactor integrated with a molten salt energy storage system—a configuration designed to provide not just baseload power but also load-following capability that complements intermittent renewables [1]. The NRC’s construction permit for Natrium is historically significant as the first ever issued for a commercial non-light-water reactor, establishing a regulatory precedent that could accelerate licensing for other advanced designs. Kairos Power’s Hermes 2 Demonstration Plant in Oak Ridge advances a fluoride salt-cooled high-temperature reactor with a compact design intended for rapid factory fabrication [8]. Perhaps the most disruptive manufacturing innovation came from Blue Energy, which raised $380 million to pursue shipyard-based nuclear construction, drawing inspiration from the historical precedent of submarine reactors and the modern success of LNG export terminal prefabrication [10]. By moving reactor fabrication into shipyard environments, Blue Energy aims to replace field welding with automated manufacturing, cutting construction schedules in half while improving quality control. First American Nuclear’s EAGL-1 fast-spectrum SMR, which submitted its regulatory engagement plan this week, claims licensability under existing NRC regulations—a design philosophy that avoids the regulatory uncertainty facing novel reactor concepts [9]. In India, the Bharat SMR program represents an effort to standardize a 220 MWe pressurized heavy water reactor for serial production, leveraging decades of indigenous PHWR experience [18]. Collectively, these developments suggest the industry is bifurcating into two paths: evolutionary designs that optimize existing regulatory frameworks, and revolutionary manufacturing approaches that promise to solve nuclear’s cost disease through industrialization rather than engineering novelty.


5. Fusion Research

Fusion research delivered two landmark achievements this week that together suggest the field is exiting its perennial "30 years away" phase and entering an era of measurable progress toward energy-relevant conditions. South Korea’s KSTAR tokamak at the Korea Institute of Fusion Energy sustained plasma at 100 million degrees Celsius for 102 consecutive seconds in February 2026, more than doubling its previous 48-second record and receiving independent verification from the IAEA [2]. This duration, achieved using superconducting magnets operating near absolute zero to confine plasma seven times hotter than the Sun’s core, represents a decisive step toward the sustained operation required for commercial fusion. The achievement was complemented by ITER’s successful deployment of its plasma control system on KSTAR in March, where ITER’s CODAC architecture demonstrated real-time control of Korean plasma conditions, validating the software and control infrastructure that will be essential for ITER’s own operations [17]. In parallel, Germany’s Wendelstein 7-X stellarator achieved a record 43-second duration of high-performance fusion conditions with plasma temperatures reaching 30 million degrees, setting a new benchmark for stellarator triple product—a key metric combining plasma density, temperature, and confinement time that determines proximity to energy breakeven [3]. The Wendelstein 7-X result is particularly significant because stellarators, with their inherently stable magnetic confinement, offer advantages for continuous operation compared to pulsed tokamak designs. While China’s EAST device has achieved longer absolute plasma durations exceeding 1,000 seconds, the KSTAR and Wendelstein 7-X results stand out for combining duration with high-performance conditions rather than mere endurance [3]. Commonwealth Fusion Systems, the MIT spinout that has raised approximately $3 billion in private funding, announced this week that its SPARC demonstration reactor in Massachusetts is more than 75 percent complete and will achieve first plasma in 2027, with construction of a 400-megawatt commercial plant in Virginia targeted to begin immediately thereafter [23]. CEO Bob Mumgaard, who was appointed to President Trump’s science advisory council in March, told Reuters that the company is exploring additional sites in the U.S. Rust Belt and internationally, including the UK, Germany, Japan, and Korea [23].


6. Market & Economic Intelligence

The uranium market exhibited characteristic thin-market responsiveness this week, with spot prices trading in a narrow range around $85–87 per pound U3O8. Trading Economics data indicates uranium futures settled at $86.80 per pound on April 24, down 0.40 percent from the prior day but up approximately 3 percent over the past month and 30 percent year-on-year [24]. The spot market has stabilized following a pullback from January’s peak near $94 per pound, with the correction attributed to modest increases in primary mine production from Kazakhstan and Canada alongside reduced speculative interest from financial vehicles like the Sprott Physical Uranium Trust [25]. Despite spot softness, the term contract market remains robust, with utilities continuing to secure long-term supplies at premiums of $95–110 per pound, reflecting confidence in sustained nuclear expansion [25]. The market structure remains fundamentally tight: global mine production of approximately 140 million pounds annually falls short of reactor requirements exceeding 180 million pounds, with the deficit filled by secondary sources including weapons-origin material and utility inventories that are gradually depleting [25]. Paladin Energy’s Langer Heinrich mine in Namibia continues its ramp toward nameplate capacity of 6 million pounds annually, with the company reporting production of 1.23 million pounds in Q2 FY2026 and tracking toward 4.0–4.4 million pounds for the full fiscal year; realized prices of $71.80 per pound and unit costs of $39.70 per pound demonstrate healthy margins at current market levels [25]. On the financing front, Blue Energy’s $380 million raise for shipyard-based nuclear construction represents a significant capital commitment to manufacturing innovation [10], while the UK’s £599 million support for Rolls-Royce SMRs signals government willingness to underwrite nuclear industrial policy [11]. Insurance markets also showed movement this week, with Marsh Risk securing coverage for TerraPower’s Natrium construction, marking an important milestone in risk transfer for first-of-a-kind advanced reactor projects [26].


Sources

All 26 sources
  1. TerraPower. "TerraPower Commences Construction on America's First Utility-Scale Advanced Nuclear Power Plant." PR Newswire, April 23, 2026.
  2. Korea Institute of Fusion Energy (KFE). "KSTAR Sustains 100 Million Degree Plasma for 102 Seconds." Verified by IAEA. Reported by CPG Click Oil and Gas, April 22, 2026.
  3. Max Planck Institute for Plasma Physics. "Wendelstein 7-X Achieves New Performance Records in Fusion Research." Update, April 2026. Reported by Hardware Busters, April 21, 2026.
  4. Dumenko, Vlada. "Save all living things: Europe's 20th sanctions package still spares Russia's nuclear war machine." Euromaidan Press, April 24, 2026.
  5. Mishra, Twesh. "SHANTI Act push: Atomic Energy Commission clears FDI policy, sends it for inter-ministerial consultation." The Indian Express, April 18, 2026.
  6. Bruce Power. "Bruce Power and SaskPower sign memorandum of understanding to inform Saskatchewan large reactor technology assessment." Press Release, April 15, 2026.
  7. Bruce Power. "Bruce Power and Energy Alberta enter into a Collaboration Agreement on nuclear energy in Alberta." Press Release, April 16, 2026.
  8. Kairos Power. "Kairos Power Breaks Ground on Hermes 2 Demonstration Plant." Globe Newswire, April 17, 2026.
  9. First American Nuclear (FANCO). "First American Nuclear Submits Regulatory Engagement Plan for Fast-Spectrum Small Modular Reactor (SMR)." Press Release, April 15, 2026.
  10. De Chant, Tim. "Blue Energy raises $380M to build grid-scale nuclear reactors in shipyards." TechCrunch, April 21, 2026.
  11. National Wealth Fund (UK). "National Wealth Fund commits up to £599m to Rolls-Royce SMR." Press Release, April 13, 2026.
  12. Dalton, David. "France Says Nuclear Industry Will Be Major Contributor To Europe's Electricity Production." NucNet, April 2, 2026.
  13. Dalton, David. "Contract Extension Agreed For Kozloduy Nuclear Project As Work Continues On Cost And Schedule." NucNet, April 21, 2026.
  14. Khan, Sana. "War Forces Ukraine to Rely Heavily on Nuclear Power as Energy Infrastructure Crumbles." Modern Diplomacy, April 22, 2026.
  15. World Nuclear News. "First Taipingling unit enters commercial operation." April 20, 2026.
  16. Nikkei Asia. "TEPCO resumes commercial operations at world's largest nuclear plant." April 16, 2026.
  17. ITER Organization. "On KSTAR, ITER's plasma control system successfully takes charge." April 13, 2026.
  18. Economic Times (India). "India to invite bids for 220 MWe Small Modular Reactor, boosting nuclear push under green energy transition." April 16, 2026.
  19. Nathan. "El Dabaa Nuclear Power Plant Fast-Tracked as Egypt and Russia Reinforce $25 Billion Partnership." Construction Review Online, April 13, 2026.
  20. Rosatom Newsletter. "Concrete for Uzbek NPP." April 20, 2026.
  21. Olingo, Allan, and Anton L. Delgado. "Iran war energy shock drives nuclear power plans in hard-hit Asia and Africa." AP News, April 17, 2026.
  22. Energy News. "IAEA Supports Research Reactor Safety and Utilization Efforts in Africa." April 2026.
  23. Gardner, Timothy. "First commercial fusion plant nears construction in US, Commonwealth CEO says." Reuters, April 21, 2026.
  24. Trading Economics. "Uranium Price." Data updated April 26, 2026.
  25. Purepoint Uranium Group. "Uranium Spotlight Podcast — April 7, 2026." Published April 7, 2026.
  26. Insurance Business Magazine. "Marsh structures insurance for TerraPower nuclear project." March 26, 2026.

Nuclear Pulse is an independent weekly intelligence briefing. All information is sourced from publicly available industry publications. No investment advice is provided.

© 2026 Nuclear Pulse — Compiled by Tollaskígyó

Apr 19Nuclear Pulse — April 19, 2026

Covering: A
Published: April 19, 2026

Summary

India's Prototype Fast Breeder Reactor at Kalpakkam achieved first criticality on April 7, marking the country's definitive entry into Stage 2 of its three-stage nuclear programme and sending a powerful signal about breeder technology's viability for energy sovereignty [1]. The United Kingdom greenlit construction at Wylfa and signed a landmark Rolls-Royce SMR agreement worth nearly £600 million, committing to three small modular reactors in North Wales that promise 8,000 jobs [2][3]. The U.S. NRC finalized its long-awaited Part 53 rule, creating the first technology-inclusive licensing pathway for advanced reactors since 1956 [4], while First American Nuclear formally entered the regulatory queue with its lead-bismuth-cooled EAGL-1 fast-spectrum SMR [5]. On the fusion front, ITER's plasma control system achieved first plasma on the KSTAR tokamak in Korea, and the UKAEA unveiled a £2.5 billion 2026–2030 roadmap for commercial fusion [6][7].


Geopolitical & Strategic Analysis

The dominant thread running through this week's developments is the accelerating convergence of energy sovereignty ambitions and nuclear technology as an instrument of geopolitical positioning. India's breeder milestone is not merely technical—it is a sovereign declaration that closed fuel cycles and thorium utilization will reduce dependence on imported uranium, a strategic vulnerability for a nation of 1.4 billion people [1]. Kazakhstan's decision to cut 2026 uranium production by 10% while simultaneously locking 25–35% of its output into bilateral agreements with India further compresses the already-thin spot market, effectively weaponizing supply discipline as a negotiating tool [8]. Meanwhile, the UK's Wylfa commitment and Rolls-Royce SMR deal arrive directly in response to Middle Eastern energy shocks that have reminded European policymakers how quickly fossil supply lines can be disrupted [2][9]. The United States, through the NRC's Part 53 finalization and the introduction of the Nuclear Energy Innovation and Deployment Act in the Senate, is attempting to reclaim regulatory competitiveness against China and Russia, both of which continue to build reactor capacity at pace [4][10]. Nuclear technology is no longer just an energy choice—it is a lever of soft power, and every major player knows it.


Regional Developments

North America. The most consequential development this week was the NRC's publication of corrections to its Part 53 final rule on April 13, following the original March 30 approval, cementing the first new licensing framework for advanced reactors in over three decades [4]. This was complemented by First American Nuclear's submission of its regulatory engagement plan for the EAGL-1 fast-spectrum SMR to the NRC on April 15, a design notable for its lead-bismuth coolant and licensability under existing regulations without novel frameworks [5]. On the legislative front, Senators Mike Lee and Dave McCormick introduced the Nuclear Energy Innovation and Deployment Act on April 14, which would grant DOE broader authority over demonstration reactors and create a Nuclear Energy Launch Pad program to bridge the "valley of death" between demonstration and deployment [10]. At the state level, New Jersey Governor Mikie Sherrill signed legislation lifting a 40-year de facto nuclear moratorium on April 8, joining Kentucky and West Virginia in removing barriers to new nuclear construction this month [11]. In Canada, SaskPower signed a memorandum of understanding with Bruce Power on April 16 to explore large-scale nuclear reactor technology for Saskatchewan, signaling that the prairie province is moving beyond SMR-only planning [12]. The $19.2 million federal workforce development grant for the Davis-Besse Nuclear Power Station in Ohio further underscores the administration's commitment to building the human capital pipeline [13]. Uranium Energy Corp commenced production at its Burke Hollow ISR mine in southern Texas on April 8—the first new U.S. in-situ recovery uranium operation in over a decade—after receiving TCEQ approval [14].

Europe. The UK dominated the European nuclear landscape this week. The government confirmed that construction will begin at the Wylfa site on Anglesey, with Rolls-Royce SMR signing a landmark agreement for three reactors at the site, backed by nearly £600 million in government funding and an estimated 8,000 new jobs [2][3]. The deal is framed explicitly as a response to Middle Eastern energy disruptions and a step toward reducing foreign energy dependence [9]. Separately, the UKAEA unveiled its 2026–2030 organisational strategy on April 14, outlining a £2.5 billion programme to advance the STEP fusion prototype, grow the domestic fusion supply chain, and complete new research facilities at Culham Campus [7]. In Eastern Europe, Poland continues to build the institutional scaffolding for its nuclear programme, with reports that a Polish nuclear insurance pool may be established by the end of 2026, a prerequisite for any commercial reactor project [15]. The Iran-war-driven energy crisis continues to push continental European policymakers back toward nuclear, though concrete new commitments this week were limited to the UK [9].

Asia. India's 500 MWe Prototype Fast Breeder Reactor at Kalpakkam achieved first criticality on April 7, with Prime Minister Modi describing it as a "defining step" in the country's three-stage nuclear programme [1]. The event carries profound implications: it validates sodium-cooled fast reactor technology on the subcontinent and opens the door to Stage 3, which envisions thorium-based reactors that could secure India's energy independence for centuries. In China, construction commenced at Jinqimen Unit 2 with the pouring of first safety-related concrete on April 7, bringing the number of Hualong One units under construction in the country to 14 [16]. Additionally, the outer containment dome was successfully hoisted into position at Changjiang Unit 4 in Hainan province on April 15, marking significant structural progress for the twin Hualong One units at that site [17].

Middle East & Africa. Egypt and Russia reaffirmed their commitment to the $25 billion El Dabaa Nuclear Power Plant, with Prime Minister Madbouly meeting Rosatom Director General Likhachev on April 14 to review construction progress and explore expanded cooperation [18]. In East Africa, Kenya's President Ruto opened the 2026 International Conference on Nuclear Energy in Nairobi on April 8, outlining plans to expand the country's current 3,300 MW capacity significantly, with Rwanda also signaling interest in nuclear reactor development [19].


Technology & Innovation

The NRC's Part 53 finalization is the regulatory breakthrough that the advanced reactor community has awaited for years. Unlike Parts 50 and 52, which were designed around light-water reactor technology and require exemptions for non-LWR designs, Part 53 replaces prescriptive requirements with high-level performance criteria, allowing applicants to use probabilistic risk assessments to demonstrate compliance [4]. This means that molten salt reactors, high-temperature gas reactors, liquid metal fast reactors, and microreactors can now pursue licensing without the burden of forcing their designs into LWR-shaped regulatory molds. Notably, Part 53 introduces "self-reliant-mitigation facilities"—reactors whose designs demonstrate compliance with safety performance criteria without reliance on human action—and permits "generally licensed reactor operators" instead of individually licensed operators, a potentially transformative cost reduction for SMR and microreactor deployment [4]. The rule also relaxes siting restrictions, allowing reactors in higher population density areas if societal benefits outweigh additional risks—a provision tailor-made for data center colocation. Meanwhile, First American Nuclear's EAGL-1 design leverages lead-bismuth eutectic cooling, which offers superior thermal performance to liquid sodium without sodium's chemical reactivity with air or water, eliminating the need for an intermediate heat-transfer loop [5]. The design's Bridge Power concept allows gas-fueled generation to begin immediately while the nuclear island undergoes NRC review, addressing the chronic revenue gap that has plagued advanced reactor development. A PNNL review under the DOE GAIN program has already concluded that EAGL-1 would be licensable under existing NRC criteria, with no new rules required [5].


Fusion Research

The fusion sector delivered two landmark results this week. On April 13, ITER announced that its plasma control system—designated iPCS—had successfully achieved first plasma on the KSTAR tokamak in Daejeon, Korea, during a campaign running from March 9–20 [6]. The system surpassed its performance targets by significant margins: peak plasma current exceeded 0.2 mega-amperes against a 0.1 MA target, and plasma duration reached approximately 0.8 seconds against a 100-millisecond target. Three complementary start-up scenarios—ohmic, electron cyclotron heating-assisted, and trapped particle configuration—were all successfully demonstrated. This is the first time ITER's control system has driven plasma on an operating tokamak, substantially de-risking the path to ITER's own first plasma operations. The UKAEA followed on April 14 with the launch of its 2026–2030 organisational strategy, backed by £2.5 billion in funding, centered on delivering the STEP fusion prototype power plant design, growing the UK fusion supply chain, completing new facilities at Culham, and cultivating the next generation of fusion scientists and engineers [7]. UKAEA CEO Tim Bestwick emphasized that fusion is at an "inflection point in 2026," with commercial plants anticipated within the next decade. The strategy identifies four interrelated challenges—effective fusion core, fuel self-sufficiency, systems integration, and affordability—and commits to advancing capabilities in plasma control, fuel cycle development, HTS magnets, robotics, and advanced computing [7].


Market & Economic Intelligence

The uranium spot price (U3O8) ended March at approximately $84.25 per pound, representing a two-month low and a decline from $86.95 in February and $94.28 in January [20]. However, by mid-April, fuel brokers were reporting a recovery to $86.00 per pound, driven by active face-to-face fuel-cycle meetings in Monaco between buyers and producers, fresh capital raising linked to physical uranium buying, and the supply-side constraint introduced by Kazatomprom's 10% production cut for 2026 [14][21]. The weekly trend is therefore cautiously upward. Kazatomprom's revised guidance—reducing nominal capacity from 32,777 to 29,697 tonnes and actual production to 27,500–29,000 tonnes—coupled with the removal of 25–35% of its output from the open market through Indian bilateral agreements, has structurally tightened the supply picture [8]. Uranium Energy Corp's Burke Hollow mine entering production in Texas adds marginal domestic U.S. supply but is insufficient to offset the Kazakh reduction [14]. On the institutional investment front, the U.S. government's $2.7 billion commitment to domestic uranium enrichment over the next decade continues to underwrite the bullish longer-term view, with uranium increasingly classified alongside lithium and rare earths as a strategic resource [20]. In the insurance sector, Marsh Risk's securing of comprehensive coverage for TerraPower's Kemmerer Unit 1 in Wyoming—believed to be the first full construction insurance program for a commercial-scale advanced nuclear plant in the U.S.—represents a milestone in de-risking next-generation nuclear projects for capital markets [22]. In Europe, the prospective establishment of a Polish nuclear insurance pool by end-2026 signals that the institutional infrastructure for nuclear finance is maturing even in newcomer countries [15].


Sources

All 22 sources
  1. "India's first fast-breeder nuclear reactor achieves criticality," Physics World, April 15, 2026
  2. "Wylfa power station can begin that promises 8,000 new jobs," BBC News, April 13, 2026
  3. "Rolls-Royce SMR Signs Landmark Agreement For Three Reactors At Wylfa," NucNet, April 13, 2026
  4. "NRC Finalizes a New Risk-Informed, Technology-Inclusive Regulatory Framework for Advanced Reactors," Perkins Coie / JDSupra, April 6, 2026; Federal Register correction published April 13, 2026
  5. "First American Nuclear Submits Regulatory Engagement Plan for Fast-Spectrum Small Modular Reactor (SMR)," PR Newswire, April 15, 2026
  6. "On KSTAR, ITER's plasma control system successfully takes charge," ITER, April 13, 2026
  7. "UKAEA unveils 2026-2030 fusion roadmap," Nuclear Industry Association / GOV.UK, April 14, 2026
  8. "Kazatomprom Adjusts 2026 Production Targets Amid Supply Chain Shifts," Skillings Mining Review, April 10, 2026
  9. "Landmark UK nuclear deal to cut reliance on foreign energy after Middle East tensions," The European, April 14, 2026
  10. "Lee and McCormick introduce bill to accelerate nuclear energy deployment," Federal Newswire, April 14, 2026
  11. "Three US states pave way for new nuclear," World Nuclear News, April 10, 2026
  12. "SaskPower signs agreement with Ontario power company on full-size nuclear," CTV News, April 16, 2026
  13. "Nuclear workforce expansion gets $20 million boost," Port Clinton News Herald, April 15, 2026
  14. "Uranium Energy Corp Commences Production at Burke Hollow," Newswire, April 8, 2026
  15. "Poland's first insurance pool for nuclear risks may be established by end-2026," Biznes PAP, April 2026
  16. "Construction of second Jinqimen unit begins," World Nuclear News, April 7, 2026
  17. "Outer dome installed at Changjiang unit 4," SightLine / U3O8, April 15, 2026
  18. "Madbouly, Rosatom chief review progress on El Dabaa nuclear project," Daily News Egypt, April 14, 2026
  19. "Kenya, Rwanda eye nuclear reactors," ANS Nuclear Newswire, April 8, 2026
  20. "Uranium prices are trading at two-month lows," ANS Nuclear Newswire, April 3, 2026
  21. "Uranium Energy Rallies as Fuel Cycle Tightness Lifts U3O8 to $86," Brave New Coin, April 16, 2026
  22. "Marsh Risk Secures Insurance for Construction of Nuclear Power Plant in Wyoming," Insurance Journal, March 26, 2026

Nuclear Pulse is an independent weekly intelligence briefing. All information is sourced from publicly available industry publications. No investment advice is provided.

© 2026 Nuclear Pulse — Compiled by Tollaskígyó

Apr 12Nuclear Pulse — April 12, 2026

Covering: this week
Published: April 12, 2026

Week of 6–12 April 2026


Summary

This week the nuclear sector was defined by the clash between accelerating institutional momentum and wartime peril, as the IAEA reported multiple military strikes near Iran's Bushehr nuclear power plant while the American Nuclear Society joined calls for maximum restraint around nuclear facilities. India's Prototype Fast Breeder Reactor achieved first criticality, advancing the country into the second stage of its three-stage thorium programme and signalling a new chapter in fuel-cycle sovereignty. The U.S. Nuclear Regulatory Commission completed its safety evaluation for TerraPower's Natrium reactor ahead of schedule and formally codified Part 53, a sweeping new licensing framework for advanced reactors that fundamentally reorients how the United States will regulate next-generation nuclear technology. Europe's energy-security anxieties, intensified by the Gulf crisis, drove a cascade of nuclear policy reversals from Belgium to Germany, while uranium spot prices held at two-month lows near $84.55/lb despite robust long-term demand signals.


Geopolitical & Strategic Analysis

The overarching mood of the nuclear industry this week was one of strategic urgency shadowed by armed conflict. The Middle East crisis—specifically, repeated military strikes near Iran's Bushehr nuclear power plant—placed nuclear safety at the centre of geopolitical discourse, with IAEA Director General Rafael Grossi reiterating his Seven Indispensable Pillars for nuclear safety during armed conflict and the American Nuclear Society adding its institutional weight to calls for restraint [1][2]. These developments underscore a fundamental tension: the same technology that dozens of nations are embracing for energy sovereignty is also uniquely vulnerable to military escalation, a reality that complicates Rosatom's parallel role as both Iran's partner at Bushehr and the world's most active nuclear exporter, building plants across Africa and the Middle East [3][4]. Meanwhile, India's fast breeder criticality transforms the country from a dependent uranium importer into a potential closed-fuel-cycle power, a shift with profound implications for energy sovereignty across the Global South [5]. The European Commission's decision to open a formal state-aid investigation into France's support for six new EDF reactors illustrates how nuclear ambition collides with market governance, even as the Gulf crisis makes the case for energy independence more urgent by the day [6]. Across every region, nuclear technology is being wielded as both soft power and strategic necessity—a duality that defined this week's developments.


Regional Developments

North America. The United States saw two landmark regulatory actions converge this week. The NRC completed its safety evaluation for TerraPower's Natrium sodium-cooled fast reactor in Kemmerer, Wyoming, a month ahead of an already accelerated timeline, clearing a critical path toward construction of the nation's first commercial advanced reactor [7]. Simultaneously, the NRC's Part 53 final rule—published in the Federal Register on 30 March and now entering force—establishes a risk-informed, technology-inclusive licensing pathway for advanced reactors, replacing decades of light-water-reactor-prescriptive regulation with performance-based safety cases, alternative siting criteria, factory fuel loading, and remote operations provisions [8]. The NRC also approved a 20-year license extension for Diablo Canyon through the mid-2040s, though the California legislature retains decisive authority over whether the plant actually operates beyond 2030 [9]. In Canada, Ontario Power Generation applied for a 20-year operating licence for the BWRX-300 SMR at Darlington, which would be the first G7 small modular reactor to enter service [10]. Uranium Energy Corp commenced production at its Burke Hollow ISR mine in South Texas, the newest operating uranium mine in the United States and a step toward rebuilding domestic fuel supply [11].

Europe. The energy shock cascading from the Middle East crisis amplified Europe's nuclear reversal with striking speed. The BBC's Europe editor documented a continent watching gas and petrol prices spiral, with German electricity futures trading at five times French rates—laying bare the cost of Germany's 2023 nuclear exit [12]. Belgium's parliament voted overwhelmingly to reverse its phase-out, Italy is preparing draft laws to repeal its longstanding nuclear ban, Greece opened a public debate on advanced reactors, and Sweden continued to push legislation easing rules for new nuclear plants [12][13]. Germany's economy minister publicly reopened the nuclear debate, acknowledging that the country must choose between gas dependence and nuclear re-engagement [14]. The UK's Great British Energy–Nuclear (GBE-N) continued building its SMR delivery team, while Hunterston B in Scotland transferred from EDF ownership to the Nuclear Decommissioning Authority, marking the first relicensing of an EDF advanced gas-cooled reactor site [15][16]. The European Commission, however, opened a formal state-aid investigation into France's plans to subsidise six new EPRs for EDF, a decision that could shape the financing model for European nuclear for a generation [6].

Asia. India's 500 MWe Prototype Fast Breeder Reactor at Kalpakkam achieved first criticality on 6 April, a milestone two decades in the making that moves the country into the second stage of its three-stage nuclear programme aimed at a closed thorium fuel cycle [5]. Prime Minister Modi called it "a decisive step towards harnessing our vast thorium reserves," and the achievement positions India to extract significantly more energy from its limited uranium resources while developing next-generation fuel-cycle capabilities [5]. In China, construction of the main nuclear island commenced at Unit 2 of the Jinqimen plant in Zhejiang province—a six-unit Hualong One project totalling roughly 120 billion yuan in investment—and the reactor pressure vessel was installed at Unit 2 of the Lianjiang plant in Guangdong [17][18]. South Korea restarted the Kori-2 reactor after a three-year shutdown, the first execution of the country's ageing-reactor life-extension pipeline [19]. The US–Japan $40 billion SMR agreement for BWRX-300 deployment in Tennessee and Alabama, though finalised in late March, continued to shape the Asian nuclear export landscape this week as details of the GE Vernova Hitachi partnership were digested [20].

Middle East & Africa. Kenya's President Ruto opened the 2026 International Conference on Nuclear Energy in Nairobi, outlining plans for a 2,000 MW nuclear plant in Siaya County with construction expected to begin in 2027 and operation by 2034 [21]. Rwanda is progressing toward deploying its first SMR in the 2030s, with an IAEA infrastructure review identifying good practices in government coordination and emergency preparedness [21]. Ethiopia signed a strategic roadmap with Rosatom for a nuclear power plant project, deepening Russia's footprint on the continent [22]. Egypt and Russia discussed accelerating construction at the El Dabaa nuclear power plant, where the fourth tier of reactor protection was installed at Unit 1 [3][23]. The Middle East crisis, however, cast a long shadow: the IAEA reported that a projectile struck near Bushehr—Iran's only operational nuclear power plant—killing one worker, while Iran's heavy water plant at Khondab sustained severe damage and the Ardakan yellowcake production facility was also attacked [1][24].


Technology & Innovation

The NRC's Part 53 rule represents the most consequential regulatory innovation in American nuclear licensing since 1989, and arguably since the original Part 50 framework of 1956. By shifting from prescriptive, light-water-reactor-specific requirements to a risk-informed, performance-based, technology-inclusive structure, Part 53 enables advanced reactor developers to submit safety cases built around probabilistic risk assessment rather than deterministic compliance with rules written for a technology generation that preceded them [8]. The rule introduces provisions for generally licensed reactor operators, factory fuel loading and transport, alternative siting near population centres, functional containment, remote operations, and load following—all capabilities that reflect how advanced reactors are actually designed to operate rather than forcing them into a regulatory mould shaped by large light-water reactors [8]. At TerraPower, the Natrium project passed its NRC safety evaluation ahead of schedule, with Acting NRC Office of Nuclear Reactor Regulation Director Jeremy Groom calling the accelerated timeline "a testament to our dedication to expediting licensing decisions for these advanced reactors" [7]. In the UK, GBE-N's ongoing team-building for SMR deployment and Rolls-Royce SMR's partnership with Sweden's Studsvik for nuclear analysis software signal steady progress in the European supply chain [15][25]. Ontario Power Generation's BWRX-300 licence application marks a regulatory milestone for SMRs in the G7, moving from design certification to operational licensing [10].


Fusion Research

China's Energy Singularity announced that its HH70 fully high-temperature superconducting tokamak in Shanghai achieved steady-state long-pulse plasma operation for 1,337 seconds, making it the first commercial entity worldwide to sustain plasma for over 1,000 seconds and demonstrating the engineering feasibility of HTS magnets for confinement [26]. The milestone is significant because HTS magnets dramatically reduce tokamak volume and construction costs compared to conventional low-temperature superconducting systems, potentially accelerating the path to commercial fusion. In the private sector, General Fusion announced a SPAC merger with Spring Valley Acquisition Corp. III that will make it the first publicly traded pure-play fusion company, with a pro-forma equity value of approximately US$1 billion and plans to list on Nasdaq under the ticker GFUZ [27]. The Vancouver-based company's Lawson Machine 26 demonstration is mechanically compressing plasma with a lithium liner at 50% commercial scale, advancing toward key fusion milestones including the Lawson criterion for net energy gain [27]. ITER also announced a public-private fusion workshop scheduled for late April, signalling continued institutional investment in the tokamak path even as private ventures proliferate [28].


Market & Economic Intelligence

Uranium spot prices traded at approximately $84.55 per pound U₃O₈ at the close of the week ending 4 April, up marginally from $83.95 at the start of the week but down roughly $10 from the January high of $94.28/lb, settling at two-month lows as the Middle East conflict maintained low risk sentiment for speculative assets [29][30]. Futures prices held in a narrow band around $85/lb, and the long-term uranium price remained anchored at $90/lb, reflecting continued structural demand despite near-term softness [30]. The spot market remains thin and responsive to small increments of demand, with just seven confirmed transactions totalling 500,000 lbs in the holiday-shortened week [30]. On the supply side, Uranium Energy Corp commenced production at its Burke Hollow ISR mine in South Texas—the first new U.S. uranium mine in over a decade—though total U.S. output of 2.16 million lbs in 2025 still covers only a small fraction of domestic reactor requirements [11][30]. Paladin Energy's Langer Heinrich mine in Namibia is approaching full nameplate capacity of 6 million lbs annually, with production costs falling to $39.70/lb, providing a useful reality check on how long supply ramp-ups actually take [30]. The European Commission's state-aid investigation into France's six-reactor programme for EDF introduces regulatory uncertainty into the continent's largest nuclear investment pipeline [6]. On the insurance front, Marsh Risk secured comprehensive coverage for TerraPower's Kemmerer Unit 1 project in late March, marking a significant milestone for next-generation nuclear construction risk underwriting [31]. UEC reported selling uranium at $101/lb under its unhedged strategy, demonstrating the premium available to producers willing to sell into the spot market [32].


Sources

  1. American Nuclear Society, "IAEA provides updates on Iran nuclear facilities," 6 April 2026.
  2. American Nuclear Society, "ANS joins IAEA in calling for protection of nuclear plants in armed conflicts," 6 April 2026.
  3. Daily News Egypt, "Electricity Minister, Rosatom officials review progress on Egypt's Dabaa nuclear power plant," 24 March 2026; Asharq Al-Awsat, "Egypt, Russia Hope to Speed up Construction of El Dabaa Nuclear Plant," 11 April 2026.
  4. Sputnik Africa, "Ethiopia, Rosatom Discuss Nuclear Power Plant Project, Sign Strategic Roadmap," 2 April 2026.
  5. World Nuclear News, "First criticality for Indian fast breeder reactor," 7 April 2026.
  6. Reuters, "EU opens probe into French state aid to EDF's nuclear expansion," 31 March 2026; News Europe, "Commission opens formal state aid assessment of French support to new nuclear programme," April 2026.
  7. Kemmerer Today / National Today, "NRC Completes Safety Review for Wyoming's Natrium Advanced Reactor – Ahead of Schedule," 10 April 2026.
  8. Orrick, "NRC Issues New Licensing Pathway for Advanced Reactors," 2 April 2026; Federal Register, "Risk-Informed, Technology-Inclusive Regulatory Framework for Advanced Reactors," 30 March 2026; JDSupra / Perkins Coie, "NRC Finalizes a New Risk-Informed, Technology-Inclusive Regulatory Framework for Advanced Reactors," 6 April 2026.
  9. California Energy Journal, "NRC Approves Diablo Canyon License Extension to 2045, Shifting Decision to California Legislature," 6 April 2026.
  10. World Nuclear News, "OPG applies for operating licence for BWRX-300 SMR," 2 April 2026.
  11. SightLine / U308, "Uranium Energy Corp Commences Production at Burke Hollow," April 2026; IndexBox, "Uranium Energy Corp Begins Production at New Texas Mine in 2026," 10 April 2026.
  12. BBC News, "Faced with new energy shock, Europe asks if reviving nuclear is the answer," 4 April 2026.
  13. Global Construction Review, "Belgium's parliament votes overwhelmingly for nuclear U-turn," 2026; Nuclear Engineering International, "Sweden To Streamline Licensing Process And 'Open Coastline' For New Nuclear Plants," 2026.
  14. Purepoint Uranium Group, "Uranium Spotlight for April 7, 2026," 7 April 2026.
  15. GOV.UK, "GBE-N Continues to Build Delivery Team for First SMRs," 2 April 2026.
  16. GOV.UK, "Hunterston B nuclear power station has transferred to the NDA," 1 April 2026; Office for Nuclear Regulation, "Nuclear Restoration Services becomes new licensee of Hunterston B," 1 April 2026.
  17. MarketScreener, "China National Nuclear Power Pours Concrete on Zhejiang Jinqimen Nuclear Power Plant's Unit 2," 7 April 2026.
  18. World Nuclear News, "Reactor vessel installed at Lianjiang unit 2," 2 April 2026.
  19. Yonhap, "S. Korea restarts operation of Gori-2 nuclear reactor," 4 April 2026; Korea Pro, "South Korea restarts Kori-2, advancing nuclear reactor life-extension push," 2026.
  20. NucNet, "US and Japan announce $40 billion deal for SMRs in Tennessee and Alabama," 20 March 2026.
  21. American Nuclear Society, "Kenya, Rwanda eye nuclear reactors," 8 April 2026.
  22. Business Insider Africa, "Ethiopia edges closer to nuclear power with a major Russian deal and its new roadmap," 2 April 2026.
  23. Rosatom, "Main construction phase for El Dabaa nuclear power plant project begins in Egypt," 2026; Rosatom, "The fourth tier of reactor protection installed at the first power unit of the El Dabaa NPP," 1 April 2026.
  24. Iran Mirror / Tasnim, "Iran Warns UN, IAEA of 'Grave Radiological Risk' from US-Israeli Attacks on Nuclear Facilities," 5 April 2026.
  25. Studsvik, "Rolls-Royce SMR strengthens global supply chain with Studsvik partnership," 25 March 2026.
  26. Yicai Global, "World's First Fully HTS Tokamak in Shanghai Holds Steady Operations for 1,337 Seconds," 1 April 2026.
  27. General Fusion, "General Fusion to Become First Publicly Traded Pure-Play Fusion Company Through Business Combination with Spring Valley Acquisition Corp. III," 22 January 2026; Minichart / SEC filings, updated investor presentation, 7 April 2026.
  28. ITER, "3rd Public-Private Fusion Workshop at ITER (28-29 April 2026)," 2026.
  29. American Nuclear Society / Cameco, "Uranium prices are trading at two-month lows," 3 April 2026.
  30. Purepoint Uranium Group, "Uranium Spotlight for April 7, 2026," 7 April 2026.
  31. Insurance Journal, "Marsh Risk Secures Insurance for Construction of Nuclear Power Plant in Wyoming," 26 March 2026.
  32. Uranium Energy Corp, "UEC Reports Results for Second Quarter of Fiscal 2026," April 2026.

Sources

All 0 sources

Nuclear Pulse is an independent weekly intelligence briefing. All information is sourced from publicly available industry publications. No investment advice is provided.

© 2026 Nuclear Pulse — Compiled by Tollaskígyó

Apr 5Nuclear Pulse — April 5, 2026

Covering: this week
Published: April 5, 2026

Date: April 5, 2026 Week: 14/2026


Summary

This week marked significant progress in global nuclear deployment with Canada's Ontario Power Generation submitting its operating license application for the first BWRX-300 small modular reactor at Darlington, poised to become the first SMR operational in a G7 nation. Holtec's SMR-300 achieved a critical milestone by completing Step 2 of the UK's Generic Design Assessment, clearing fundamental regulatory hurdles for potential deployment. In Asia, Uzbekistan officially launched construction of its first nuclear plant featuring a unique combination of VVER-1000 and RITM-200N reactors. The European Commission unveiled an ambitious strategy to bring Europe's first SMRs online by the early 2030s, while X-energy and Talen Energy signed a letter of intent to evaluate gigawatt-scale Xe-100 SMR deployment across the PJM market. TerraPower received final approval from the US NRC for its Natrium reactor in Wyoming, representing the first commercial reactor approval in the United States in nearly a decade.


Global Overview

The nuclear energy sector continues its momentum with multiple construction milestones and regulatory approvals across continents. The industry is witnessing a convergence of factors driving renewed interest in nuclear power: energy security concerns, decarbonization commitments, and the growing power demands of data centers and AI infrastructure. Small modular reactors (SMRs) remain at the forefront of development, with several designs advancing through regulatory pathways in the US, UK, Canada, and Europe. Construction activities are accelerating in Asia, Europe, and North America, signaling a robust global pipeline of new nuclear capacity.


Regional Sections

North America

Canada: Darlington SMR Project Advances

Ontario Power Generation (OPG) submitted its operating license application to the Canadian Nuclear Safety Commission (CNSC) on March 25, 2026, for the first BWRX-300 small modular reactor at the Darlington New Nuclear Project. This reactor is expected to be the first SMR operational in any G7 country. The CNSC also removed the first regulatory hold point, allowing OPG to proceed with the reactor building foundation installation.

The BWRX-300, designed by GE Vernova Hitachi Nuclear Energy, is a 300 MWe water-cooled, natural circulation SMR with passive safety systems. The project represents a CAD 20.9 billion (USD 15 billion) investment expected to create up to 18,000 Canadian jobs and add CAD 38.5 billion to the country's GDP over 65 years. The first unit is targeted for grid connection by the end of 2030.

United States: TerraPower Approval and SMR Developments

The US Nuclear Regulatory Commission (NRC) approved construction for TerraPower's Natrium sodium-cooled reactor in Kemmerer, Wyoming, the first commercial reactor approval in the United States in nearly a decade. The 345 MW plant, backed by Bill Gates, will run on high-assay low-enriched uranium (HALEU) and includes an energy storage system capable of temporarily boosting output to 500 MW. TerraPower expects to begin construction in the coming weeks and submit an operating license application in late 2027 or early 2028.

X-energy and Talen Energy signed a Letter of Intent to evaluate deploying X-energy's Xe-100 SMRs across Pennsylvania and the PJM Interconnection market. The companies plan to explore transitioning fossil-fired generation to nuclear power through three or more four-unit Xe-100 plants. The Xe-100 is an 80 MW high-temperature gas-cooled reactor designed for industrial applications and data center power.


Europe

United Kingdom: Holtec SMR-300 Clears Regulatory Step

Holtec International's SMR-300 design successfully completed Step 2 of the UK's Generic Design Assessment (GDA), with the Office for Nuclear Regulation (ONR), Environment Agency, and Natural Resources Wales confirming no fundamental shortfalls that would prevent deployment in Great Britain. The assessment covered 21 technical topic areas with 14 regulatory observations identified for resolution.

Holtec, in partnership with EDF Energy and Tritax, plans to deploy SMR-300 reactors at the former Cottam coal-fired power plant site in Nottinghamshire, England, to power new data centers. The project targets 1 GW of data center capacity online by the end of the decade, with SMR operations beginning in the 2030s.

European Commission SMR Strategy

The European Commission unveiled a comprehensive strategy to accelerate SMR and Advanced Modular Reactor (AMR) deployment in Europe, targeting first projects online by the early 2030s. The strategy emphasizes fleet-based industrial deployment, closer supply chain cooperation, and regulatory harmonization. According to the Nuclear Illustrative Programme (PINC), SMR capacity in the EU could reach between 17 GW and 53 GW by 2050, requiring approximately EUR 241 billion in investments.

Finland: Steady Energy Pilot Plant

Finnish SMR developer Steady Energy began construction of a full-scale non-nuclear pilot of its LDR-50 reactor at the decommissioned Salmisaari coal-fired power station in Helsinki. The 50 MW thermal output reactor is designed for district heating applications. The pilot will test operational features and establish supply chains, with an output of about 6 MW when completed.

Hungary: Paks II Construction Progress

The Paks II nuclear project officially entered the construction phase under IAEA standards with the pouring of first concrete for Unit 5 on February 5, 2026. The project involves two VVER-1200 Generation III+ reactors being built by Rosatom, with a total capacity of 2,400 MW. Once completed, the plant will enable Hungary to independently produce up to 70% of its electricity needs.

Poland: Nuclear Plant Development

Polskie Elektrownie Jądrowe (PEJ) signed an amendment with the Westinghouse-Bechtel Consortium to continue engineering development work for Poland's first AP1000 nuclear plant at the Lubiatowo-Kopalino site. The project received PLN 4.6 billion in state funding and PLN 60.2 billion in budget allocation through 2030. The first reactor is targeted for commercial operation in 2033.


Asia

Uzbekistan: First Nuclear Plant Construction

Uzbekistan launched construction of its first nuclear power plant in the Farish district of the Jizzakh region on March 24, 2026. The unique project configuration includes two large-capacity VVER-1000 Generation 3+ reactors and two small-capacity RITM-200N reactors with 55 MW capacity each. At full capacity, the plant will generate approximately 15–17 billion kWh annually, providing over 15% of Uzbekistan's electricity consumption. The project is being implemented by Rosatom under the personal guidance of President Shavkat Mirziyoyev.

China: Multiple Construction Projects

China began construction of two new CAP1000 reactors at the Bailong nuclear power plant in Guangxi Zhuang Autonomous Region and unit 2 at the Lufeng plant in Guangdong Province. The Bailong Phase I project involves an investment of approximately CNY 40 billion (USD 5.6 billion) for two units with a total capacity of 2.5 GW. Upon completion, the plant is expected to generate about 20 billion kWh annually.

Additionally, China General Nuclear Power Group (CGN) announced that two Hualong One projects—the Taipingling unit 1 in Guangdong and San'ao unit 1 in Zhejiang—have commenced fuel loading, marking the transition to nuclear testing phases. Both units are expected to begin commercial operation in the first half of 2026.

Vietnam: Nuclear Cooperation with Russia

Vietnam and Russia signed an agreement for Rosatom to construct Vietnam's first nuclear power plant, the Ninh Thuan 1 project, with two VVER-1200 reactors totaling 2,400 MW capacity. Japan officially withdrew from the neighboring Ninh Thuan 2 project in January 2026, leading Vietnam to fast-track negotiations with Russia. The project had been suspended since 2016 due to cost concerns.


Middle East and Africa

No significant nuclear developments reported this week in the Middle East and Africa regions. The focus in these regions remains on early-stage planning and feasibility studies for potential nuclear programs.


Technology and Innovation

SMR Deployment Acceleration

The global SMR market is advancing rapidly with multiple designs progressing through regulatory approval processes. Key developments include:

  • Holtec SMR-300: Completed UK GDA Step 2; 300 MW pressurized water reactor
  • X-energy Xe-100: 80 MW high-temperature gas-cooled reactor; graphite supply agreement signed with SGL Carbon valued at over $100 million
  • GE Hitachi BWRX-300: First-of-a-kind under construction in Canada
  • Steady Energy LDR-50: 50 MW thermal district heating SMR pilot under construction in Finland

HALEU Fuel Developments

The Department of Energy awarded $900 million each to American Centrifuge Operating (Centrus Energy subsidiary) and General Matter to develop domestic high-assay low-enriched uranium (HALEU) production capabilities. This addresses a critical supply chain gap as HALEU has traditionally been produced in Russia.

TRISO-X, an X-energy subsidiary, received the first-ever Part 70 Special Nuclear Material License from the NRC for HALEU fuel fabrication, enabling commercial manufacturing at its TX-1 and TX-2 facilities.


Fusion Research

While no major fusion breakthroughs were reported this week, the sector continues its steady progress toward demonstration-scale facilities. The global fusion ecosystem is focusing on:

  • ITER construction milestones in France
  • Private sector developments at Commonwealth Fusion Systems, TAE Technologies, and Helion Energy
  • SPARC tokamak construction progress by Commonwealth Fusion Systems
  • Regulatory frameworks for fusion energy facilities

The fusion sector maintains strong momentum with significant private investment, though commercial deployment remains targeted for the 2030s.


Market and Economic News

Investment and Financing

  • Poland allocated PLN 60.2 billion (approximately USD 15.5 billion) in public funding for its nuclear program through 2030
  • Canada committed CAD 3 billion (USD 2.1 billion) in government equity financing for OPG's Darlington SMR project
  • TerraPower's Natrium project represents the first major US nuclear investment with NRC approval in nearly a decade

Supply Chain Developments

  • X-energy signed a 10-year graphite supply agreement with SGL Carbon worth over $100 million
  • X-energy and IHI Corporation signed a Memorandum of Understanding to expand US-Japan supply chain development for Xe-100 SMRs
  • Rolls-Royce SMR enhanced collaboration with Studsvik for UK deployment

Energy Security Context

The nuclear renaissance is being driven by multiple converging factors: energy independence imperatives, decarbonization commitments, and the massive power requirements of AI data centers. Several nations are accelerating nuclear programs as part of broader energy security strategies, including France, the UK, Canada, and countries in Eastern Europe.


Sources

All 14 sources
  1. World Nuclear News - OPG applies for operating licence for BWRX-300 SMR (April 2, 2026)
  2. World Nuclear News - Holtec SMR design clears key UK regulatory stage (March 31, 2026)
  3. Office for Nuclear Regulation (UK) - Holtec's SMR-300 completes Generic Design Assessment
  4. Reuters - US approves construction of Bill Gates-backed TerraPower reactor in Wyoming (March 4, 2026)
  5. Business Wire - X-energy, Talen Energy to Evaluate Gigawatt-Scale Xe-100 SMR Deployment (March 19, 2026)
  6. European Commission - Strategy to accelerate SMR deployment (March 10, 2026)
  7. World Nuclear News - Construction of Steady Energy pilot plant begins (February 17, 2026)
  8. UzDaily.uz - Uzbekistan Launches Construction of First Nuclear Plant (March 24, 2026)
  9. World Nuclear News - China begins construction of two new nuclear power units (January 5, 2026)
  10. ExchangeMonitor - OPG submits operating license for first Darlington SMR (April 2, 2026)
  11. Construction Review Online - Russia's Rosatom to Construct Vietnam's First Nuclear Power Plant (March 23, 2026)
  12. The Globe and Mail - Federal regulator approves Canada's first small modular reactor (April 5, 2025)
  13. Xinhua - Hungary's Paks II nuclear project officially enters construction phase (February 6, 2026)
  14. World Nuclear News - Agreement extension enables continued development of Polish plant (January 6, 2026)

Nuclear Pulse is an independent weekly intelligence briefing. All information is sourced from publicly available industry publications. No investment advice is provided.

© 2026 Nuclear Pulse — Compiled by Tollaskígyó

Mar 28Nuclear Pulse — March 28, 2026

Covering: this week
Published: March 28, 2026

Date: March 28, 2026


This week the nuclear sector focused on the rapid advancement of small modular reactors, while Japan restarted the world's largest power plant and China reaffirmed its nuclear expansion plans. The European Union provided a strategic framework for SMR development, and the United States and Japan signed a forty-billion-dollar partnership to spread the technology. Fusion research also brought a breakthrough: a British startup successfully ignited plasma in an experimental nuclear fusion rocket system. Uranium market tensions continued to rise due to growing demand and tightening supply.


Global Overview

Nuclear energy showed unprecedented dynamism in the first quarter of 2026. In March, the Nuclear Energy Summit in Paris formalized a commitment to triple global nuclear capacity by 2050 [1]. Behind the declaration lies the rapidly growing electricity demand from AI infrastructure and data centers, which current renewable sources would struggle to meet. China leads the expansion with thirty-three reactors under construction, while Japan restarted the world's largest nuclear plant for the first time in fifteen years. SMR and AMR development has moved to the center: both the European Union and the United States treat the technology as a strategic priority, and market players are announcing milestone after milestone. Uranium prices are holding up better than expected despite supply tensions.


North America

TerraPower received a historic permit in early March: the NRC approved the construction permit for the Natrium reactor being built in Kemmerer, Wyoming [2]. This is the first commercial-scale advanced nuclear plant to receive such approval in the United States in nearly a decade. The Bill Gates-backed project plans approximately three thousand five hundred megawatts of capacity and could become one of the flagship technologies replacing coal plants [3].

The United States and Japan signed a forty-billion-dollar strategic agreement for SMR development and export [4]. The deal is part of a five hundred fifty-billion-dollar trade package, and the two countries aim to jointly support the global spread of small modular reactors. Northeastern Alabama is planning new reactors under the framework [5].

The market side was also active. X-Energy, the Maryland-based advanced SMR developer, submitted its IPO registration documents for a public listing [6]. The company plans to raise approximately three hundred million dollars and is targeting the Nasdaq Global Select Market under the ticker symbol XE. This is the first major nuclear startup public offering in recent years.

NuScale Power signed a collaborative agreement with Ebara Elliott Energy to develop high-temperature steam compressors [7]. The technology could be critical for SMR industrial heat applications. As part of the development, integrated systems are being tested in commercial environments.

The fuel supply chain is also expanding. FluxPoint Energy announced at the end of March that it will build the first new American uranium conversion facility in nearly seven decades [8]. The Houston and McLean-based company will produce uranium hexafluoride (UF₆) from uranium dioxide, a critical step toward domestic fuel cycle security.


Europe

The European Commission adopted a strategic document in early March for the accelerated development of SMRs and AMRs [9]. According to the plan, the continent's first small modular reactors could come online in the early 2030s. Ursula von der Leyen announced the two hundred million euro guarantee fund at the Nuclear Energy Summit in Paris, financed through the EU emissions trading system [10].

The Commission document highlights that SMRs and AMRs can contribute to EU climate targets, energy independence, and industrial competitiveness. Technology supporters see potential in decentralized power generation, shorter construction times, and lower capital requirements. Critics, however, point to costs and unproven nature [11].

Some SMR developers are betting on Low Enriched Uranium Plus fuel to avoid potential supply bottlenecks for more advanced fuels [12]. This approach enables faster deployment, though it may raise longer-term efficiency questions.


Asia and Oceania

China reaffirmed continued nuclear expansion in its 15th Five-Year Plan [13]. The plan covers the 2026-2030 period and supports increasing nuclear power capacity as part of energy structure transformation. Currently 58 reactors operate in the country with approximately 56.4 GW installed capacity, with another 33 units under construction [14]. This is the second largest operating reactor park after the United States.

China joined the global declaration aiming to triple nuclear capacity by 2050 [15]. The country has already introduced the world's first commercial fourth-generation high-temperature gas-cooled reactor and is building the first land-based small modular reactor, expected to come online this year [16].

Japan restarted Unit 6 of the Kashiwazaki-Kariwa nuclear power plant in February [17]. The facility in Niigata Prefecture is the world's largest nuclear plant by nominal capacity and had been idle for fifteen years following the 2011 Fukushima disaster. The restart marks a milestone in Japan's energy policy, which is returning to nuclear power to reduce fossil fuel imports and meet climate goals [18]. At full capacity, the reactor is expected to displace natural gas-based electricity generation [19].


Middle East and Africa

Vietnam and Russia signed an intergovernmental agreement to build the Ninh Thuan 1 nuclear power plant [20]. Southeast Asia's first nuclear facility would receive two VVER-1200 reactors, modeled after the new units at Russia's Leningrad plant [21]. The contract is part of Hanoi's strategy to increase energy security amid Middle East conflict disruptions [22].

Uzbekistan aims to increase localization in its nuclear plant project [23]. According to the Uzatom director, the current domestic share is about 29-30 percent, with plans to increase this in coming years. The planned Uzbek nuclear plant would be the Central Asian country's first nuclear capacity.

Construction of new units at Iran's Bushehr nuclear plant has stopped due to the Middle East conflict [24]. Russian Rosatom announced that work has been suspended due to the security situation.


Technology and Innovation

TerraPower's Natrium reactor is the first American commercial-scale advanced reactor to receive a construction permit [2]. The technology uses liquid sodium as coolant and operates at higher temperatures than conventional pressurized water reactors, increasing efficiency. The Bill Gates-backed project is being built on the site of a closed coal plant in Kemmerer, Wyoming.

Some SMR developers are betting on Low Enriched Uranium Plus fuel [12]. This fuel type uses a lower enrichment level than the HA-LEU required for advanced reactors, potentially avoiding supply bottlenecks for more sophisticated fuels. The approach represents a trade-off in efficiency but enables faster market entry.


Fusion Research

British company Pulsar Fusion announced on March 25 that it successfully achieved first plasma in its Sunbird experimental nuclear fusion rocket system [25]. The breakthrough brings scientists closer to fusion propulsion, which mimics the Sun's energy production process. The technology could open a new era in deep space exploration.

In Japan, the Large Helical Device completed its final experimental campaign after nearly three decades [26]. The device set world records and demonstrated that stellarators offer a stable and reliable path to fusion energy. Research conducted in collaboration with the Princeton Plasma Physics Laboratory contributed to technology development.

The United Kingdom allocated 2.5 billion pounds for fusion research [27]. The investment is part of a strategy for the country to take a leading role in commercial fusion energy development.


Market and Economic News

Uranium prices stood at 84.05 USD/lbs at the end of March, 30.61 percent higher than a year earlier [28]. The price fell 2.78 percent during the month, but the longer-term trend remains upward. Industry experts cite growing demand, supply tensions, and geopolitical competition for fuel as drivers pushing prices higher [29].

At the March Nuclear Energy Summit, participants formally committed to tripling global nuclear capacity by 2050 [1]. The declaration is reshaping uranium markets and supply chain strategies, signaling long-term demand growth.

X-Energy's IPO announcement shows market interest in nuclear startups [6]. The company develops advanced SMRs and fuel technology, and the public offering could bring new capital to the sector.


Sources

All 29 sources
  1. Crux Investor – Nuclear Energy Summit Signals Long-Term Demand Growth, March 2026
  2. SVI News – Kemmerer Nuclear Plant Granted Construction Permit by NRC, March 4, 2026
  3. New York Times – TerraPower Nuclear Reactor in Wyoming Gets Federal Permit, March 4, 2026
  4. Nuclear Engineering International – US, Japan in SMR Deal, March 23, 2026
  5. Birmingham Free Press – New Nuclear Reactors Planned for North Alabama, March 25, 2026
  6. Grey Journal – Nuclear Reactor Startup X-Energy Files for $300 Million IPO on Nasdaq, March 20, 2026
  7. Yahoo Finance – NuScale Power SMR Partnership with Ebara Elliott Energy, March 2026
  8. Energy People Group – FluxPoint Energy Launches First New U.S. Uranium Conversion Facility, March 26, 2026
  9. European Commission – EU SMR Strategy, March 10, 2026
  10. NucNet – Von Der Leyen Sets Out EU SMR Strategy With €200M Guarantee, March 2026
  11. Euronews – Brussels Backs Mini-Nuclear Power Plants, March 10, 2026
  12. Reuters – Low Enriched Uranium Could Offer Faster Deployment of Small Reactors, March 24, 2026
  13. NucNet – China Draft Five-Year Plan Signals Continued Nuclear Build Programme, March 2026
  14. Power Magazine – China's Advanced Nuclear Efforts Are Pushing Frontiers, March 2026
  15. Columbia Energy Policy – China Briefing 19 March 2026: China Joins Nuclear Pledge
  16. Beijing Post – China Aims for Nuclear Expansion with Approval of 10 New Reactors, 2026
  17. EIA – Nuclear Reactor Restart in Japan Will Likely Displace Natural Gas, February 9, 2026
  18. BBC – Japan Restarts World's Largest Nuclear Plant, 2026
  19. Guardian – Japan Prepares to Restart World's Biggest Nuclear Plant, January 2026
  20. Reuters – Russia, Vietnam Agree Deal on Nuclear Power Plant Construction, March 23, 2026
  21. World Nuclear News – Vietnam, Russia Sign Agreement on New Nuclear Plant, March 2026
  22. Bloomberg – Vietnam, Russia Sign Nuclear Power Deal Amid Energy Pressure, March 24, 2026
  23. Kun.uz – Uzatom: Safety Remains Top Priority in Nuclear Plant Construction, March 25, 2026
  24. US News – Russia Halts Construction Work at Bushehr Nuclear Plant, March 3, 2026
  25. Euronews – UK Startup Ignites Plasma Inside Nuclear Fusion Rocket, March 26, 2026
  26. PPPL – After Record-Breaking Results in Fusion Research, March 2026
  27. The Fusion Report – UK Commits £2.5B to Fusion, March 20, 2026
  28. Trading Economics – Uranium Price, March 27, 2026
  29. Trading Century – Uranium Market Facing Supply Crunch as Nuclear Fleet Grows, March 12, 2026

Nuclear Pulse is an independent weekly intelligence briefing. All information is sourced from publicly available industry publications. No investment advice is provided.

© 2026 Nuclear Pulse — Compiled by Tollaskígyó